
Market Update For November 17, 2026
The Nigerian equities market returned to negative territory on Tuesday, November 17, 2026, as renewed profit-taking in heavyweight stocks reversed the previous session’s gains, putting pressure on the benchmark index. The downturn was largely driven by sell-offs in selected blue-chip stocks, particularly Dangote Cement and NGX Group, although buying interest in several consumer and financial services stocks helped limit the broader market decline.
Investor sentiment remained mixed throughout the session, with market participants seemingly taking advantage of recent price appreciation to lock in gains while selectively repositioning their portfolios in stocks with attractive valuations and growth prospects. The performance of the market also highlighted the continued influence of large-cap stocks on the direction of the benchmark index, as losses in a few heavyweight counters outweighed advances across several other equities.
The session’s performance reflects the market’s struggle to sustain its recent upward momentum following an extended period of strong year-to-date appreciation. With the NGX All-Share Index having recorded substantial gains in 2026, profit-taking activities are becoming increasingly evident, particularly in stocks that have experienced significant price rallies.
Despite the negative close, the relatively balanced market breadth suggests that investors have not completely withdrawn from equities. Rather, trading activity points to a selective approach, with buying interest concentrated in stocks offering potential short-term returns and opportunities for portfolio repositioning.
Trading activity weakened during the session, reflecting a decline in market participation compared with the previous trading day. Total volume traded fell by 16.27% to 564.06 million shares, valued at ₦22.77 billion across 31,041 deals. The moderation in turnover indicates a reduction in trading intensity, although significant transactions in selected banking and financial services stocks continued to support overall market activity.
NEM dominated the volume chart, exchanging 131.22 million shares, representing 23.26% of total market volume. The stock’s strong participation highlights sustained investor interest in selected insurance and financial services counters. FCMB and ACCESSCORP also featured prominently, accounting for 11.17% and 6.92% of total volume traded, respectively.
On the value chart, STANBIC led with transactions worth ₦3.73 billion, representing 16.38% of total market value. NEM and ZENITHBANK followed, reflecting continued interest in selected financial services and banking stocks.
The concentration of trading activity in financial services counters underscores the sector’s continued importance to overall market liquidity. However, the broader market performance suggests that investors are becoming more selective, balancing opportunities for capital appreciation against the need to protect existing portfolio gains.
Profit-Taking Weighs on Large-Cap Stocks
The market’s negative performance was largely influenced by renewed selling pressure in heavyweight stocks, with Dangote Cement recording the steepest decline among the major market movers. The stock’s 9.99% loss exerted considerable pressure on the benchmark index, reinforcing the impact of large-cap counters on overall market direction.
NGX Group also recorded a notable decline of 4.16%, while OANDO shed 1.91% and TIP lost 1.73%. Other significant stocks, including GTCO and ACCESSCORP, declined by 0.68% and 0.37%, respectively.
The weakness in these stocks suggests that investors are increasingly cautious about maintaining positions in equities that have recorded substantial price appreciation. Such profit-taking activities are a normal feature of an advancing market, particularly when valuations become stretched and investors seek to preserve accumulated gains.
Nevertheless, the continued performance of selected mid-cap and consumer stocks indicates that the market is not experiencing a complete loss of buying interest. Instead, investors appear to be rotating funds across sectors in search of better risk-adjusted opportunities.
Oil Market
In the international commodities market, crude oil prices extended their decline on Tuesday as expectations of excess global supply outweighed concerns over renewed tanker attacks in the Gulf. Brent crude traded around $92 per barrel, while US West Texas Intermediate (WTI) declined to $85.28.
Technical Analysis and Market Outlook
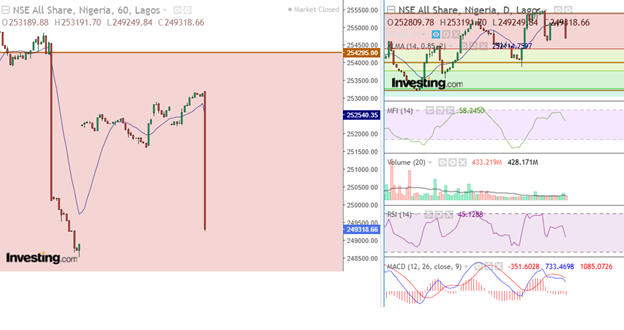
From a technical perspective, the NGX All-Share Index experienced renewed selling pressure after failing to sustain its previous session’s positive momentum. The 1.38% decline pushed the benchmark below the psychological 250,000-point level, suggesting that sellers are gradually gaining influence in the short-term market direction.
The inability to maintain the 250,000-point threshold raises the possibility of further consolidation, particularly if selling pressure persists in heavyweight stocks. However, the positive market breadth provides a degree of support for the underlying market structure, as advances in selected equities indicate that investors are still willing to take positions despite the broader weakness.
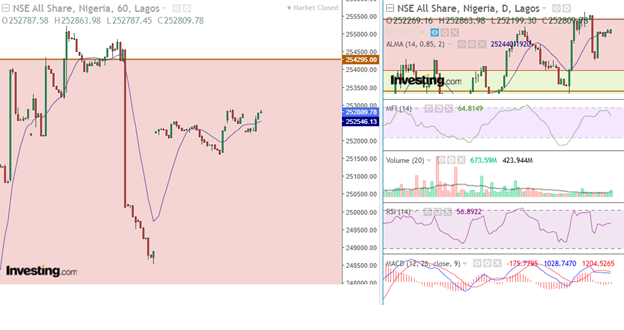
The 248,000–249,000-point region remains an important immediate support area to monitor, while the 252,800–253,000-point range represents the nearest resistance zone. A sustained break below the support region could expose the market to additional downside pressure, whereas a recovery above 250,000 points may improve sentiment and encourage renewed buying interest.
Market direction in the coming sessions will likely depend on the performance of banking, industrial and consumer stocks, particularly those with significant influence on the benchmark index. Investors are also expected to remain attentive to corporate earnings, dividend expectations, monetary policy developments and other macroeconomic indicators that could influence asset allocation decisions.
We expect cautious trading in the near term as investors continue to rebalance portfolios following the market’s strong year-to-date performance. Although profit-taking may create temporary pressure on the index, the underlying interest in fundamentally sound stocks could provide opportunities for selective accumulation. Investors should therefore prioritise earnings quality, valuation, liquidity and dividend sustainability rather than chasing short-term price movements.
At the close of trading, the NGX All-Share Index declined by 1.38% to 249,318.65 points from 252,809.78 points recorded in the previous session, while market capitalisation shed approximately ₦2.27 trillion. The market’s year-to-date return moderated to 60.22%. Total volume traded fell by 16.27% to 564.06 million shares, valued at ₦22.77 billion across 31,041 deals. Market breadth remained positive, with 26 gainers against 24 decliners. The major market movers were DANGCEM (-9.99%), NGXGROUP (-4.16%), OANDO (-1.91%), TIP (-1.73%), GTCO (-0.68%) and ACCESSCORP (-0.37%). On the gainers’ table, CADBURY led with a 10.00% appreciation to ₦62.70, followed by LIVESTOCK (+9.87%) at ₦12.80, AFRIPRUD (+9.80%) at ₦11.20, INTBREW (+9.78%) at ₦10.10 and ETRANZACT (+7.81%) at ₦17.25. Conversely, DANGCEM topped the losers with a 9.99% decline to ₦1,323.00, followed by JOHNHOLT (-9.71%) at ₦7.90, REDSTAREX (-9.60%) at ₦11.30, RTBRISCOE (-6.67%) at ₦7.70 and CAVERTON (-4.17%) at ₦4.60.