Market Update For November 18, 2026
The Nigerian equities market extended its bearish run on Wednesday, November 18, 2026, as sustained profit-taking in heavyweight stocks weakened investor sentiment and pushed the benchmark index lower for a second consecutive session. Selling pressure across selected banking, industrial and consumer stocks outweighed gains in some mid- and small-cap counters, reflecting a cautious trading environment as investors continued to lock in profits following the market’s strong year-to-date performance.
The downturn highlighted growing resistance at elevated market levels, with investors becoming more selective in positioning across sectors. Although some stocks attracted bargain-hunting interest, demand was insufficient to offset losses in key blue-chip counters, particularly ARADEL, ETRANZACT, ZENITHBANK and other actively traded equities.
The banking sector remained among the notable contributors to the market’s weakness, as ZENITHBANK declined by 2.59%, UBA lost 1.23%, GTCO shed 0.85%, while UCAP depreciated by 0.61%. INTBREW also recorded a marginal decline of 0.99%. These losses reflected continued portfolio adjustments and profit-taking in stocks that have benefited from previous market rallies.
ARADEL recorded the steepest decline among the major stocks, falling by 10.00%, while ETRANZACT dropped 9.86%. MEYER and CHAMPION also recorded substantial losses of 8.86% and 8.85%, respectively. CAVERTON declined by 8.70%, further highlighting the weakness across selected industrial and consumer-related counters.
Despite the negative performance, buying interest remained visible in selected equities, particularly lower-priced stocks that attracted speculative and bargain-hunting activity. However, the relatively narrow difference between advancing and declining stocks suggested that the market was experiencing mixed sentiment rather than a broad-based sell-off.
Trading activity weakened during the session, indicating reduced participation as investors adopted a more cautious approach. Total traded volume declined by 20.03% to 451.10 million shares, while transaction value stood at ₦26.59 billion across 32,491 deals. The decline in volume suggests that some investors are becoming more selective, waiting for clearer market direction before committing additional funds.
FIRSTHOLDCO maintained its dominance in market activity, accounting for 62.65 million shares, representing 13.89% of total traded volume. The stock also recorded the highest transaction value of ₦6.67 billion, equivalent to 25.09% of the day’s total value. ACCESSCORP and ZENITHBANK followed in volume contribution with 9.41% and 7.35%, respectively, while ZENITHBANK and GTCO ranked behind FIRSTHOLDCO in traded value.
The concentration of trading activity in major financial stocks underscores the continued importance of the banking sector in determining market direction. However, the inability of buying interest in these counters to offset losses elsewhere reflects the cautious positioning of investors amid ongoing portfolio adjustments.
Oil Market
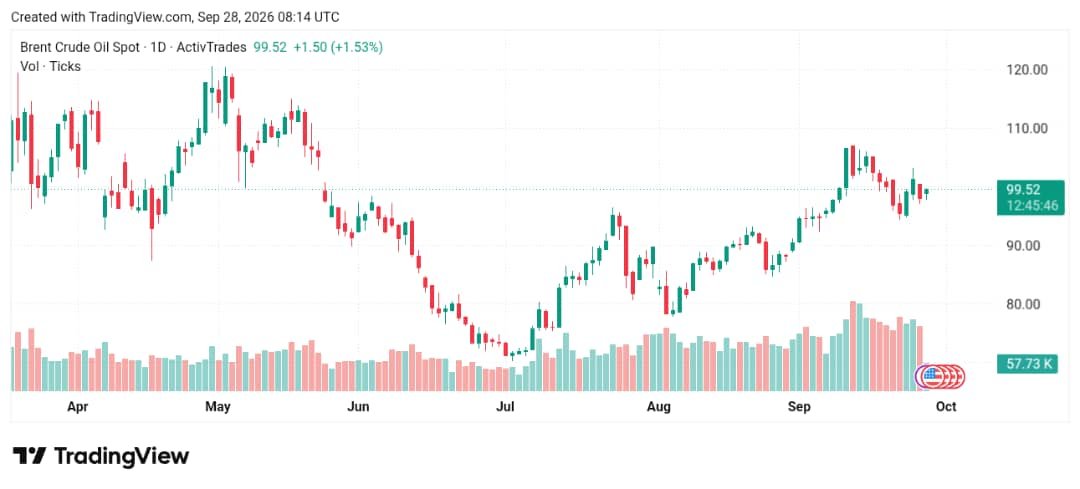
International oil prices declined on Wednesday as rising US petroleum inventories reinforced concerns about near-term supply conditions, outweighing some of the geopolitical risks supporting the market.
Brent crude futures dropped by $1.15, representing a 1.2% decline, to $91.99 per barrel, while US West Texas Intermediate (WTI) crude fell by $1.67, or 2.0%, to $84.34 per barrel.
The price weakness followed a significant increase in US crude inventories, which rose by 5.28 million barrels in the week ended November 13. Gasoline inventories also recorded a substantial increase of 5.12 million barrels, while distillate stocks gained 351,000 barrels.
Technical Analysis and Market Outlook
From a technical perspective, the NGX All-Share Index is showing signs of short-term weakness following two consecutive sessions of losses. The latest decline suggests that selling pressure is gradually increasing as investors take profits after the substantial gains recorded across the market this year.
The index’s retreat from the 249,000-point region raises questions about the sustainability of the recent upward momentum, particularly as heavyweight stocks continue to experience selling pressure. The 248,000-point level remains an immediate support area to watch, while a decisive break below this region could expose the market to further downward movement.
On the upside, the 249,500-point region represents an immediate recovery threshold, with stronger buying interest required to push the index towards higher resistance levels. A sustained move above this area would help improve the technical outlook and suggest that bargain hunters are gradually returning to the market.
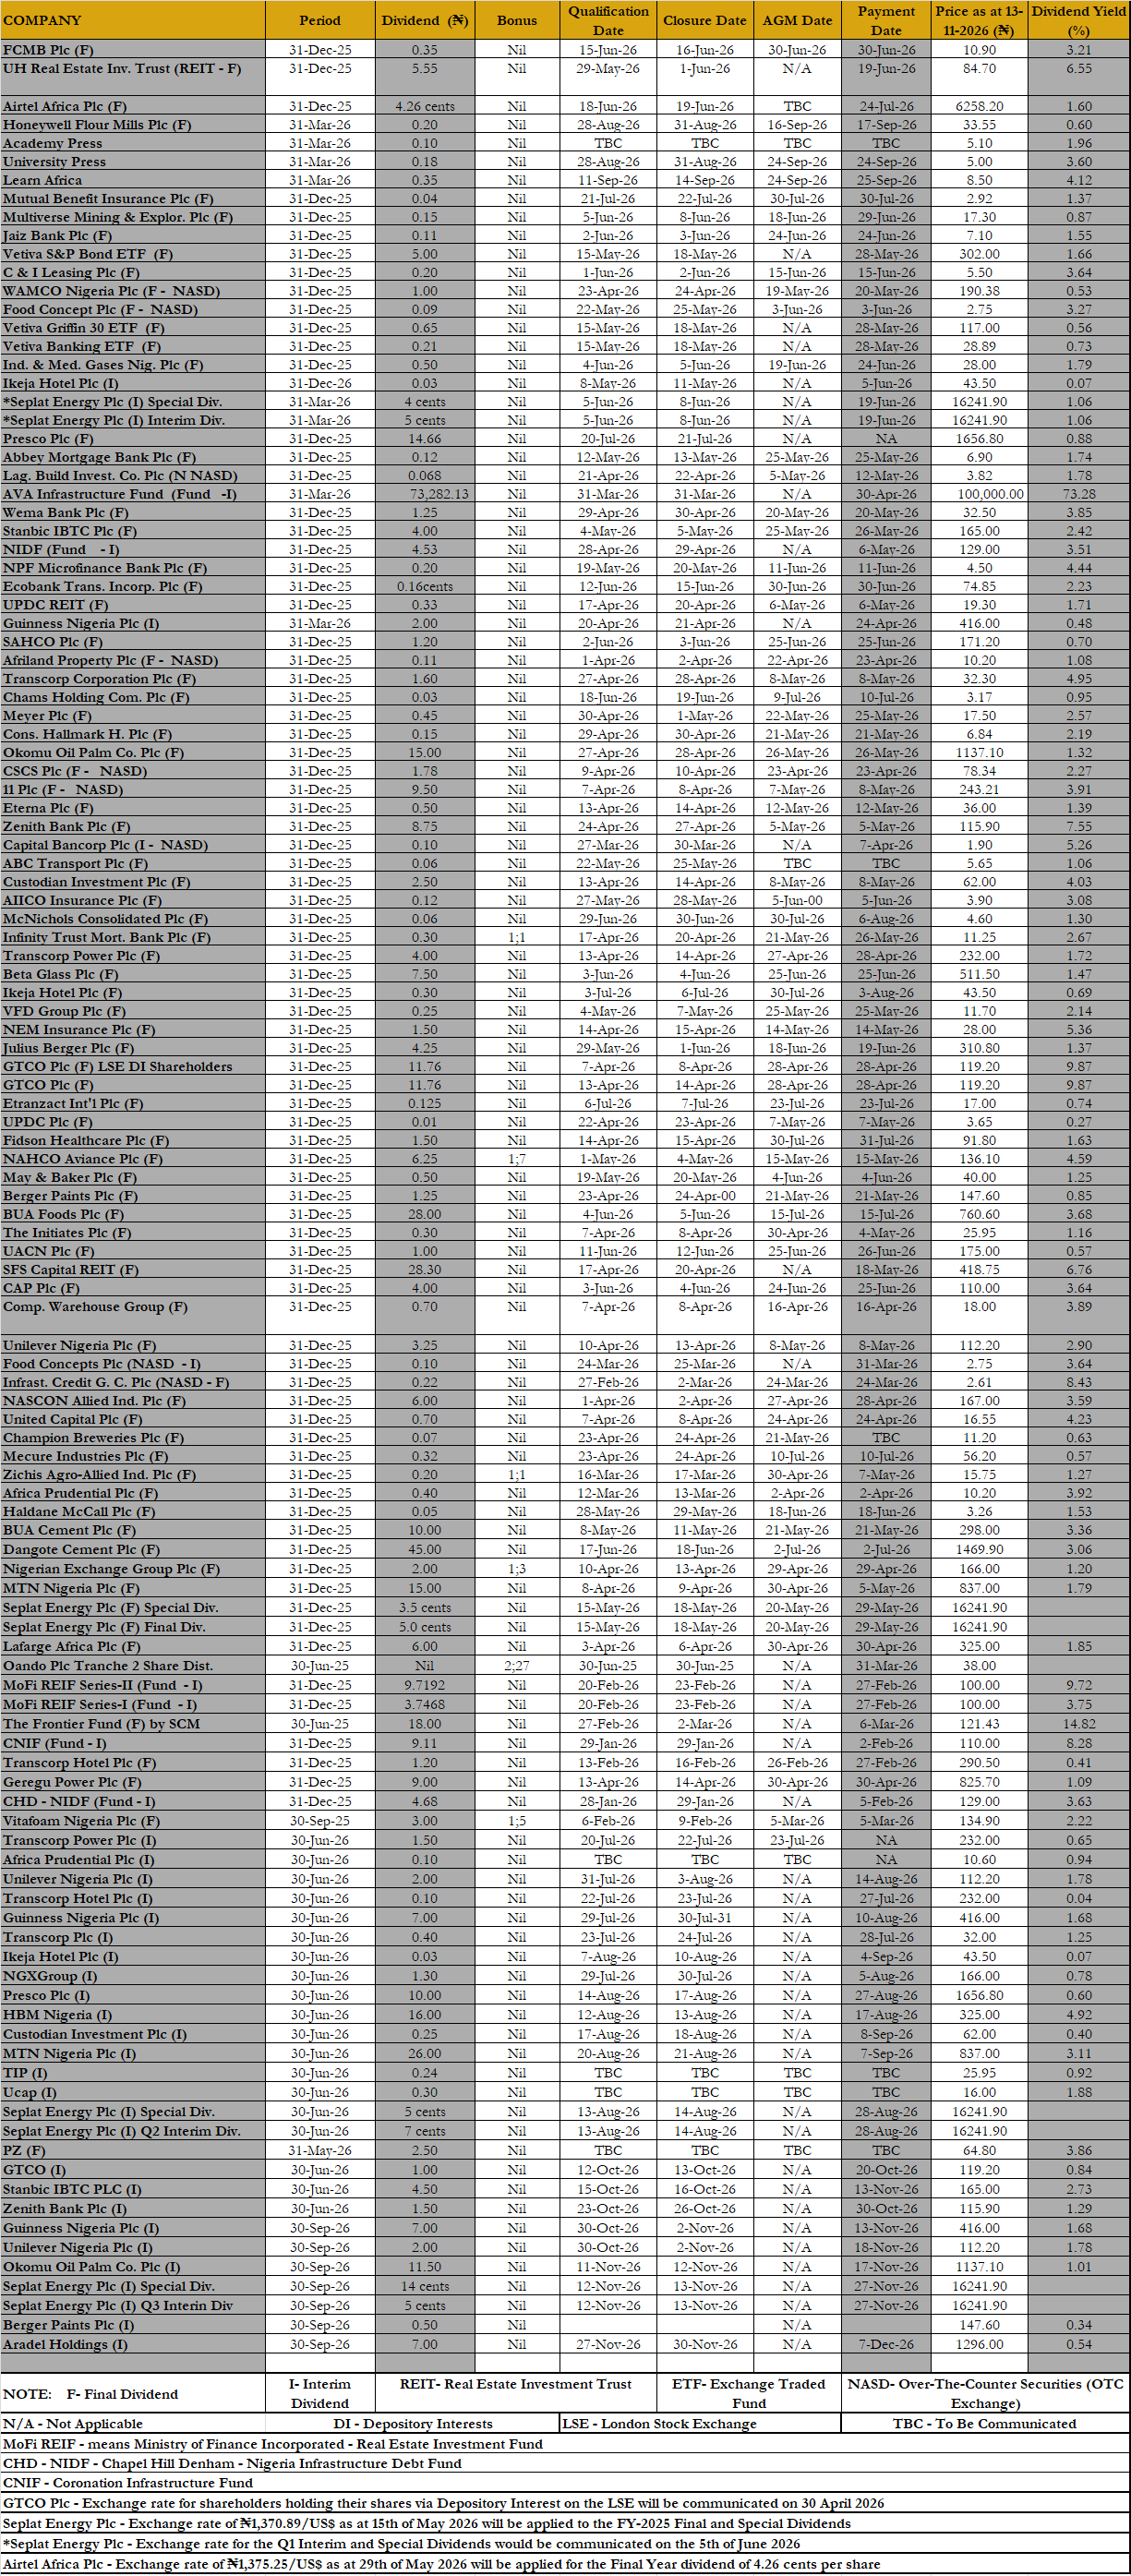
The market’s recent behaviour also suggests a transition from broad-based appreciation towards more selective stock performance. Investors appear increasingly focused on taking profits in equities that have recorded significant price gains, while directing attention towards stocks with attractive valuations, strong earnings potential and sustainable dividend prospects.
Market breadth remains an important indicator to monitor. Although the number of declining stocks was only marginally higher than advancing equities, continued weakness in large-cap counters could place additional pressure on the benchmark index if institutional buying interest remains subdued.
For the next trading session, the outlook is cautiously bearish, with profit-taking likely to persist in stocks that have experienced substantial appreciation. However, selective bargain hunting could provide some support, particularly in fundamentally strong companies trading at relatively attractive valuations.
Investors are therefore expected to remain selective, with attention focused on corporate earnings, dividend expectations, macroeconomic developments and sector-specific opportunities. A recovery in heavyweight stocks, supported by improved market turnover, would be necessary to restore positive momentum and strengthen the broader market outlook.
Overall, the market remains fundamentally supported by its strong year-to-date return, but elevated valuations and intermittent profit-taking could encourage further consolidation in the near term. Investors may find better opportunities in fundamentally sound stocks rather than chasing short-term price movements.
The NGX All-Share Index declined by 0.40%, shedding 989.00 points to close at 248,329.65, compared with 249,318.65 recorded in the previous session. Market capitalisation contracted by approximately ₦642.15 billion, while the year-to-date return moderated to 59.58%. Total trading volume fell by 20.03% to 451.10 million shares, valued at ₦26.59 billion across 32,491 deals. Market performance remained mixed, with 26 advancing stocks against 27 decliners, reflecting slightly negative market breadth. FIRSTHOLDCO dominated trading activity by both volume and value, accounting for 13.89% of total shares traded and 25.09% of transaction value, while ACCESSCORP and ZENITHBANK followed in volume contribution. ARADEL, ETRANZACT, MEYER, CHAMPION and CAVERTON were among the major stocks weighing on the market. On the gainers’ chart, MCNICHOLS and CMFC topped the table with 10.00% appreciation each, followed by CHELLARAM (+9.79%), LIVINGTRUST (+9.77%) and LEGENDINT (+9.68%). Conversely, ARADEL led the losers with a 10.00% decline, followed by TRANSEXPR (-9.26%), MEYER (-8.86%), CHAMPION (-8.85%) and CAVERTON (-8.70%).