
Quarter Under Preview: -THIRD QUARTER 2026
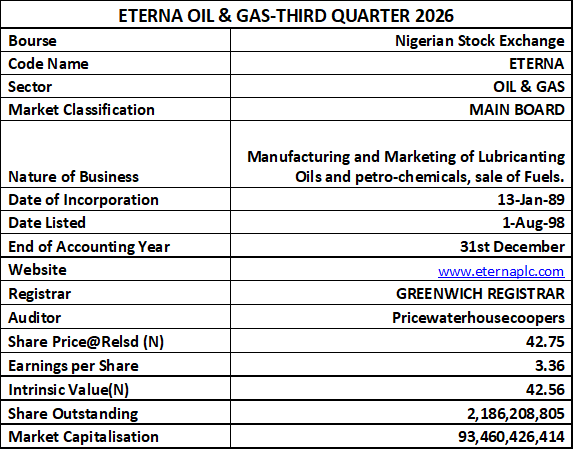
Current Share Price: N42.75
Latest Final Dividend: N0.50
Latest Interim Dividend: N
Estimated Beta Value: 0.54x
Estimated Intrinsic Value: N42.56
Ratings: Buy
Analyst: Jeariogbe Tunde Segun
The Company
Eterna Plc was incorporated on January 13, 1989, as Eterna Oil & Gas Limited and commenced business operations in 1991. The company initially focused on the marketing and distribution of petroleum products, lubricants and oil-related products. In 1991, it established a technical and commercial partnership with Castrol BP, securing distributorship rights to import and market Castrol products in Nigeria and the ECOWAS sub-region. This strategic partnership laid the foundation for its entry into the lubricants market. The company was subsequently re-registered as a public limited liability company in 1997, and its shares listed on the Nigerian Stock Exchange (now Nigerian Exchange Limited) in August of the following year.
Over the years, Eterna expanded its operations and strengthened its position in Nigeria’s downstream petroleum industry. A major milestone was the establishment of its Castrol-certified lubricant blending plant at Sagamu, Ogun State, with an initial capacity of 35,000 metric tonnes, making it one of the pioneering facilities of its kind in sub-Saharan Africa. The company also expanded into petroleum storage and distribution through investments in tank farms, aviation fuel facilities and retail filling stations. Its product portfolio grew to include lubricants, industrial chemicals, aviation fuel, automotive fuels, gas and other petroleum products.
Eterna experienced financial and operational challenges in the early 2000s following unsuccessful acquisition efforts, which affected its financial position and revenue-generating assets. However, a strategic investment in 2004 paved the way for a management restructuring and business turnaround which began in 2005.
The company subsequently embarked on a renewed growth strategy, including rebranding in 2007 and further expansion of its storage and distribution infrastructure. In 2021, Preline Limited acquired a controlling 61% stake in Eterna Plc, marking another significant ownership transition.
Today, Eterna operates as an integrated energy and petroleum products company, with interests in lubricant manufacturing, petroleum products marketing, crude oil trading and distribution, and remains listed on the Nigerian Exchange.
Statement of Comprehensive Income
Eterna Plc recorded a strong improvement in revenue performance in nine months of 2026, according to figures presented through the NGX, with turnover rising by 71.75% to ₦365.56 billion, compared with ₦212.84 billion in the corresponding period of 2025. Cost of sales increased by 68.66% to ₦342.23 billion, growing at a slower rate than revenue, which resulted in improved gross profit. Operating profit also expanded significantly by 250.52% to ₦11.19 billion from ₦3.19 billion, indicating improved operating efficiency and better cost absorption, notwithstanding the 66.75% increase in operating expenses to ₦12.29 billion.
On the financing front, the company recorded a slight 1.67% reduction in finance costs to ₦1.93 billion from ₦1.96 billion. Net finance expense also improved by 49.17%, declining from ₦1.80 billion to ₦912.88 million, providing additional support for earnings growth. Consequently, profit before tax surged by 635.80% to ₦10.28 billion, compared with ₦1.40 billion in Q3 2025. However, depreciation and amortization increased by 10.67% and 73.16%, respectively, reflecting higher non-cash charges against earnings.
After accounting for tax expenses of ₦2.94 billion, representing an increase of 174.16%, Eterna reported a profit after tax of ₦7.34 billion, compared with ₦325.88 million in the corresponding period of 2025, representing an impressive 2,152.91% growth. Overall, the results reflect a substantial improvement in revenue generation, operating profitability and bottom-line performance. The significant earnings recovery is encouraging for shareholders, although attention should be given to the relatively thin operating margin, rising operating expenses and the sustainability of the improved profitability in subsequent reporting periods.
Statement of Financial Position
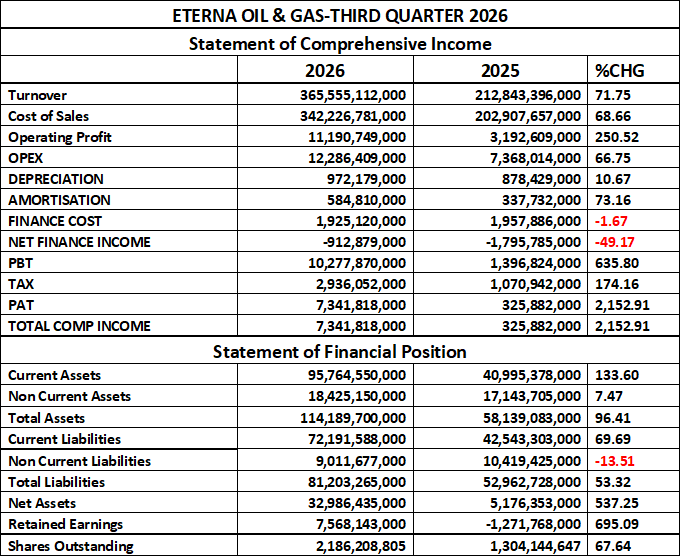
Eterna Plc recorded a significant expansion in its asset base as at Q3 2026, with total assets increasing by 96.41% to ₦114.19 billion, compared with ₦58.14 billion in the corresponding period of 2025. This growth was largely driven by a 133.60% increase in current assets to ₦95.76 billion, while non-current assets rose moderately by 7.47% to ₦18.43 billion. The substantial increase in current assets suggests improved short-term asset capacity and a significant expansion in the company’s operating activities.
On the liabilities side, current liabilities increased by 69.69% to ₦72.19 billion from ₦42.54 billion, while non-current liabilities declined by 13.51% to ₦9.01 billion. Consequently, total liabilities rose by 53.32% to ₦81.20 billion. Despite the increase in obligations, the company’s current assets now exceed current liabilities, producing positive working capital of approximately ₦23.57 billion, compared with negative working capital of ₦1.55 billion in 2025. This represents a notable improvement in short-term liquidity, although the growth in current liabilities remains an area requiring monitoring.
Net assets improved substantially by 537.25% to ₦32.99 billion from ₦5.18 billion, reflecting a significant strengthening of shareholders’ equity. Retained earnings also recovered from a deficit of ₦1.27 billion in 2025 to a positive ₦7.57 billion, representing a major improvement in accumulated profitability. However, shares outstanding increased by 67.64% to 2.19 billion units from 1.30 billion units, indicating a substantial expansion in the company’s share capital. Overall, Eterna’s balance sheet reflects improved liquidity, stronger net asset value and a return to positive retained earnings, although the increase in liabilities and share dilution should be considered when assessing its financial strength and per-share value.
Financial Strength/Solvency Ratio
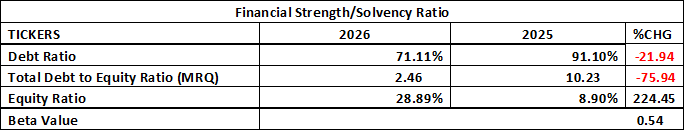
Eterna Plc’s financial strength and solvency position improved considerably in Q3 2026, with the debt ratio declining by 21.94% to 71.11% from 91.10% in 2025, indicating a reduced proportion of assets financed by liabilities. Similarly, the total debt-to-equity ratio dropped significantly by 75.94% to 2.46 from 10.23, while the equity ratio increased by 224.45% to 28.89% from 8.90%, reflecting a substantial improvement in shareholders’ equity relative to total assets. These movements suggest reduced financial leverage and a stronger capital structure, although the debt-to-equity ratio of 2.46 still indicates that debt obligations remain considerably higher than shareholders’ equity. The beta value of 0.54 suggests relatively low systematic volatility compared with the broader market, indicating that the stock has historically exhibited lower sensitivity to general market movements. Overall, Eterna’s solvency indicators point to a significant improvement in financial stability, although its relatively high debt exposure remains an important consideration.
Profitability Ratios
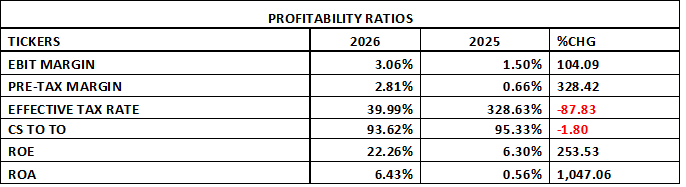
Eterna Plc recorded a significant improvement in its profitability ratios in Q3 2026 compared with the corresponding period of 2025. EBIT margin more than doubled to 3.06% from 1.50%, representing a 104.09% improvement, while pre-tax margin increased to 2.81% from 0.66%, reflecting a 328.42% growth. The cost of sales to turnover ratio (CS to TO) improved marginally to 93.62% from 95.33%, indicating a slight improvement in the company’s cost efficiency. The effective tax rate also declined substantially to 39.99% from 328.63%, although the previous year’s exceptionally high rate was influenced by its relatively low profit before tax.
Return on Equity (ROE) improved significantly to 22.26% from 6.30%, representing a 253.53% increase, while Return on Assets (ROA) rose sharply to 6.43% from 0.56%, indicating improved returns generated from both shareholders’ funds and the company’s asset base. These improvements reflect stronger earnings capacity and better utilization of capital and assets. However, the EBIT margin of 3.06% remains relatively thin, suggesting that the company still operates with limited operating profitability relative to its revenue. Overall, Eterna’s profitability profile shows a substantial recovery, with stronger returns to shareholders and improved asset efficiency.
Efficiency Ratios
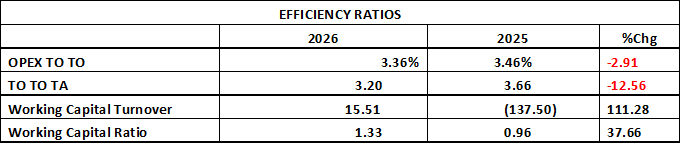
Eterna Plc recorded a mixed but generally improved efficiency performance in Q3 2026. Operating expenses to turnover ratio declined marginally to 3.36% from 3.46%, indicating a slight improvement in operating cost efficiency, while turnover to total assets ratio reduced to 3.20 from 3.66, suggesting a decline in asset utilization efficiency. However, working capital turnover improved significantly from a negative 137.50 times to 15.51 times, reflecting a major recovery in the company’s ability to generate revenue from working capital.
Similarly, the working capital ratio increased to 1.33 from 0.96, moving above the 1.0 benchmark and indicating an improved short-term liquidity position, with current assets now exceeding current liabilities. Overall, Eterna’s working capital management and operating cost efficiency improved, although the decline in asset turnover suggests that the company needs to improve its revenue-generating capacity relative to its expanding asset base.
Investment/Valuation Ratios
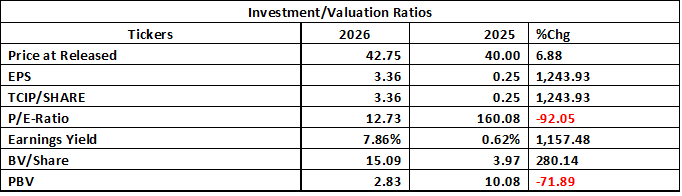
Eterna Plc’s investment and valuation ratios reflect a significant improvement in earnings performance and a more attractive valuation position in Q3 2026. Earnings per share (EPS) increased substantially to ₦3.36 from ₦0.25, representing a growth of 1,243.93%, while total comprehensive income per share (TCIP/share) also improved to ₦3.36 from ₦0.25. At a share price of ₦42.75, representing a 6.88% increase from ₦40.00, the company’s price-to-earnings (P/E) ratio declined significantly to 12.73 times from 160.08 times, indicating that the stock is now trading at a considerably lower earnings multiple. Similarly, earnings yield improved to 7.86% from 0.62%, suggesting better earnings returns relative to the prevailing market price.
Book value per share also strengthened considerably to ₦15.09 from ₦3.97, representing a 280.14% improvement, reflecting the recovery in shareholders’ funds and retained earnings. However, the price-to-book value (PBV) ratio declined to 2.83 times from 10.08 times, indicating a substantial improvement in valuation relative to the company’s net asset position. Overall, Eterna’s valuation profile has improved significantly, supported by stronger earnings, higher book value per share and a lower P/E multiple. Nevertheless, the share price of ₦42.75 remains approximately 2.83 times its book value, suggesting that the market is already pricing in some expectations of continued earnings recovery.
Final Recommendation
Eterna Plc has demonstrated an impressive earnings recovery, significant improvement in shareholders’ funds and better liquidity. Its improved EPS, ROE and declining P/E ratio are positive investment indicators. However, the current market price of ₦42.75 is approximately in line with the estimated intrinsic value of ₦42.56, leaving very limited margin of safety.
Investment conclusion: Eterna is fundamentally improving, but the share price appears to have largely reflected the earnings recovery. A HOLD recommendation is appropriate at the current price. A more attractive entry point would be around ₦34–₦36, providing a better margin of safety.