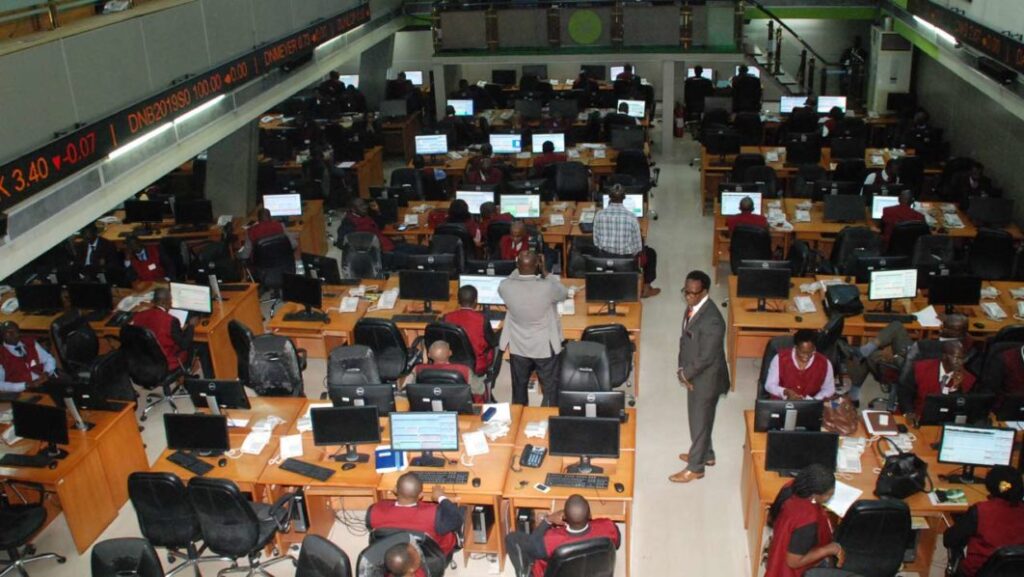
Market Update For November 12, 2026
The Nigerian equities market regained positive momentum on Thursday, November 12, 2026, reversing two consecutive sessions of losses as renewed buying interest in selected heavyweight and mid-cap stocks supported a modest recovery. The rebound reflected improved investor appetite for fundamentally attractive stocks following recent profit-taking, although cautious trading in some sectors continued to limit the market’s overall performance.
The recovery was driven by demand across healthcare, financial services, banking and energy stocks, with FIDSON, SEPLAT, STANBIC, FIRSTHOLDCO, OANDO, UBA and ZENITHBANK among the equities supporting the benchmark index. Their performance helped counterbalance losses in selected consumer goods and real estate stocks, suggesting that investors were repositioning towards counters offering potential value after the recent market correction.
The positive close also indicates that investors are gradually returning to selected equities despite lingering uncertainty over market direction. However, the relatively moderate appreciation suggests that confidence remains selective rather than broad-based, with market participants still weighing opportunities for bargain hunting against the possibility of further profit-taking.
Trading Activity and Sectoral Positioning
Trading activity recorded a significant improvement during the session, reflecting increased participation and renewed interest in selected counters. Total volume traded advanced by 596.70% to 2.91 billion shares, valued at ₦78.66 billion across 28,318 deals.
LIVESTOCK dominated the volume chart, exchanging 2.20 billion shares, representing 75.47% of total market volume. Its substantial contribution indicates concentrated trading interest in the counter and played a major role in the sharp increase in overall market activity.
On the value side, FIRSTHOLDCO led transactions with shares worth ₦32.40 billion, accounting for 41.19% of the day’s total traded value. The strong activity in FIRSTHOLDCO highlights its continued importance in market turnover, while the participation of other actively traded stocks points to sustained institutional and retail interest in selected equities.
The increase in turnover is an encouraging development for market liquidity, particularly following the recent bearish sessions. Nevertheless, the concentration of trading volume in a few stocks suggests that the improvement in activity has not necessarily translated into widespread buying across the market. Sustained participation across different sectors will be important in determining the strength and durability of the recovery.
The return of positive breadth indicates an improvement in underlying market sentiment, with advancing stocks outnumbering decliners. However, the continued weakness in some consumer goods and real estate counters shows that investors remain selective in their positioning.
International Breweries’ decline to a new 52-week low of ₦8.40 is particularly noteworthy, as it reflects persistent selling pressure and weak sentiment surrounding the stock. Such price movements reinforce the importance of company-specific fundamentals, earnings performance, operating costs and sector conditions in determining individual stock performance.
For investors, the current market environment presents opportunities to accumulate fundamentally sound equities at relatively attractive prices, although caution remains necessary. Stocks with strong earnings potential, sustainable dividend prospects, healthy balance sheets and improving operational performance may continue to attract attention as investors reposition their portfolios.
Oil Market:
International crude oil prices edged higher on Thursday as persistent geopolitical tensions in the Middle East and Russia provided support, offsetting concerns over rising crude production and the possibility of increased global supply.
Brent crude futures gained 65 cents to $93.40 per barrel, while US West Texas Intermediate (WTI) crude rose marginally by one cent to $86.54 per barrel at 1425 GMT. The recovery followed earlier losses of more than $1 per barrel in early Asian trading.
Technical Analysis and Market Outlook
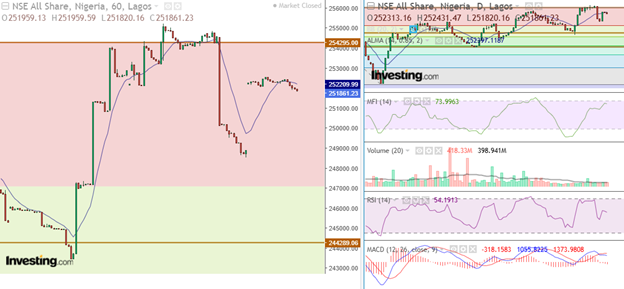
From a technical perspective, the Nigerian equities market’s return to positive territory suggests an attempt to establish support following the recent downward movement. The recovery in the All-Share Index indicates that buyers are gradually returning to selected counters, although the market still requires stronger participation from heavyweight stocks to confirm a sustained bullish reversal.
The 253,000-point region remains an immediate resistance area to watch, as a decisive break above this level could strengthen bullish momentum and open the door for further upward movement. On the downside, the previous session’s closing level around 251,861 points provides an important near-term support reference. A failure to sustain the recovery could expose the market to renewed selling pressure and further consolidation.
Market breadth will also remain an important indicator of the strength of any recovery. Continued positive breadth, accompanied by stronger turnover in fundamentally sound large-cap stocks, would provide better confirmation of improving market sentiment. Conversely, a rally driven by only a handful of heavily traded counters may struggle to maintain momentum.
In the coming sessions, investors are expected to monitor corporate earnings, dividend expectations, macroeconomic developments, interest rate conditions and foreign portfolio flows for further direction. The interplay between these factors will influence investment decisions, particularly as market participants balance opportunities in equities against competing returns from fixed-income instruments.
Overall, the market’s recovery provides an encouraging signal following two consecutive sessions of losses, but it is too early to conclude that a sustained bullish trend has been established. Selective bargain hunting, improved liquidity and renewed demand for fundamentally strong stocks could support further gains, while profit-taking and cautious investor positioning may keep the market volatile.
The Nigerian Exchange All-Share Index (ASI) advanced by 0.20% to close at 252,366.80 points from 251,861.24 points in the previous session, adding approximately ₦328.26 billion to market capitalisation, which settled at ₦163.86 trillion. The market’s year-to-date return improved to 62.18%, while trading volume increased by 596.70% to 2.91 billion shares, valued at ₦78.66 billion across 28,318 deals. Market breadth was positive, with 26 gainers against 21 losers. Major market movers included FIDSON, SEPLAT, STANBIC, FIRSTHOLDCO, OANDO, UBA and ZENITHBANK. FIDSON (+9.94%), SUNUASSUR (+9.92%), CHAMPION (+9.85%), CAVERTON (+9.59%) and FTGINSURE (+9.42%) led the gainers, while INTBREW (-7.18%), TANTALIZER (-6.67%), HONYFLOUR (-4.85%), VITAFOAM (-4.66%) and UPDCREIT (-3.74%) recorded the biggest losses.