
Market Update For November 19, 2026
The Nigerian equities market sustained its bearish momentum on Thursday, November 19, 2026, as continued profit-taking in selected blue-chip and mid-cap stocks outweighed gains in other counters, keeping the benchmark index under pressure. The modest decline reflected cautious investor positioning and portfolio adjustments following the market’s recent rally, despite pockets of bargain hunting across selected equities.
The NGX All-Share Index (ASI) shed 0.02% to close at 248,286.56 points, compared with 248,329.65 points recorded in the previous trading session. The decline translated into an estimated loss of ₦27.98 billion in market capitalisation, while the market’s year-to-date (YTD) return moderated to 59.55%. Although the decline was relatively marginal, the continued weakness suggests that investors are becoming more selective, particularly in stocks that have recorded significant price appreciation.
Selling pressure remained concentrated in selected equities, with INTBREW declining by 4.50%, followed by OANDO (-4.17%), UBA (-3.38%), TRANSCORP (-3.13%), FCMB (-1.36%), TIP (-1.18%), NGXGROUP (-1.14%), ACCESSCORP (-0.92%) and NEM (-0.71%). The performance of these stocks reflected renewed profit-taking and cautious repositioning, as investors reassessed their exposure to equities amid mixed market signals.
The financial services sector and other actively traded counters continued to influence market direction, with investors maintaining interest in selected stocks despite the broader weakness. However, the absence of stronger buying support in some heavyweight equities limited the market’s ability to reverse its downward movement.
Trading activity also moderated, indicating a slowdown in market participation. Total volume declined by 17.54% to 372.03 million shares, compared with the previous session, while transaction value stood at ₦14.37 billion across 28,467 deals. The reduction in volume suggests that some investors remained on the sidelines, awaiting more attractive entry points and clearer directional signals.
TRANSEXPR emerged as the most actively traded stock by volume, exchanging 30.25 million shares, equivalent to 8.13% of total market volume. CHAMS followed with an 8.06% contribution, while FIDELITYBK accounted for 5.40%. On the value side, GTCO dominated transactions with ₦2.09 billion, representing 14.57% of total market value. ARADEL and ZENITHBANK also featured among the leading contributors, highlighting sustained investor activity in selected large-cap counters.
Technical Analysis and Market Outlook
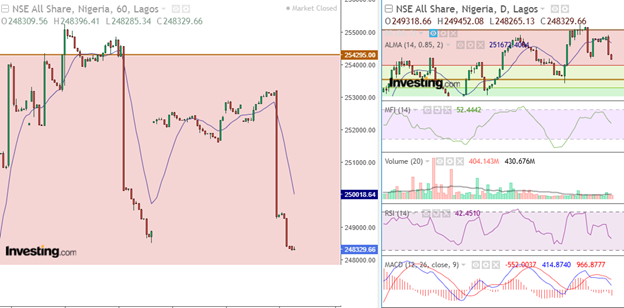
From a technical standpoint, the ASI’s continued weakness points to a market struggling to establish a fresh upward direction after its recent gains. The index is trading below the psychological 250,000-point threshold, which remains an important resistance level and a key barrier to renewed bullish momentum.
The 248,000-point region represents an immediate support area to watch, as sustained demand around this level could help prevent further declines and encourage a gradual recovery. A successful rebound towards 250,000 points would strengthen the market’s near-term outlook, although a decisive break above that level would be necessary to confirm a stronger bullish recovery.
Conversely, persistent selling pressure and a failure to hold the 248,000-point support zone could expose the market to additional downside, particularly if institutional investors continue to lock in profits. The current market structure therefore calls for caution, as the balance between bargain hunting and profit-taking is likely to determine the index’s next direction.
For the next trading session, we anticipate mixed sentiment, with selective buying interest expected in fundamentally sound stocks and counters trading at attractive valuations. However, continued profit-taking in recently appreciated equities could limit market recovery. Investors should focus on corporate earnings, dividend prospects, liquidity and valuation rather than short-term price movements.
Oil Market
International oil prices moved higher on Thursday as renewed geopolitical tensions in the Middle East raised concerns about possible supply disruptions, providing support to crude prices despite expectations of a global supply surplus.
Brent crude advanced by 1.35% to $93.19 per barrel, while US West Texas Intermediate (WTI) gained 1.60% to $84.55 per barrel. The gains reflected the market’s sensitivity to geopolitical developments and the potential implications for global energy supply.
Market Summary and Performance: The NGX All-Share Index declined by 0.02% to 248,286.56 points, compared with 248,329.65 points in the previous session, while market capitalisation shed approximately ₦27.98 billion. Trading activity weakened as total volume fell by 17.54% to 372.03 million shares, valued at ₦14.37 billion across 28,467 deals. The market’s year-to-date return moderated to 59.55%, while market breadth closed negative with 19 gainers against 26 decliners, indicating that declining stocks outnumbered advancing equities. TRANSEXPR led trading volume with 30.25 million shares, representing 8.13% of total transactions, followed by CHAMS at 8.06% and FIDELITYBK at 5.40%. GTCO dominated traded value with ₦2.09 billion, accounting for 14.57% of total turnover, while ARADEL and ZENITHBANK also featured among the leading value contributors. On the gainers’ chart, SOVRENINS advanced 9.96% to ₦2.76, CMFC gained 9.94% to ₦3.87, CHELLARAM rose 9.86% to ₦11.70, CORNERST appreciated 9.64% to ₦4.55, and REGALINS added 8.45% to ₦0.77. Conversely, ROYALEX declined 6.00% to ₦0.94, MCNICHOLS lost 5.05% to ₦4.70, INTBREW fell 4.50% to ₦9.55, VERITASKAP shed 4.42% to ₦1.08, while OANDO dropped 4.17% to ₦34.50 each.