Market Update For September 17, 2026
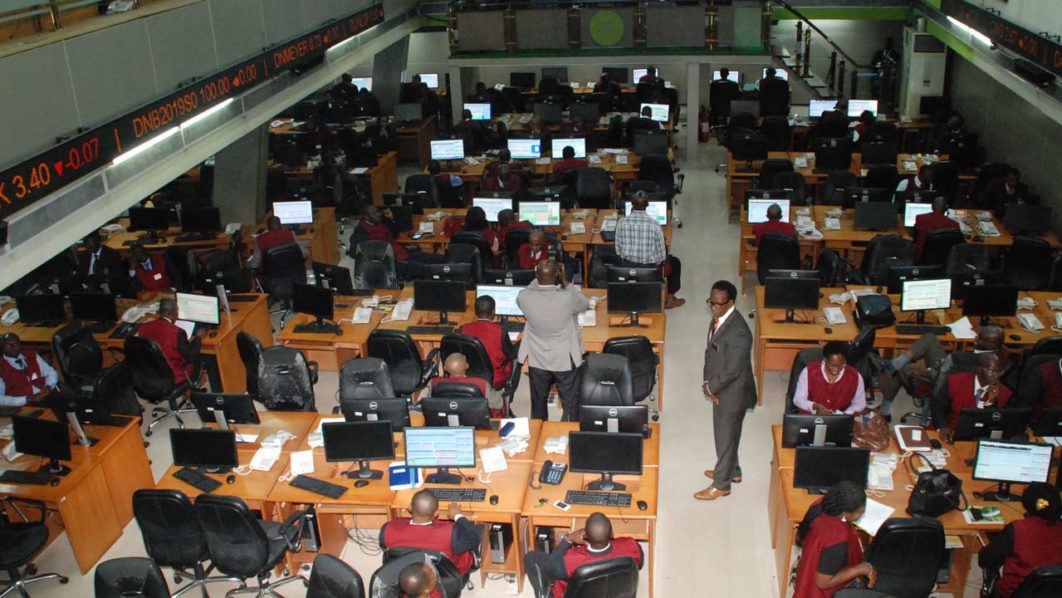
The Nigerian equities market extended its recovery on Thursday, September 17, as renewed buying interest across selected counters pushed the benchmark higher Market Update For September 17, 2026 keeping the market in positive territory.
The session reflected a gradual improvement in investors’ demand, with buying interest spread across industrial, banking, consumer and real estate-related stocks. While gains were not broad-based across all sectors, the performance of several actively traded equities helped sustain the upward movement in the benchmark.
Investors continued to show interest in selected stocks with strong price momentum, while some counters faced significant selling pressure. The divergence in individual stock performances highlights the increasingly selective approach being adopted by market participants as they assess valuations, corporate prospects and short-term trading opportunities.
One of the notable developments was the performance of UPDCREIT, which gained 10%, closing at ₦17.60 each and moved above its 52-week high. The move places the real estate investment trust among the stocks attracting strong buying interest and brings increased attention to its ability to sustain the recent price momentum.
BUACEMENT advanced by the same margin, while ROYALEX gained 9.89%, adding to the strong performance recorded among the leading gainers.
On the other hand, selling pressure was pronounced in TRANSPOWER, which declined 9.97%. LEGENDINT, OMATEK, LIVINGTRUST and SOVRENINS also recorded substantial losses. The sharp movements on both sides of the market indicate that investors remain active in repositioning their portfolios.
Trading activity was another important feature of Thursday’s session. FIDELITYBK continued to dominate activity, recording 524.33 million shares traded. The strong volume in the counter contributed significantly to overall market turnover and highlighted continued investor participation in banking stocks.
ZENITHBANK and GTCO also featured prominently in value traded, reflecting sustained interest in some of the market’s major financial institutions. The concentration of trading in a few actively traded stocks, however, suggests that liquidity remains uneven across the broader market.
The improvement in market activity came as the NGX continued to recover from the weakness recorded earlier in the month. Investors are now watching whether the recent rebound can develop into a more sustained upward move or whether profit-taking will emerge around key technical levels.
Technical Analysis
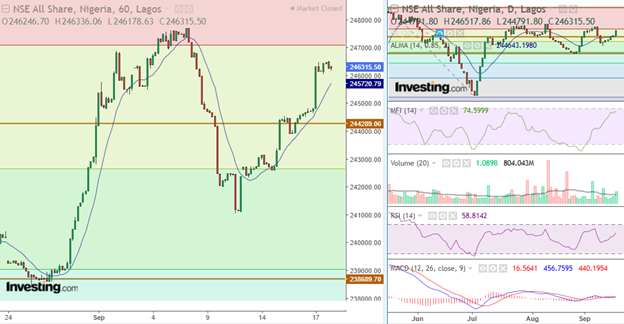
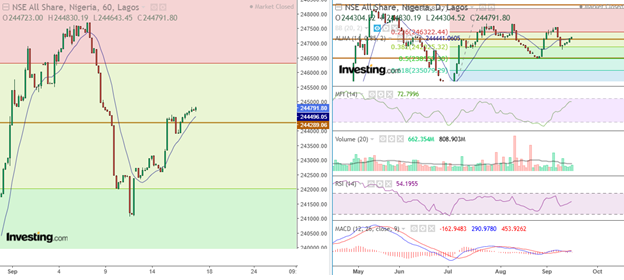
From a technical standpoint, the All-Share Index maintained its short-term recovery after gaining another 0.62% during Thursday’s session.
The index closed at 246,315.38 points, keeping it above the 245,000-point psychological level. This is an important development for the short-term structure of the market, particularly after the recent decline that pushed the ASI towards the 242,000-point region.
The 242,000-point area remains an important support zone. A sustained hold above this level could provide a base for further recovery, while a renewed break below it would indicate that sellers are regaining control of the market.
On the upside, the 250,000-point region remains a key resistance level. The index will need stronger buying interest and broader participation to convincingly move through this area.
The increase in trading volume during Thursday’s advance provides some confirmation of the renewed demand. However, volume needs to remain elevated over subsequent sessions for the recovery to demonstrate greater strength.
Market breadth is another factor to monitor. Although the session closed with more gainers than decliners, participation was not overwhelmingly broad. A continued improvement in the number of advancing stocks would provide stronger support for the market’s recovery.
The performance of leading banking and industrial stocks will also remain important. These stocks carry significant weight and liquidity in the market, meaning sustained buying interest in them can have a meaningful influence on the direction of the broader index.
Meanwhile, stocks that have moved sharply towards or above their 52-week highs could experience increased volatility as existing investors consider taking profits and new buyers assess whether current prices can be sustained.
Outlook
The market enters the next trading session with its short-term recovery intact, although investors are likely to remain cautious as the ASI approaches the 250,000-point resistance area.
Sustained buying across large-cap stocks could provide the momentum needed for the index to test higher levels. However, if buying interest becomes concentrated in only a handful of stocks, the broader market could struggle to maintain the pace of the recovery.
The performance of market breadth will therefore remain important. Continued gains accompanied by a healthy number of advancing stocks would indicate stronger participation, while a decline in breadth despite a rising index could point to a more selective market.
Investors will also continue to monitor corporate developments, earnings expectations, monetary policy, interest rates and liquidity conditions. These factors could influence the flow of funds between equities, fixed-income instruments and other investment assets.
The banking sector is likely to remain a major area of attention given the level of trading activity recorded in financial stocks. At the same time, renewed interest in industrial and real estate-related counters could provide additional support if the trend continues.
For the broader market, the immediate focus remains on whether the ASI can consolidate above 245,000 points and eventually challenge the 250,000-point resistance. The reaction of investors around these levels could provide a clearer indication of the next phase of the market.
Oil Market
The international oil market remained under pressure on Thursday, with crude prices extending the previous session’s losses as concerns about immediate supply disruptions eased.
Brent crude fell about 3% to $102.72 per barrel, while US West Texas Intermediate declined 1.91% to $100.47 per barrel. Brent touched its lowest level since September 10, while WTI fell to its lowest level since September 11.
The decline followed reports that Saudi Arabia was offering additional crude cargoes through Oman, helping to ease concerns about the availability of Middle Eastern supplies.
Expectations that Saudi Arabia’s East-West pipeline could return to service sooner also contributed to the decline in prices. The developments reduced some of the immediate supply concerns that had pushed crude prices higher in previous sessions.
Despite the decline, both benchmarks remained above $100 per barrel as investors continued to assess the potential impact of the Middle East conflict on global energy supplies.
For Nigeria, movements in international crude prices remain significant because oil continues to play an important role in government revenues, foreign-exchange earnings and external liquidity.
Higher oil prices can provide support for government revenues and foreign-exchange inflows, while a sustained decline could place greater pressure on fiscal and external positions. The relationship between crude prices and Nigerian equities, however, can vary depending on domestic monetary conditions, exchange-rate developments, corporate earnings and investor sentiment.
The oil market will therefore remain an important external factor for Nigerian investors, particularly as the equities market approaches a key technical resistance level.
The Nigerian Exchange All-Share Index gained 1,523.59 points, or 0.62%, to close at 246,315.38 points, while market capitalisation increased by ₦1.18 trillion to ₦159.89 trillion. The market’s year-to-date return rose to 58.29%. Total transactions reached 1.09 billion shares valued at ₦43.38 billion in 54,026 deals, while market breadth remained positive with 37 gainers, 27 decliners and 83 unchanged stocks. FIDELITYBK led market activity with 524.33 million shares traded, followed by strong activity in other major financial stocks. Top gainers: BETAGLAS +10.00% to ₦511.50; CONHALLPLC +10.00% to ₦7.37; UPDCREIT +10.00% to ₦17.60; BUACEMENT +10.00% to ₦297.00; ROYALEX +9.89% to ₦1.00. Top losers: TRANSPOWER -9.97% to ₦197.70; LEGENDINT -9.88% to ₦3.65; OMATEK -9.66% to ₦1.31; LIVINGTRUST -8.45% to ₦2.60; SOVRENINS -7.91% to ₦1.98 each.