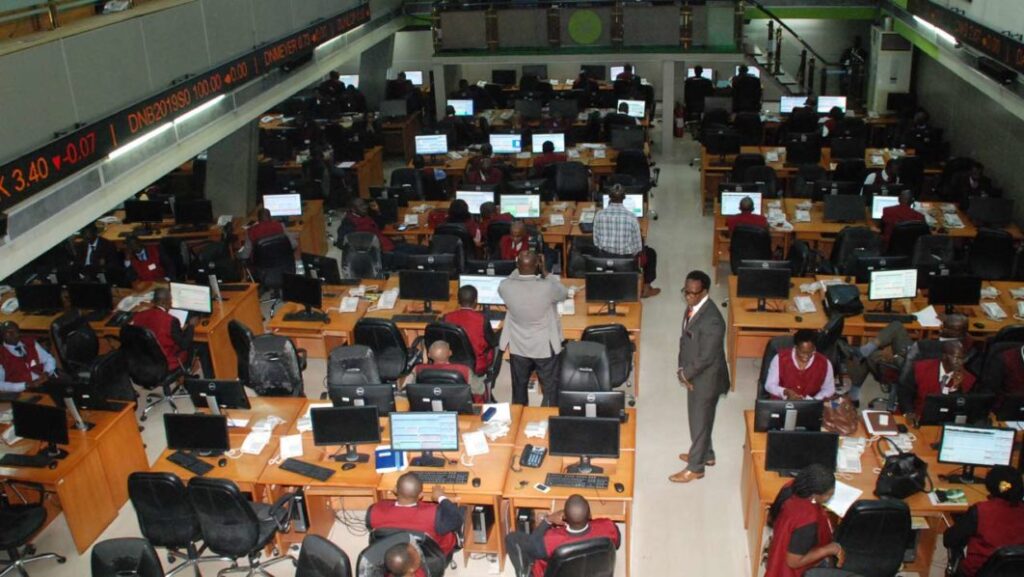
Market Update For October 27, 2026
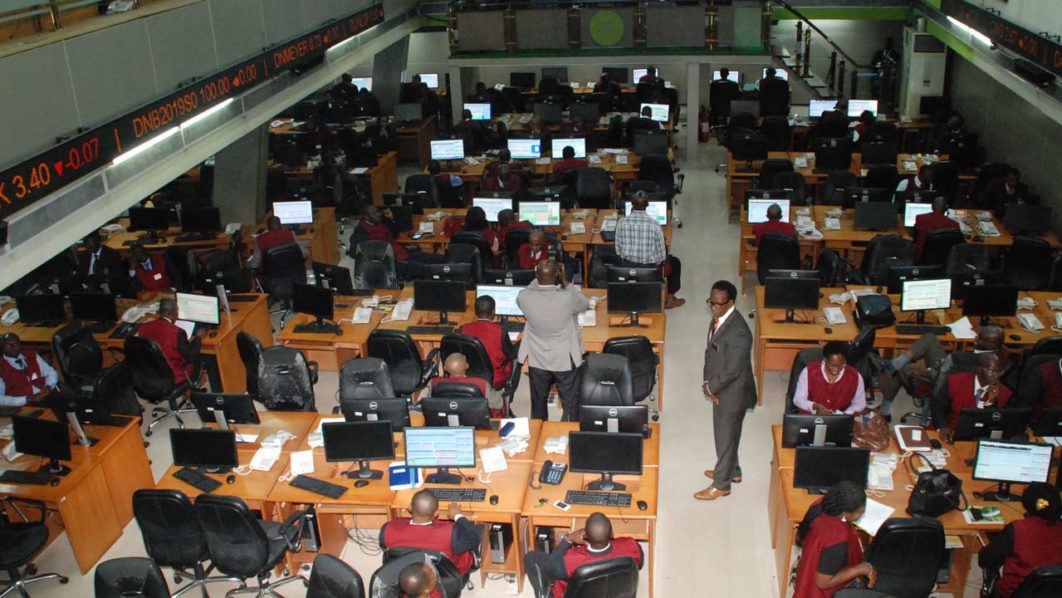
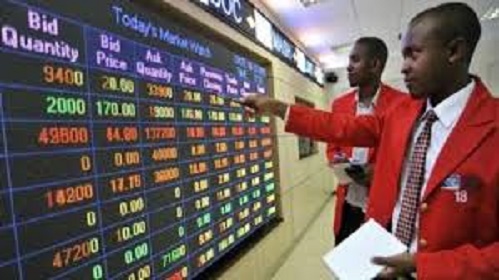
Nigeria’s equities market extended its bull-run on Tuesday, October 27, 2026, on renewed demand for heavyweight stocks which pushed the benchmark NGX All-Share index higher for a second consecutive session. Gains in Dangote Cement and selected financial services and industrial stocks supported the rally, although persistent losses across several listed companies indicated that investor sentiment remained divided.
The latest advance reflects continued buying interests in selected large-cap equities as investors position for potential gains amid changing domestic economic conditions and developments in global financial markets.
However, the divergence between the benchmark index and broader market performance suggests that the rally has yet to translate into widespread participation across the Nigerian Exchange.
At the close of trading, the NGX All-Share Index (ASI) advanced by 2,699.52 basis points, or 1.07%, closing at 253,990.06 points, compared with 251,290.54 points recorded on Monday. The gain followed the previous session’s strong performance, reinforcing the market’s upward momentum and extending its recovery towards the 254,000-point region.
Market capitalisation increased by ₦1.75 trillion to ₦164.91 trillion, reflecting the positive contribution of advancing equities to the overall market valuation. The market’s year-to-date return also improved to 63.22%, underscoring the substantial gains recorded by Nigerian equities since the beginning of the year.
Despite the strong performance, the market’s advance was largely supported by selected heavyweight stocks rather than a broad-based improvement in investor sentiment. This distinction remains important because sustained market rallies generally benefit from participation across multiple sectors, rather than depending heavily on a limited number of influential companies.
Dangote Cement emerged as one of the principal drivers of Tuesday’s rally, gaining 9.80% to close at ₦1,341.90 each and recording a new 52-week high. The stock’s advance strengthened the industrial sector’s contribution to the benchmark index and highlighted the influence of large-cap equities on overall market performance.
The performance of Dangote Cement is particularly significant given the company’s size and its position within the domestic industrial sector. Strong price movements in large-cap stocks can have a considerable effect on the direction of the ASI, especially when investors concentrate their purchases on companies with substantial market valuations.
Honeywell Flour Mills also recorded a strong performance, rising 9.67% to ₦21.55, while NAHCO gained 8.00% to close at ₦151.20. AVACAP advanced by 9.42% to ₦7.55, reflecting additional buying interest in selected stocks outside the market’s largest industrial names.
Within the financial services sector, Wema Bank advanced by 4.01%, Access Corporation gained 3.26%, and Stanbic IBTC Holdings rose by 3.06%. Their gains provided additional support for the market, suggesting that investors were still willing to take positions in selected banking and financial services stocks.
The positive performance across these equities indicates that demand was not confined entirely to one sector. Nevertheless, the market’s negative breadth shows that the gains were insufficient to offset selling pressure across a substantial number of listed companies.
For investors, the performance of heavyweight stocks remains an important factor in determining the sustainability of the current rally. Continued strength in companies such as Dangote Cement and selected banking stocks could provide further support for the benchmark index. However, a broader improvement in participation would offer stronger evidence that the market’s upward movement is becoming more firmly established.
Despite the benchmark’s advance, market breadth remained negative, with 22 stocks closing higher against 39 decliners, while 85 equities ended the session unchanged.
The imbalance between advancing and declining stocks suggests that selling pressure remained widespread, even as the market recorded a substantial increase in its overall valuation. This pattern highlights the difference between index performance and the experience of investors holding individual stocks.
A market can record strong gains when a few heavily weighted companies appreciate significantly, even if a larger number of smaller or less influential stocks decline. In such circumstances, the benchmark may give a more positive impression of market conditions than the performance of the average listed company.
Tuesday’s session reflected this dynamic. While Dangote Cement and several other advancing equities helped lift the ASI, losses among other stocks demonstrated that investors remained selective in their allocation of funds.
Negative breadth does not necessarily mean that the rally will reverse immediately. Instead, it signals that the strength of the advance should be assessed alongside other indicators, including trading activity, sector performance and the ability of leading stocks to sustain their gains.
If the number of advancing stocks begins to increase alongside further index appreciation, it could indicate a broader recovery in investor confidence. Conversely, if the ASI continues to rise while declining stocks consistently outnumber gainers, the market could remain vulnerable to sudden changes in sentiment.
Trading activity was another important feature of Tuesday’s session, although the available market reports contain conflicting turnover figures that require reconciliation before publication.
One report recorded 5.23 billion shares valued at ₦441.44 billion, representing a substantial increase in activity. Within that account, FIRSTHOLDCO reportedly dominated the market, accounting for 4.88 billion shares, or 93.19% of total volume, with transactions valued at ₦416.29 billion, equivalent to 94.30% of total traded value.
However, a separate market summary reported that 376.92 million shares worth ₦28.22 billion changed hands. It also identified Honeywell Flour Mills as the volume leader, with 32.64 million shares traded, while Dangote Cement recorded the highest transaction value.
The difference between these figures is too significant to treat as a minor reporting variation. The correct volume, value and deal count should be confirmed against the official NGX trading report before the figures are incorporated into the final published analysis.
Nevertheless, the available information points to notable activity in selected equities. Where turnover is concentrated in a small number of stocks, investors should distinguish between broad market liquidity and transactions driven by specific securities or exceptional trading events.
FIRSTHOLDCO’s reported dominance in the higher-volume account would, if confirmed, indicate an unusually concentrated session. Such activity may reflect large transactions or changes in investor positioning, but turnover alone does not establish whether institutional investors are accumulating shares or reducing their exposure.
For a more complete assessment, investors should examine the number of shares traded, transaction values, deal counts and the distribution of activity across sectors. These measures help determine whether increased turnover reflects broad participation or isolated transactions in a handful of equities.
Technical Analysis
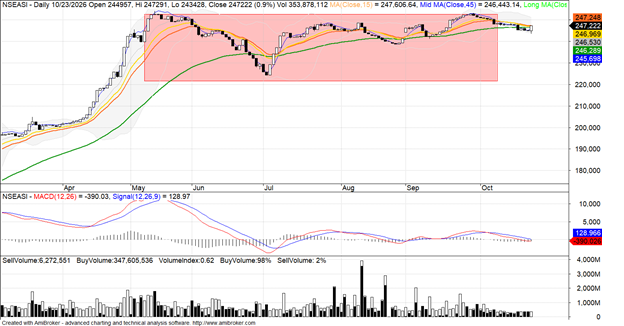
From a technical perspective, the ASI’s 1.07% appreciation strengthens the market’s immediate bullish outlook and keeps the benchmark above the psychologically important 250,000-point level.
The advance from Monday’s close of 251,290.54 points to 253,990.06 points indicates that buyers maintained control of the benchmark’s direction during the session. The market’s proximity to the 254,000-point region also places it at an important level to monitor for signs of continued momentum.
A sustained move above this region could strengthen the bullish outlook and encourage additional buying, particularly if the advance is accompanied by improving market breadth and healthy trading activity. However, a single session’s gain is insufficient to confirm a durable breakout, especially when declining stocks continue to outnumber advancing equities.
The 250,000-point level remains an important psychological reference point. A sustained position above this threshold would help preserve the market’s current positive structure, while a decline below it could expose the benchmark to renewed selling pressure.
Investors should also monitor the behaviour of heavyweight stocks, particularly Dangote Cement, whose latest advance to a new 52-week high contributed to the market’s performance. Continued strength in such stocks could support the ASI, although sharp profit-taking in leading equities may have an outsized impact on the benchmark.
The market’s technical outlook should therefore be assessed through a combination of price movement, trading volume, market breadth and the performance of leading sectors. The current advance is encouraging, but confirmation of a stronger upward trend would require sustained buying interest and broader participation.
Oil Market
Oil prices declined on Tuesday as investors focused on diplomatic engagements surrounding the Middle East conflict. Brent crude futures fell by $1.00, or 0.86%, to $114.81 per barrel, while US West Texas Intermediate crude declined by $0.78, or 0.77%, to $100.98 per barrel.
Despite the pullback, prices remained elevated amid persistent geopolitical risks, including the ongoing Houthi-Saudi Arabia conflict and concerns over the possibility of further US-Israeli attacks. Diplomatic discussions involving Iranian representatives and regional stakeholders also remained in focus as markets assessed the prospects for easing hostilities.
For Nigeria, elevated oil prices can have mixed implications. Higher prices may support export earnings and government revenue, but persistent geopolitical tensions can also increase uncertainty, raise global energy costs and complicate the outlook for inflation and economic growth.
These developments may influence investor expectations for energy companies, exchange-rate stability, government finances and domestic interest-rate conditions. However, the effect on individual Nigerian stocks will depend on company-specific fundamentals and how changes in global prices translate into local operating conditions.
Within the equities market, investors are likely to continue balancing the potential benefits of strong domestic earnings against inflationary pressures, funding costs and uncertainty in the external environment.
Outlook
The Nigerian equities market enters the next trading session with a cautiously bullish outlook. The ASI’s latest advance, the increase in market capitalisation and the strong performance of selected heavyweight stocks point to continued buying interest.
However, the negative market breadth remains a key concern. If gains remain concentrated in a small number of large-cap equities, the market may struggle to sustain its upward trajectory without broader participation.
Investors should monitor whether the ASI can maintain its position above 250,000 points and extend its advance beyond the 254,000-point region. A sustained breakout accompanied by stronger breadth would provide a more convincing signal of market strength.
On the other hand, continued declines across a wider range of stocks could indicate that investors are becoming increasingly selective or taking profits in existing positions. In that environment, the benchmark could remain supported by heavyweight stocks while individual equities experience greater price volatility.
Corporate earnings, trading liquidity, sector-specific developments and external market conditions will remain important determinants of investor positioning. Stocks with strong earnings prospects and resilient fundamentals may continue to attract attention, while investors should avoid relying solely on recent price appreciation when making investment decisions.
Overall, the market’s direction remains positive in the near term, but the durability of the rally will depend on whether buying interest broadens beyond a few influential stocks. Improved market breadth, sustained demand and confirmation of the latest technical advance would strengthen the case for further gains.
Market Summary: The NGX All-Share Index (ASI) advanced by 2,699.52 points, or 1.07%, to close at 253,990.06 points on Tuesday, October 27, 2026, while market capitalisation increased by ₦1.75 trillion to ₦164.91 trillion. The market’s year-to-date performance improved to 63.22%. Trading activity figures remain subject to verification, as the supplied reports recorded either 5.23 billion shares worth ₦441.44 billion or 376.92 million shares valued at ₦28.22 billion. Market breadth was negative, with 22 stocks advancing, 39 declining and 85 closing unchanged. Key market movers included DANGCEM, HONYFLOUR, NAHCO, WEMABANK, ACCESSCORP and STANBIC, with DANGCEM reaching a new 52-week high of ₦1,341.90. Top gainers: UPDCREIT (+10.00% to ₦19.25), DANGCEM (+9.80% to ₦1,341.90), HONYFLOUR (+9.67% to ₦21.55), AVACAP (+9.42% to ₦7.55) and NAHCO (+8.00% to ₦151.20). Top losers: PRESCO (-10.00% to ₦1,840.80), TRIPPLEG (-9.93% to ₦2.54), THOMASWY (-9.85% to ₦2.47), AUSTINLAZ (-9.81% to ₦2.39) and TRANSCORP (-9.70% to ₦32.60).