Dangote Cement Plc is one of Nigeria’s most strategically important industrial giants, with a large domestic manufacturing and distribution network and a presence in selected African markets. Its investment case rests on the continuing demand for cement from housing, commercial construction, roads, infrastructure and urbanisation.
Current price: N1,341.90
Rating: Buy
Price projection: N1,800, N2,000 and N2,200
Technical Analysis
In this report, we shall use the following tools and analysis methods:
Elliott’s wave theory to understand the overall market sentiment
Fibonacci tools to determine support and resistance levels
The Relative Strength Index and volume to evaluate the market’s strength
The Money Flow Index to determine the market liquidity
Moving average and MACD to understand the nature of the trend
Top-down analysis to know the best investment position
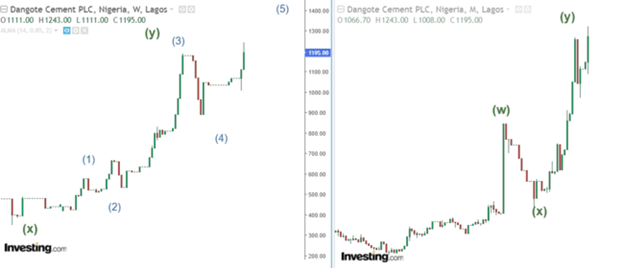
Elliott wave analysis
Weekly chart: Market overview
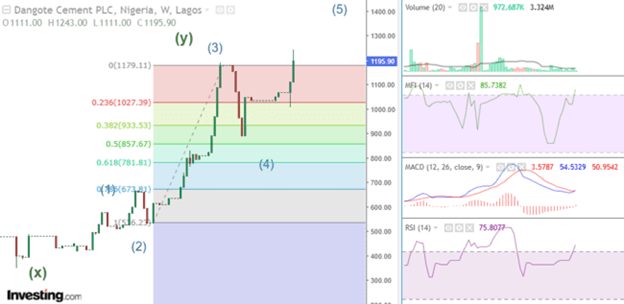
Dangote Cement commenced its recovery phase after meeting strong support within the 0.5 Fibonacci level. This phase broke the stock 52-week at N1,180, creating investment opportunities for investors. In line with this performance, the stock’s liquidity, momentum, and liquidity improved exponentially. MACD also initiated its bullish signal, aligning with this overall market sentiment.
Daily chart: Investment opportunitiy
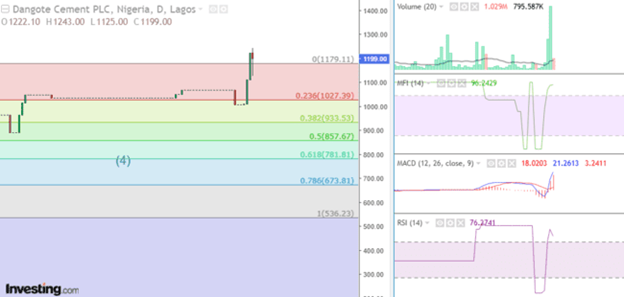
On the daily chart, Dangote Cement pulled back after breaking its all-time high level. This performance offers a buy-in opportunity for discount investors. In line with this performance, volume closed strong bearish above its moving average, signalling profit-taking. However, the stock’s liquidity and relative strength sustained their strong momentum. Thus, investors should should watch N1,125 and N1000 as potential support levels with prices projected at N1,800, N2,000 and N2,200
SWOT Analysis
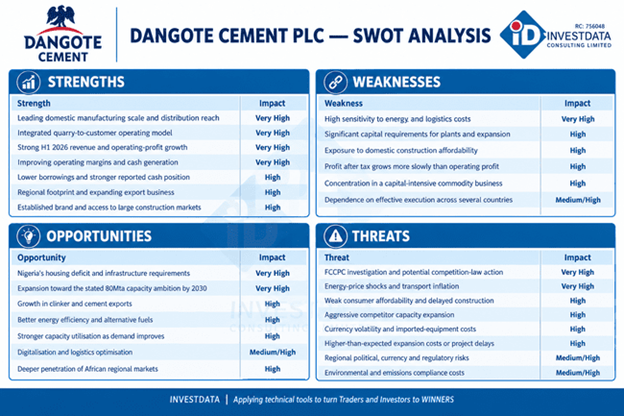
Dangote Cement’s strongest advantages are its scale, integrated operations, improving margins and strong cash generation. Its principal vulnerabilities are energy and logistics costs, construction affordability and the substantial investment required to expand. The FCCPC investigation adds a material regulatory risk to the investment case.
The company’s opportunities lie in infrastructure-led demand, export growth, operational efficiency and disciplined expansion. For shareholders, the decisive question is whether these opportunities can deliver sustainable earnings and cash-flow growth without sacrificing pricing flexibility, balance-sheet resilience or dividend capacity.