Market Update For November 4, 2026
The Nigerian equities market sustained its upward trajectory on Wednesday, November 4, 2026, extending the previous session’s gains as renewed demand for selected heavyweight stocks continued to support the benchmark index. Although buying interests remained evident in major banking and industrial counters, the broader market reflected a mixed trading pattern, with investors maintaining selective positions amid intermittent profit-taking in several equities.
The positive performance highlights the continued resilience of the domestic equities market, which has maintained substantial gains since the beginning of the year. Demand for large-cap stocks remained an important driver of market direction, particularly within the banking sector, where GTCO, UBA, ZENITHBANK and FIDELITYBK attracted renewed investor interest. HONYFLOUR and TRANSPOWER also recorded significant price appreciation, while TRANSCORP, WEMABANK and STERLINGNG contributed to the positive market sentiment.
The banking sector’s influence on the benchmark performance underscores its importance in determining the direction of the Nigerian equities market. With institutional and retail investors continuing to position themselves in highly capitalised stocks, movements in major banking equities are likely to remain a significant determinant of overall market performance. However, the relatively modest increase in the benchmark index suggests that investors are becoming more selective, particularly as some stocks experience profit-taking following previous price appreciation.
The market’s performance also reflects a gradual balance between bargain hunting and portfolio repositioning. While some investors continued to accumulate positions in stocks with attractive growth prospects, others appeared to be locking in gains from equities that have recorded substantial appreciation. This combination of buying and selling activity has contributed to the uneven performance across market segments, with selected heavyweight stocks providing support while several mid- and small-cap counters remained under pressure.
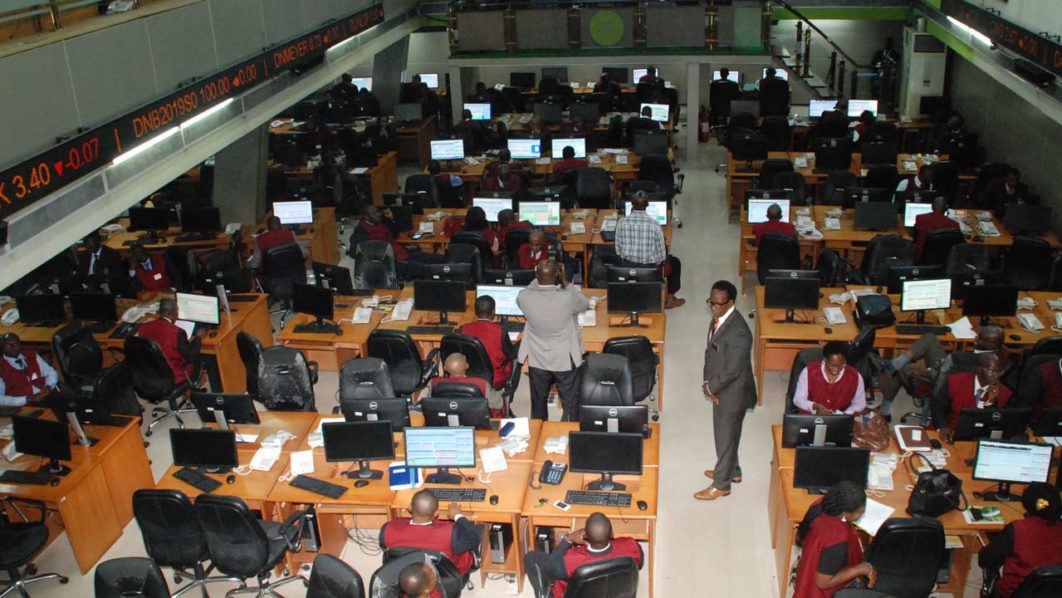
Trading activity remained relatively active, indicating sustained investor participation despite the mixed performance across individual stocks. FIRSTHOLDCO featured prominently in the day’s transactions, recording the highest volume and value contributions in one of the supplied market reports. The stock’s activity reflects its continued importance in the financial services segment and its influence on overall market turnover. ACCESSCORP and GTCO also featured among the actively traded equities, reinforcing the banking sector’s significant contribution to market activity.
Technical Analysis, Market Outlook
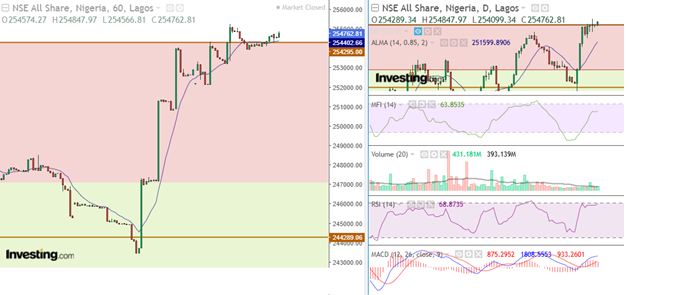
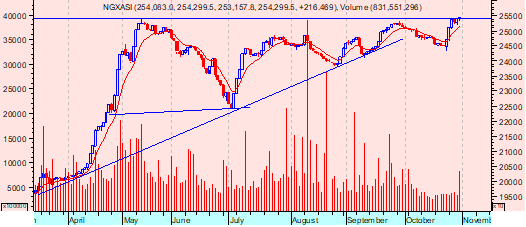
From a technical perspective, the NGX All-Share Index maintained its positive direction, extending its recent advance and approaching the 255,000-point psychological threshold. The latest close at 254,762.81 points indicates that buyers remain active, with the market preserving its short-term bullish bias despite the relatively modest daily appreciation.
The ability of the index to sustain its position above the 253,000-point region is important for maintaining the current upward structure. This level represents an immediate support area, where renewed buying interest could help limit potential downward movements. On the upside, the 255,000-point threshold remains the immediate psychological resistance, with a decisive breakout potentially strengthening bullish sentiment and encouraging further accumulation across selected equities.
However, the market would require stronger participation across more sectors to establish a more convincing upward breakout. Although the benchmark continues to advance, the mixed performance of individual stocks suggests that the rally is not yet evenly distributed. Sustained demand for banking, industrial and consumer-related equities could provide additional support, while a deterioration in market breadth may signal increasing caution among investors.
Trading volume and value will also remain important indicators in assessing the strength of the current rally. An increase in turnover accompanied by positive market breadth would provide stronger confirmation of renewed accumulation. Conversely, declining trading activity alongside repeated resistance around the 255,000-point region could indicate weakening momentum and increase the likelihood of short-term consolidation.
The immediate market outlook remains cautiously positive, supported by the strong year-to-date return and continued interest in selected large-cap stocks. Nevertheless, investors are likely to maintain a selective approach, considering corporate earnings, dividend expectations, valuation levels and prevailing macroeconomic conditions before increasing their exposure. The possibility of further profit-taking cannot be ruled out, particularly in stocks that have recorded significant gains in recent sessions.
Overall, the market appears to be consolidating its recent advances while maintaining an underlying bullish bias. The ability of the index to break above the 255,000-point resistance level, alongside improved market participation, will be important in determining whether the current upward movement can extend into another phase of appreciation.
Global Oil Market
International crude oil prices recorded another significant decline on Wednesday, falling by more than $3 per barrel as investors reassessed geopolitical developments and the possible implications of the US midterm elections for Washington’s involvement in the conflict with Iran.
Brent crude futures declined by $3.20, representing a 3.09% drop, to $100.40 per barrel, while US West Texas Intermediate crude fell by $3.01, or 3.13%, to $93.08. The decline extended the recent weakness in the international oil market, with Brent having settled at its lowest level in nearly four weeks during the previous session as traders weighed the prospects of diplomatic efforts to end the conflicts involving Iran and Ukraine.
The political outcome of the US midterm elections introduced additional uncertainty into the market. President Donald Trump’s Republican Party suffered significant electoral setbacks, with Democrats securing control of both the House of Representatives and the Senate. Trump acknowledged that the war involving Iran had contributed to his party’s poor performance, raising questions about the potential direction of US foreign policy and the administration’s approach to the conflict.
The developments have placed renewed attention on the possibility of diplomatic negotiations and their implications for global crude supply. Any meaningful reduction in tensions between Washington and Tehran could ease concerns about supply disruptions and reduce the geopolitical risk premium currently reflected in oil prices. However, a breakdown in negotiations or further military escalation could quickly reverse the downward trend, particularly given the strategic importance of the Middle East to global energy supply.
The oil market is therefore facing competing influences. On one hand, expectations of diplomatic progress could encourage further price corrections as traders reduce their exposure to geopolitical risk. On the other hand, uncertainty surrounding the conflict, potential supply disruptions and the possibility of renewed military action could provide a floor for prices. This leaves crude markets vulnerable to sharp movements as investors respond to political developments and changes in supply expectations.
For Nigeria, the movement in international crude prices remains particularly important given the country’s dependence on oil exports for foreign exchange earnings and government revenue. A sustained decline in crude prices could place additional pressure on projected oil receipts, especially if production levels remain below expectations. Conversely, elevated prices could support external earnings, although the benefits would depend on domestic production performance, export volumes and fiscal management.
The decline in oil prices also comes at a time when investors are closely monitoring global economic conditions, energy demand and geopolitical developments. Consequently, the direction of crude prices in the coming sessions will depend not only on developments in the Iran conflict but also on the broader balance between global supply and demand.
At the close of Wednesday’s trading, the NGX All-Share Index gained 473.46 points, representing a 0.19% increase, to settle at 254,762.81 points, while market capitalisation rose by ₦307.41 billion to ₦165.42 trillion, lifting the market’s year-to-date return to 63.72%. Trading statistics in the supplied reports were inconsistent, with one set recording 552.31 million shares valued at ₦37.46 billion in 33,047 deals, while another reported 431.18 million shares worth ₦25.26 billion in 32,815 deals. The reported market breadth was also inconsistent, with one account indicating 27 advancing stocks against 23 decliners, while another recorded 30 gainers against 26 losers. Nevertheless, the overall market direction remained positive. TRANSPOWER topped the gainers’ chart with a 9.97% appreciation to ₦203.00, followed by CAVERTON, which advanced 9.84% to ₦3.35, and ETRANZACT, which gained 9.68% to ₦17.00. HMCALL rose 7.36% to ₦3.50, while INTENEGINS appreciated by 7.27% to ₦1.77. On the losing side, ETERNA recorded the steepest decline, shedding 9.94% to close at ₦38.50. SOVRENINS fell 9.91% to ₦1.91, while LEARNAFRCA declined 9.84% to ₦8.25. CORNERST lost 9.30% to ₦3.90, and MBENEFIT depreciated by 6.85% to ₦2.72 each.