
Quarter Under Preview: – Third Quarter 2026
Current Share Price: N151.20
Latest Final Dividend: N6.25
Latest Interim Dividend: NIL
Estimated Beta Value: 0.52x
Estimated Fair Value: N135
Analyst: Jeariogbe Tunde Segun
The Company
NAHCO Plc (Nigerian Aviation Handling Company Plc) was incorporated on December 29, 1979, as a private limited liability company to provide aircraft handling services at Nigerian airports. It commenced operations in 1981 following the Federal Government’s decision to commercialize aviation ground handling services previously managed by the Federal Airports Authority of Nigeria (FAAN). Over the years, the company expanded its operations beyond passenger and ramp handling to include cargo handling, aircraft cleaning, aviation security, crew transportation, warehousing, and other aviation support services, making it one of the leading ground handling companies in Nigeria.
In 2005, NAHCO was privatized, marking a significant milestone in its growth and operational efficiency. The company was subsequently listed on the Nigerian Exchange (NGX), providing access to capital for expansion and modernization. Today, NAHCO operates in major airports across Nigeria and serves numerous international and domestic airlines. Through continuous investment in modern equipment, staff training, and technology, the company has maintained a strong reputation for safety, reliability, and operational excellence, while expanding into logistics and export processing to support Nigeria’s growing aviation and trade sectors.
Statement of Comprehensive Income
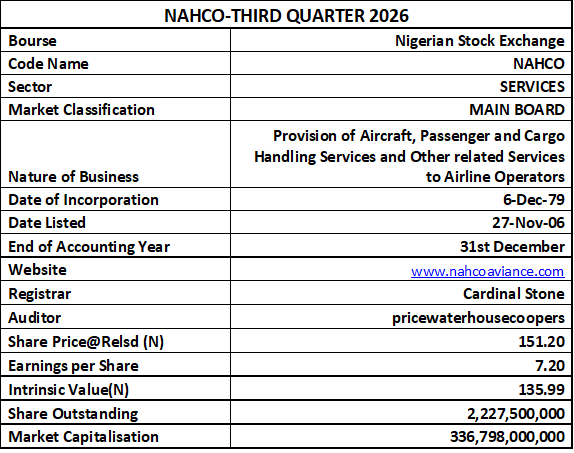
NAHCO Plc recorded a strong performance in the 2026 nine-month, with turnover increasing by 16.51% to ₦55.64 billion from ₦47.76 billion in the corresponding period of 2025. However, cost of sales rose by a significant 42.11% to ₦27.47 billion, eclipsing revenue growth, thereby indicating the presence of increased pressure on direct operating costs. Despite this, operating profit improved by 19.43% to ₦21.67 billion from ₦18.14 billion, reflecting the company’s ability to sustain operating profitability amid rising costs.
Operating expenses fell substantially by 37.17% to ₦6.68 billion from ₦10.64 billion, providing significant support to operating performance. Depreciation and amortization increased by 50.38% to ₦2.40 billion, suggesting a higher depreciation burden, while finance costs declined by 19.65% to ₦1.26 billion, indicating some improvement in financing expenses. Net finance income remained negative, deteriorating from negative ₦203.59 million to negative ₦429.68 million, reflecting increased net finance-related pressure. Nevertheless, profit before tax grew by 18.39% to ₦21.24 billion from ₦17.94 billion.
Profit after tax advanced by 19.21% to ₦16.04 billion compared with ₦13.46 billion in Q3 2025, while total comprehensive income also increased by 19.21% to ₦16.04 billion. The stronger bottom-line performance reflects the impact of improvement in operating efficiency, particularly the substantial reduction in operating expenses, despite the sharp increase in cost of sales and depreciation. Overall, NAHCO delivered encouraging earnings growth during the period, supported by revenue expansion and effective operating cost management. However, the rising cost of sales remains an important area to monitor for the sustainability of profit margins.
Statement of Financial Position
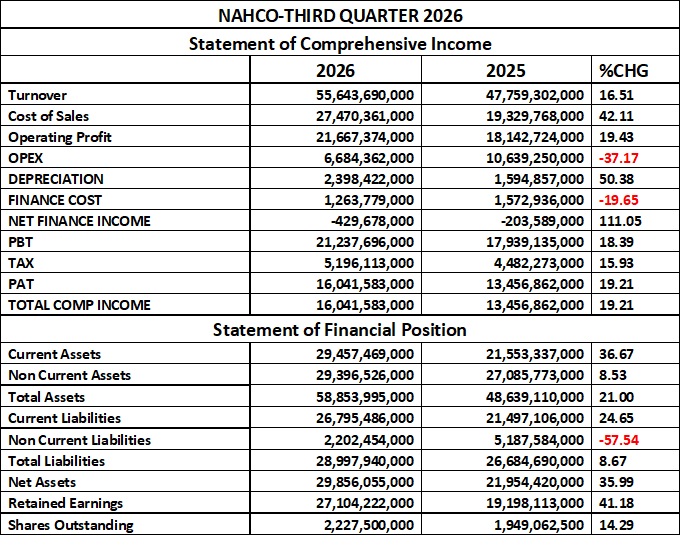
NAHCO Plc recorded a significant expansion in asset base in the period under review, with total assets increasing by 21.00% to ₦58.85 billion from ₦48.64 billion in 2025. Current assets grew by 36.67% to ₦29.46 billion, while non-current assets increased by 8.53% to ₦29.40 billion, indicating improvements in both short-term resources and long-term operating assets. The stronger growth in current assets suggests an improved short-term asset position, although the quality and composition of these assets would be important in assessing liquidity.
On the liabilities side, current liabilities increased by 24.65% to ₦26.80 billion from ₦21.50 billion, slightly outpacing current asset growth. However, non-current liabilities declined significantly by 57.54% to ₦2.20 billion from ₦5.19 billion, resulting in a moderate 8.67% increase in total liabilities to ₦29.00 billion. Consequently, net assets rose by 35.99% to ₦29.86 billion from ₦21.95 billion, reflecting a stronger equity position and a reduction in the company’s long-term debt obligations. The current ratio stood at approximately 1.10x, indicating that current assets exceed current liabilities, although the liquidity cushion remains relatively narrow.
Retained earnings increased by 41.18% to ₦27.10 billion from ₦19.20 billion, reflecting the accumulation of profits and strengthening of internally generated equity. Shares outstanding also increased by 14.29% to 2.228 billion from 1.949 billion, suggesting an expansion in the company’s share capital base. Overall, NAHCO’s financial position shows substantial asset growth, improved net assets and reduced long-term liabilities. However, the faster growth in current liabilities and the increase in outstanding shares warrant attention when assessing liquidity and shareholder value.
Financial Strength/Solvency Ratios
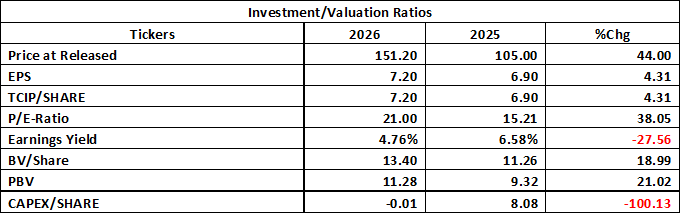
NAHCO’s financial strength and solvency position improved in Q3 2026 compared with the corresponding period of 2025. The debt ratio declined by 10.19% to 49.27% from 54.86%, indicating a lower proportion of assets financed by liabilities, while the total debt-to-equity ratio (MRQ) reduced by 20.09% to 0.97x from 1.22x, reflecting reduced financial leverage.
Similarly, the equity ratio improved by 12.39% to 50.73% from 45.14%, showing increased reliance on shareholders’ funds to finance the company’s assets. With a beta value of 0.52, the stock exhibits relatively low sensitivity to overall market movements. Overall, NAHCO demonstrates an improving capital structure, reduced debt exposure and stronger equity backing, suggesting a more sustainable financial position and moderate balance-sheet risk.
Profitability Ratios
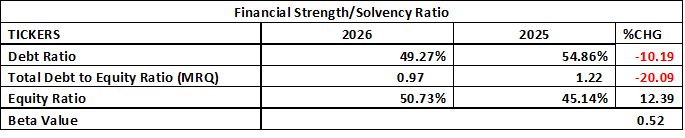
NAHCO Plc recorded a slight improvement in its Q3 2026 operating profit, with EBIT margin increasing to 38.94% from 37.99% in the corresponding period of 2025, representing a 2.51% improvement. Pre-tax margin also rose by 1.61% to 38.17% from 37.56%, indicating improved profit retention before taxation. The effective tax rate declined marginally by 2.75% to 32.39% from 33.31%, providing some relief to earnings. However, the cost-to-turnover ratio increased to 49.37% from 40.47%, representing a significant 21.98% rise, suggesting that the company’s cost of sales is consuming a larger proportion of revenue and exerting pressure on operating margins.
On shareholders’ returns, Return on Equity (ROE) declined by 12.34% to 53.73% from 61.29%, while Return on Assets (ROA) eased slightly by 1.48% to 27.26% from 27.67%. Although both ratios remain relatively strong, the decline in ROE indicates reduced returns generated from shareholders’ funds, while the marginal fall in ROA suggests a slight moderation in asset utilization efficiency. Overall, NAHCO maintains strong profitability levels, supported by healthy EBIT and pre-tax margins, but the rising cost-to-turnover ratio and declining returns on equity and assets are areas requiring attention.
Efficiency Ratios
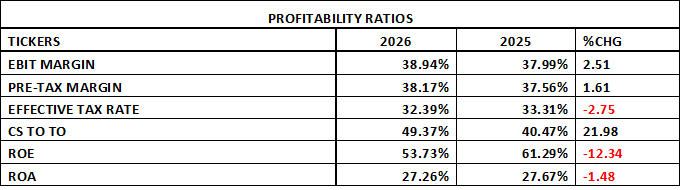
NAHCO Plc’s efficiency ratios present a mixed performance in Q3 2026. Operating expenses to turnover declined significantly by 46.07% to 12.01% from 22.28%, indicating improved control of operating costs relative to revenue. Turnover to total assets (asset turnover) moderated slightly to 0.95x from 0.98x, representing a 3.71% decline and suggesting a marginal reduction in asset utilization efficiency.
Working capital turnover fell sharply from 849.34x to 20.90x, a 97.54% decline, which may reflect a substantial change in the working capital base. However, the working capital ratio improved by 9.65% to 1.10x from 1.00x, indicating a modest improvement in short-term liquidity. Overall, NAHCO demonstrated better operating cost efficiency and marginally improved liquidity, although the decline in asset utilization and working capital turnover requires attention.
Investment/Valuation Ratio
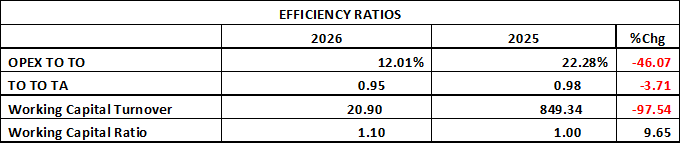
NAHCO Plc’s investment and valuation metrics indicate improved earnings performance alongside a significant appreciation in its share price. The price at release increased by 44.00% to ₦151.20 from ₦105.00, while earnings per share (EPS) and total comprehensive income per share (TCIP/share) rose by 4.31% to ₦7.20 from ₦6.90. However, the price-to-earnings (P/E) ratio increased by 38.05% to 21.00x from 15.21x, indicating that the market price has appreciated considerably faster than earnings. Consequently, earnings yield declined by 27.56% to 4.76% from 6.58%, suggesting a lower earnings return relative to the prevailing share price.
Book value per share improved by 18.99% to ₦13.40 from ₦11.26, reflecting growth in shareholders’ funds. However, the price-to-book value (PBV) ratio increased by 21.02% to 11.28x from 9.32x, indicating that the stock is trading at a substantial premium to its underlying book value. Capital expenditure per share also recorded a significant decline from ₦8.08 to negative ₦0.01, representing a reported 100.13% reduction, which requires further examination of the underlying capital expenditure figures. Overall, NAHCO’s earnings and book value are growing, but the faster appreciation in its share price has increased valuation pressure, making the stock relatively expensive on both earnings and book value measures.
Intrinsic Value Estimation
Based on NAHCO Plc’s Q3 2026 earnings performance, strong profitability, improving balance-sheet position, and growth prospects, an earnings-based valuation approach using a fair P/E multiple of 18.75x and EPS of ₦7.20 gives an estimated intrinsic value of ₦135.00 per share. This valuation reflects the company’s strong earnings-generating capacity while allowing for a reasonable discount to its prevailing market valuation. At a market price of ₦151.20, the stock trades approximately 10.71% above its estimated intrinsic value, suggesting limited immediate upside at the current price.
Final Investment Verdict-Hold
NAHCO Plc demonstrates strong underlying fundamentals, supported by revenue growth of 16.51%, profit after tax growth of 19.21%, improved operating efficiency and a stronger financial position. Its EBIT margin of 38.94%, ROE of 53.73% and reduced debt-to-equity ratio of 0.97x reflect a profitable business with improving financial strength. However, the significant increase in its share price relative to earnings growth has pushed valuation multiples higher, with the stock trading at 21.00x earnings and 11.28x book value. At the estimated intrinsic value of ₦135.00 against the market price of ₦151.20, the stock appears moderately overvalued. Consequently, HOLD is recommended, as the company’s fundamentals remain attractive, but the prevailing market price offers limited margin of safety for fresh investment. Existing shareholders may retain their positions while monitoring earnings growth and valuation.