Quarter Under Review: -THIRD QUARTER 2026
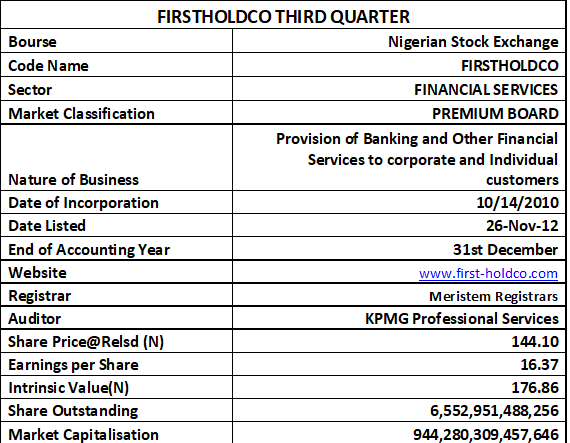
Current Share Price: N155.00
Latest Final Dividend: N0.60
Latest Interim Dividend: N
Estimated Beta Value: 1.68x
Estimated Intrinsic Value: N176.86
Ratings: Buy
Analyst: Jeariogbe Tunde Segun
The Company
First Holding Company Plc, formerly FBN Holdings Plc, has its roots in the long history of First Bank of Nigeria Plc, whose operations in the country began in 1894 as the Bank of British West Africa (BBWA), founded by Sir Alfred Jones. Over the years, the institution expanded and evolved through several name changes and mergers, becoming First Bank of Nigeria Limited in 1979 and First Bank of Nigeria Plc in 1991. FirstBank subsequently developed into a diversified financial-services group with interests extending beyond commercial banking into investment banking, asset management, trusteeship and insurance.
The creation of First HoldCo followed the restructuring of the FirstBank Group on the back of the Central Bank of Nigeria’s regulatory framework on banking groups and holding companies. The holding-company structure was designed to separate the commercial banking business from the Group’s other financial-services businesses, while allowing the various businesses to remain under a common corporate structure.
FBN Holdings was incorporated in 2010 and, following the restructuring, FirstBank became its wholly owned commercial-banking subsidiary. The shares of the former First Bank of Nigeria Plc were subsequently delisted on 23 November 2012, while FBN Holdings was listed on the Nigerian Stock Exchange on 26 November 2012.
Since its emergence as a holding company, First HoldCo has developed into a diversified financial-services group with businesses covering commercial banking, capital markets, asset management, trusteeship, securities brokerage and insurance brokerage. Its principal subsidiary remains FirstBank, supported by other businesses within the Group. In 2025, FBN Holdings changed its name to First HoldCo Plc, reflecting the Group’s continuing evolution and its broader identity beyond the traditional FirstBank franchise. Today, First HoldCo is listed on the NGX Premium Board and remains one of Nigeria’s major financial-services groups, combining the strength of the historic FirstBank franchise with a diversified portfolio of financial businesses.
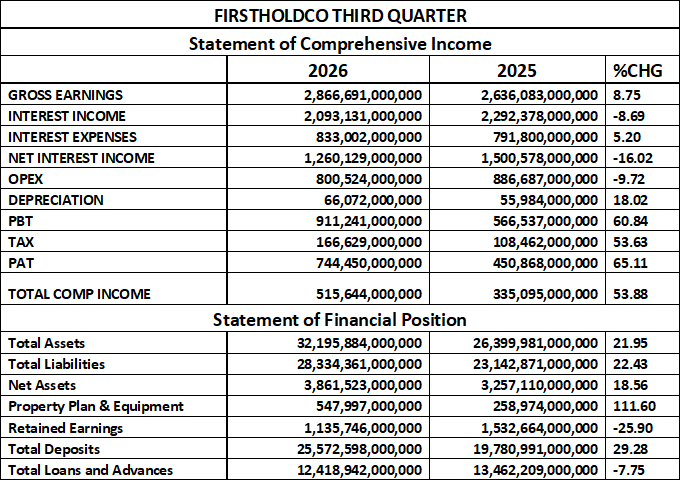
Statement of Comprehensive Income
First HoldCo’s 2026 nine-month performance presents a mixed operating picture, with gross earnings rising by 8.75% to ₦2.867 trillion, from ₦2.636 trillion in the similar period of 2025. However, interest income declined by 8.69% to ₦2.093 trillion, while interest expenses increased by 5.20% to ₦833.002 billion. Consequently, net interest income fell significantly by 16.02% to ₦1.260 trillion, indicating pressure on the Group’s core interest margin despite the growth in overall gross earnings.
Operating efficiency improved during the period, as expenses declined by 9.72% to ₦800.524 billion, compared with ₦886.687 billion in the corresponding period of 2025. Although depreciation increased by 18.02% to ₦66.072 billion, the reduction in operating expenses helped support profitability. This was reflected in the strong 60.84% increase in profit before tax (PBT) to ₦911.241 billion, from ₦566.537 billion in 2025. Tax expense also increased by 53.63% to ₦166.629 billion, but the increase in earnings was sufficiently strong to lift profit after tax (PAT) by 65.11% to ₦744.450 billion, compared with ₦450.868 billion in Q3 2025.
The Group’s total comprehensive income stood at ₦515.644 billion, representing a 53.88% increase from ₦335.095 billion in the previous year. Overall, the results indicate a substantial improvement in bottom-line profitability despite weakness in net interest income. The significant growth in PBT and PAT, together with the reduction in operating expenses, suggests improved cost management and stronger contribution from non-interest or other income sources. However, the decline in net interest income remains an area requiring attention, as sustained pressure on the core banking margin could affect the quality and durability of earnings going forward.
Statement of Financial Position
First HoldCo’s statement of financial position indicates a significant expansion in balance sheet during the period. Total assets increased by 21.95% to ₦32.196 trillion, for example, from ₦26.400 trillion in 2025, while total liabilities rose by 22.43% to ₦28.334 trillion. Consequently, net assets grew by 18.56% to ₦3.862 trillion, indicating an improvement in the Group’s underlying net worth. Property, plant and equipment recorded a particularly strong 111.60% increase to ₦547.997 billion, suggesting substantial investment in infrastructure and other fixed assets during the period.
On the funding side, total deposits increased by 29.28% to ₦25.573 trillion, from ₦19.781 trillion, providing a stronger deposit base for the Group’s operations. However, total loans and advances declined by 7.75% to ₦12.419 trillion, from ₦13.462 trillion, indicating a more cautious lending position despite the substantial growth in deposits. Retained earnings also declined by 25.90% to ₦1.136 trillion. Overall, the balance sheet shows strong asset and deposit growth, but the decline in loans and retained earnings suggests that the quality and deployment of the increased funding base will be important considerations in assessing First HoldCo’s future growth and profitability.
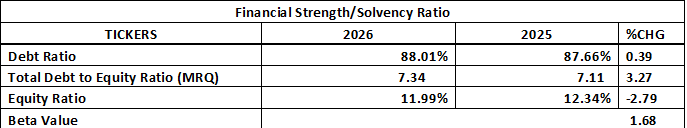
Financial Strength/ Solvency Ratio
First HoldCo’s financial strength and solvency position remained relatively stable in 2026, although the Group continues to operate with a high level of financial leverage. The debt ratio increased marginally to 88.01% from 87.66%, representing a 0.39% rise, while the total debt-to-equity ratio increased to 7.34 from 7.11, indicating a modest increase in leverage. Conversely, the equity ratio declined to 11.99% from 12.34%, suggesting that shareholders’ equity now represents a slightly smaller proportion of total assets.
The Group’s beta of 1.68 indicates that its share price carries relatively higher market sensitivity and volatility compared with the broader market. Overall, the ratios point to a highly leveraged financial structure, typical of a banking-led financial group, with relatively thin equity coverage; nevertheless, the changes year-on-year are moderate and do not, on their own, indicate a significant deterioration in solvency.
Profitability Ratios
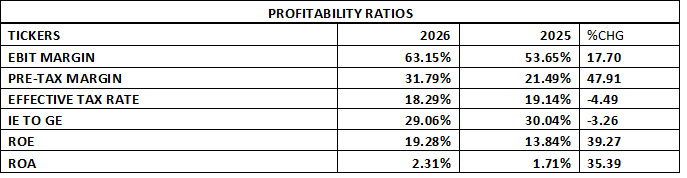
First HoldCo recorded a strong improvement in profitability in 2026, with EBIT margin rising to 63.15% from 53.65%, representing a 17.70% increase. Pre-tax margin also improved significantly by 47.91% to 31.79%, from 21.49% in 2025, reflecting the stronger growth in profit before tax relative to gross earnings. Meanwhile, the effective tax rate declined slightly to 18.29% from 19.14%, while interest expense to gross earnings reduced to 29.06% from 30.04%, indicating some improvement in the cost structure.
The improvement was also evident in returns generated for shareholders and on the asset base. ROE increased by 39.27% to 19.28%, from 13.84% in 2025, indicating that First HoldCo generated substantially more profit from shareholders’ funds. Similarly, ROA rose by 35.39% to 2.31%, from 1.71%, showing improved utilisation of the Group’s large asset base. Overall, the profitability ratios point to a marked improvement in earnings quality and operational profitability, with stronger margins and significantly better returns on both equity and assets, despite the continued pressure on net interest income.
Efficiency Ratios
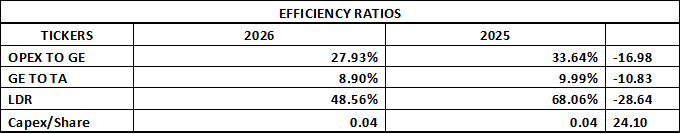
First HoldCo recorded a notable improvement in operating efficiency in 2026. Operating expenses to gross earnings (OPEX/GE) declined to 27.93% from 33.64%, representing a 16.98% reduction, indicating better cost control and improved efficiency in converting gross earnings into operating profit. Similarly, gross earnings to total assets (GE/TA) fell to 8.90% from 9.99%, a 10.83% decline, suggesting that earnings growth did not keep pace with the expansion in the Group’s asset base. The lower OPEX-to-gross-earnings ratio, however, is a positive indication of improved cost management.
The loan-to-deposit ratio (LDR) declined substantially to 48.56% from 68.06%, representing a 28.64% reduction. This means a smaller proportion of customer deposits was deployed as loans and advances, consistent with the reported decline in loans despite strong deposit growth. While this may reflect a more conservative lending posture and potentially lower credit risk, it could also indicate under-utilisation of the Group’s growing deposit base. Capex per share remained at ₦0.04, although the reported change of 24.10% suggests an increase in the underlying capital expenditure relative to the comparative period. Overall, the efficiency ratios present a mixed picture, with stronger cost efficiency but weaker asset and deposit deployment.
Investment/Valuation Ratios
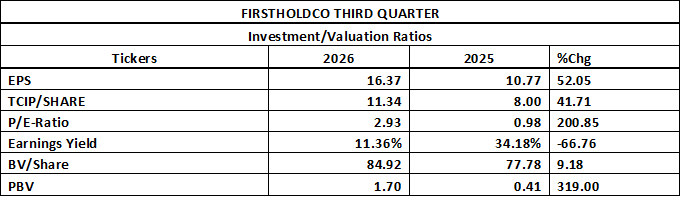
First HoldCo’s investment and valuation indicators show a significant improvement in earnings performance in 2026. EPS increased by 52.05% to ₦16.37, from ₦10.77 in 2025, while TCIP per share rose by 41.71% to ₦11.34, from ₦8.00. The strong growth in EPS reflects the substantial increase in profit after tax recorded during the period. However, the P/E ratio increased sharply to 2.93x from 0.98x, representing a 200.85% increase (please note that our PE/Ratio is technically adjusted for 9-months), as the market valuation of the shares rose relative to earnings. Consequently, the earnings yield declined to 11.36% from 34.18%, although the current yield remains indicative of a relatively low earnings multiple.
The Group’s book value per share increased to ₦84.92 from ₦77.78, representing a 9.18% improvement and indicating growth in shareholders’ underlying value. However, the price-to-book value (PBV) ratio rose substantially to 1.70x from 0.41x, reflecting a significant re-rating of the shares relative to their book value. Overall, the investment indicators present a combination of strong earnings and book-value growth but a considerably higher market valuation. The sharp rise in P/E and PBV means that while First HoldCo’s fundamentals have improved, investors are now paying a higher premium for the company’s earnings and net assets compared with the previous year.
Final Verdict — First HoldCo Plc
First HoldCo delivered a strong improvement in profitability in Q3 2026, with PBT rising 60.84%, PAT increasing 65.11%, ROE improving to 19.28% and ROA to 2.31%. Cost efficiency also strengthened, while deposits grew by 29.28%. The major concerns are the 16.02% decline in net interest income, 7.75% contraction in loans and advances, and relatively high leverage. Nevertheless, the overall fundamentals remain positive, particularly given the substantial growth in earnings and shareholders’ value.
Our Overall rating is BUY on the strength of Strong Fundamentals/Moderate Valuation Risk. First HoldCo’s earnings growth, improving ROE, stronger cost efficiency and rising book value provide a positive fundamental case. The principal caution is that the shares have already experienced a significant valuation re-rating, with P/E rising from 0.98x to 2.93x and PBV from 0.41x to 1.70x. At an intrinsic-value reference of about ₦177, the stock offers a positive fundamental outlook, but the actual margin of safety is relatively tiny as against the prevailing market price.