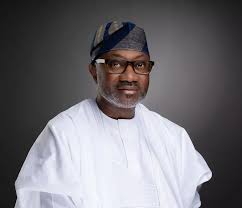
Caption: Olufemi Otedola, Chairman, First HoldCo Plc
In what may well signal that its worst days are over, First Holding Company Plc, on Friday published its unaudited result for the nine-months ended September 30, 2026, that further rekindled hope that the board, after some many years of drought could recommend dividend payment at the end of full-years to expectant shareholders that have had to make do with capital appreciation over the period of drought. Recall that the directors had, some months ago, announced a policy of paying 60% of net profit as dividend yearly, subject to approval of its primary regulator- the Central Bank of Nigeria (CBN).
According to the latest financials, the group announced a robust 65.11% growth in net profit, despite the marginal 8.79% rise in gross earnings for the period, also at a time when interest income slowed down. The growth in net profit could have been much more significant, but for the 53.63% increase in income tax expense.
Gross earnings stood at ₦2.868tr, increasing by ₦231.859bn from ₦2.636tr in the corresponding period of last year, of which the commercial banking group contributed a significant ₦2.701tr, followed by ₦120.069bn from investment banking and asset management group. Interest income slipped marginally to o ₦2.093tr from ₦2.292tr. Of this figure, customer loans and advances fetched ₦1.304tr compared to the previous ₦1.459tr; followed by investment securities contributed ₦651.228bn, down from ₦720.151bn; while loans and advances to banks accounted for ₦136.915bn compared to ₦112.705bn.
Interest expense rose to ₦833.002bn from ₦791.8bn, driven by the ₦656.532bn expended on customer deposits, from ₦489.197bn; deposit from banks dropped from ₦202.014bn to ₦87.525bn; while borrowings and others cost ₦88.845bn, a drop from ₦100.589bn. Net interest income, therefore, dropped to ₦1.260tr from ₦1.5tr.
Impairment charge for losses dropped to ₦207.096bn from ₦288.919bn, driven by ₦202.696bn loss in customer loans and advances, which dropped from ₦267.433bn. Increase in impairment dropped to ₦4.198bn from ₦21.548bn. This resulted in net interest income after impairment charge for losses of ₦1.053tr, compared with the ₦1.211tr reported in the corresponding period of 2025.
Fee and commission income jumped by 40.92% to ₦367.063bn from ₦260.477bn, boosted by the ₦73.164bn electronic banking fees which rose from ₦68.8bn. This was followed by ₦51.446bn income from financial advisory fees up from just ₦1.002bn in the preceding nine months. The bulk of this income (₦47.43bn) was earned between July and September. Commission and fees from Letters of credit contributed ₦48.084bn, down from ₦49.173bn; just as fund transfer and intermediation fees rose to ₦40.12bn from ₦36.96bn, among others. Expense rose to ₦50.634bn from ₦46.783bn, representing a subdued growth of 8.23%; following which net fee and commission income stood at ₦316.429bn from ₦213.694bn.
Foreign exchange gains improved to ₦86.242bn from ₦71.943bn, the bulk of which was the ₦70.49bn foreign exchange trading income compared to ₦32.405bn in the first nine months of 2025; while foreign exchange revaluation gains dropped from ₦39.538bn to ₦15.752bn. Net gains on sale of investment securities contributed ₦61.121bn from ₦48.492bn; just as net gains from financial instruments at face value stood at ₦104.588bn, as against the previous nine-month’s ₦72.779bn loss. A breakdown of which showed that trading gains on debt securities fetched ₦1346.94bn from ₦25.788bn; while fair value losses amounted to ₦32.352bn, an improvement from the ₦98.567bn loss in the corresponding period of last year. Dividend income contributed ₦12.488bn, a marginal increase over the ₦11.74bn in the corresponding period of last year, representing dividend income earned from other equity investment held by subsidiaries of First HoldCo Plc.
Other operating income for the period also soared from ₦23.832bn to ₦142.058bn, derived the ₦94.308bn recoveries, which leaped from ₦5.884bn; while other income contributed ₦47.349bn from ₦16.85bn in 2025. Other operating expenses was mainly boosted by the Asset Management Company of Nigeria levy of ₦112.944bn, up from ₦110.825bn; ahead of ₦82.568bn spent on IT maintenance from ₦68.006bn; other repairs and maintenance dropped from ₦42.954bn to ₦35.526bn; just as advert and corporate promotions costs fell to ₦42.263bn from ₦121.604bn.
Personnel expenses dropped to ₦280.833bn from ₦290.65bn. Depreciation, amortization and impairment grew to ₦66.072bn from ₦55.984bn; just while other operating expenses dropped from ₦596.037bn to ₦519.691bn; resulting in an operating profit of ₦909.363bn, representing a growth from 565.91bn. A ₦1.878bn share of profit of associates, up from the previous ₦627m, left profit before tax at ₦911.241bn from ₦566.910bn.
Income tax expenses for the period, however jumped by ₦58.167bn to ₦166.629 from ₦108.462bn, of which ₦157.596bn represented current income tax, up from ₦97.474bn; while origination of temporary deferred tax differences dropped to ₦9.033bn from ₦10.988bn. This resulted in profit after tax of ₦744.612bn from ₦458.075bn, which translates to earnings per share of ₦16.45, up from ₦10.65 each. The 2025 nine-month EPS is a pointer that the group could outperform the all-time full-year peak EPS of ₦18.21 reported by its precursor First Bank of Nigeria Plc.
A further breakdown of the numbers showed that the Commercial Banking pooled ₦2.045tr of total interest income, accounting for ₦810.251bn interest expense, ₦784.771bn PBT and ₦133.798bn income tax expense and ₦650.973bn net profit. Investment Banking and Asset Management Growth pooled ₦120.069bn in total revenue, ₦23.739bn income tax and ₦62.578bn net profit; while ₦31.061bn of net profit was derived from what the group classified as “others.”
The balance sheet also recorded growth from ₦27.25tr as of December 31, 2025 to ₦32.195tr, boosted by investment securities valued at ₦10.309tr from ₦6.97tr, while customer loans and advances stood at ₦9.393tr, a marginal rise from the ₦8.966tr at the end of the 2025 full-year. Total liabilities climbed from ₦23.949tr at the end of 2025 full-year to ₦28.334tr, with customer deposits accounting for the lion’s share of ₦22.909tr from ₦18.883tr. Shareholders’ funds (total equity) for the period rose to ₦3.861tr from ₦3.301tr.