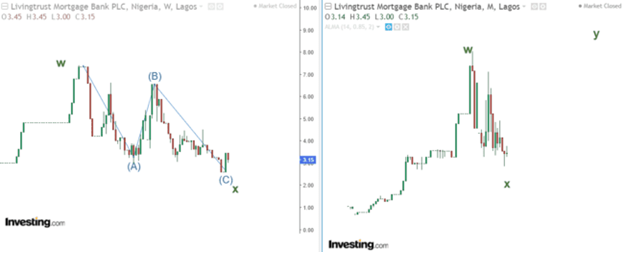
LivingTrust Mortgage Bank Plc is a Nigerian financial institution focused on mortgage banking. Its official website maintains investor-relations disclosures, financial statements, information on funded projects and property-development partnerships. The NGX classifies the company under Financial Services, within the mortgage banking subsector
Current price: N3.20
Rating: Buy
Price projection: N6 and N9
Technical Analysis
In this report, we shall use the following tools and analysis methods:
Elliott’s wave theory to understand the overall market sentiment
Fibonacci tools to determine support and resistance levels
The Relative Strength Index and volume to evaluate the market’s strength
The Money Flow Index to determine the market liquidity
Moving average and MACD to understand the nature of the trend
Top-down analysis to know the best investment position
Elliott wave analysis
Weekly chart: Market overview
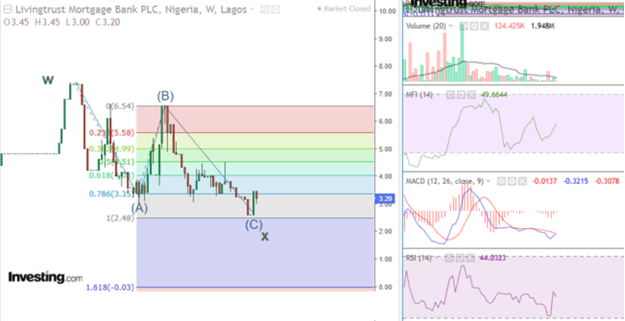
The stock saw a deep flat correction on the weekly chart in Wave X of the grand cycle. Plotting the Fibonacci extension tool, the stock retrace to the 1.0 Fibonacci level and initiated its recovery phase with a strong bullish candlestick.
In line with this performance, the stock’s liquidity and momentum improved. Notable, MACD sustained its bearish divergence signal, preparing investors for a trend reversal. Thus, traders should watch for strong volume
Daily chart: Trading opportunity
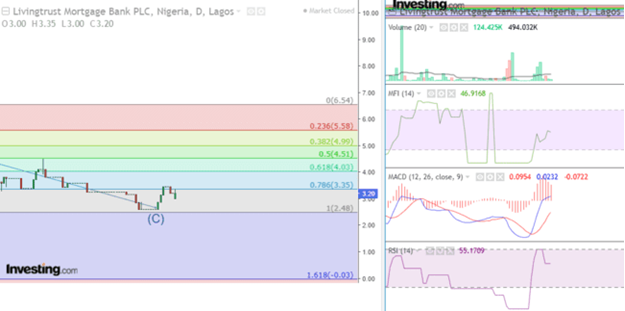
On the daily chart, Living Trust pulled back and met strong support at N3, signalling continuous interest. This performance gradually improved the stock’s liquidity and momentum. Since MACD sustained its bullish divergence, traders should watch N2.50 and N2 as potential support levels, with prices projected at N6 and N9.
SWOT Analysis
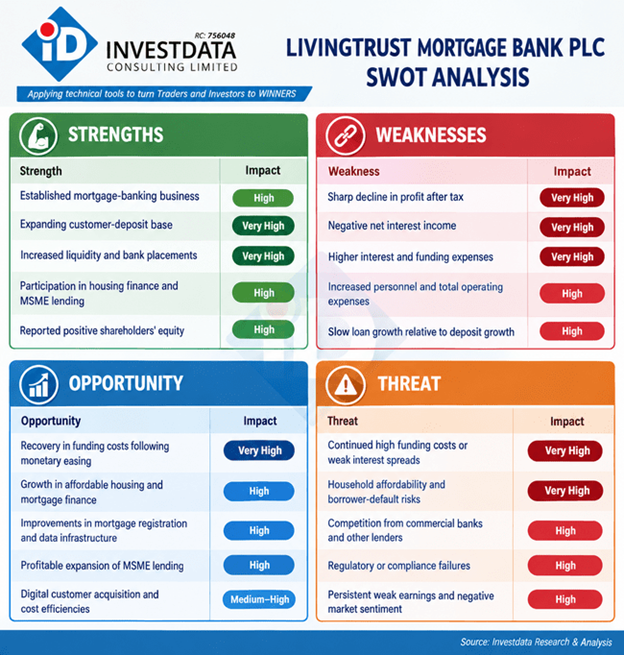
LivingTrust Mortgage Bank Plc has growth potential supported by its expanding customer-deposit base, improved liquidity and opportunities in mortgage finance and MSME lending.
However, the sharp decline in H1 2026 profit, negative net interest income and rising operating costs remain significant weaknesses. While lower funding costs, affordable-housing initiatives and digital transformation could support recovery, persistent funding pressures, borrower-default risks and intense competition pose threats.
Ultimately, LivingTrust’s investment prospects will depend on its ability to convert deposit growth into profitable lending, restore sustainable earnings and improve cost efficiency. Investors should therefore remain cautious until financial results demonstrate a clear recovery in core profitability, supported by a sustained improvement in the share-price trend.