
Market Update For November 20, 2026
The Nigerian equities market extended its bearish performance on Friday, November 20, 2026, following sustained profit-taking in heavyweight and selected stocks which continued to undermine market sentiment. Sell pressure across banking, consumer goods and other counters outweighed gains in selected equities, leaving the benchmark index in negative territory for another session. The development reflected cautious investor positioning as market participants continued to lock in profits following the strong gains recorded earlier in the year.
The sell-off was particularly evident in FIRSTHOLDCO, HONYFLOUR, ETERNA, TRANSCORP, ZENITHBANK, ACCESSCORP, NGXGROUP and GTCO. Other stocks, including UBA, FIDELITYBK and NEM, also closed lower, reinforcing the negative direction of the market. The performance of banking stocks was particularly significant, as losses in ZENITHBANK, ACCESSCORP, GTCO, UBA and FIRSTHOLDCO contributed to the pressure on the broader market.
Despite the widespread losses, selective buying interest remained in a few counters, particularly in the insurance, healthcare and financial services segments. However, the gains recorded in these stocks were not enough to offset the losses in large-cap equities, leaving the overall market direction bearish.
Trading activity also weakened, suggesting a moderation in investor participation amid the prevailing cautious sentiment. Total volume declined by 17.85% to 305.63 million shares, while transaction value stood at ₦16.55 billion across 29,606 deals. FIDELITYBK remained the most actively traded stock by volume, with 29.20 million shares exchanged, representing 9.55% of total market volume. GTCO followed among the most actively traded equities, accounting for 6.98% of total volume, while ZENITHBANK contributed 6.51%.
In terms of transaction value, GTCO maintained its dominance with ₦2.46 billion worth of shares traded, representing 14.89% of total market value. ZENITHBANK and STANBIC also featured among the leading stocks by value, highlighting continued investor activity in major banking counters despite the broader market weakness.
The decline in trading volume alongside the negative market breadth suggests that investors were increasingly selective, with buying interest concentrated in a limited number of stocks. This pattern indicates that market participants may be adopting a more cautious approach while assessing valuations, corporate earnings prospects and prevailing economic conditions.
Oil Market Rebounds on Middle East Supply Concerns
International crude oil prices edged higher on Friday as escalating geopolitical tensions in the Middle East renewed concerns about potential disruptions to global energy supplies. Reports of Houthi missile attacks on Saudi Arabia’s capital, Riyadh, alongside reported tanker incidents around the strategically important Strait of Hormuz, raised concerns about the security of crude oil transportation and the possibility of supply interruptions.
Brent crude advanced 0.6% to $92.57 per barrel, while US West Texas Intermediate (WTI) gained 0.5% to $83.63 per barrel. The modest recovery reflected renewed geopolitical risk premiums as investors assessed the implications of rising regional tensions for global oil supply.
Technical Analysis and Market Outlook
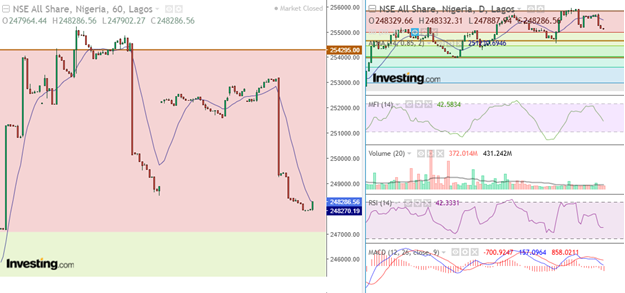
From a technical perspective, the NGX’s continued weakness points to a deterioration in short-term market momentum, with persistent selling pressure preventing the benchmark index from establishing a sustainable recovery. The decline to 247,660.74 points reflects growing resistance from profit-taking activities, particularly in heavyweight banking and consumer stocks.
The inability of the index to maintain its previous closing level of 248,286.56 points suggests that buyers are yet to regain sufficient control of the market. The 247,000-point region is an important near-term support area to monitor, while the 248,286-point level represents the immediate resistance zone based on the previous session’s close. A sustained move above this level could improve short-term sentiment and create room for a recovery towards higher resistance levels.
However, a decisive break below the 247,000-point region could expose the market to further declines as investors continue to reduce positions in stocks that have recorded substantial year-to-date appreciation. The direction of the market will also depend on whether bargain hunters return to fundamentally sound stocks and whether institutional investors increase their exposure to equities.
The negative market breadth, with decliners significantly outnumbering advancers, further confirms the weakness in market sentiment. Although selected stocks recorded impressive gains, the limited participation on the buying side suggests that the market has yet to establish a broad-based recovery.
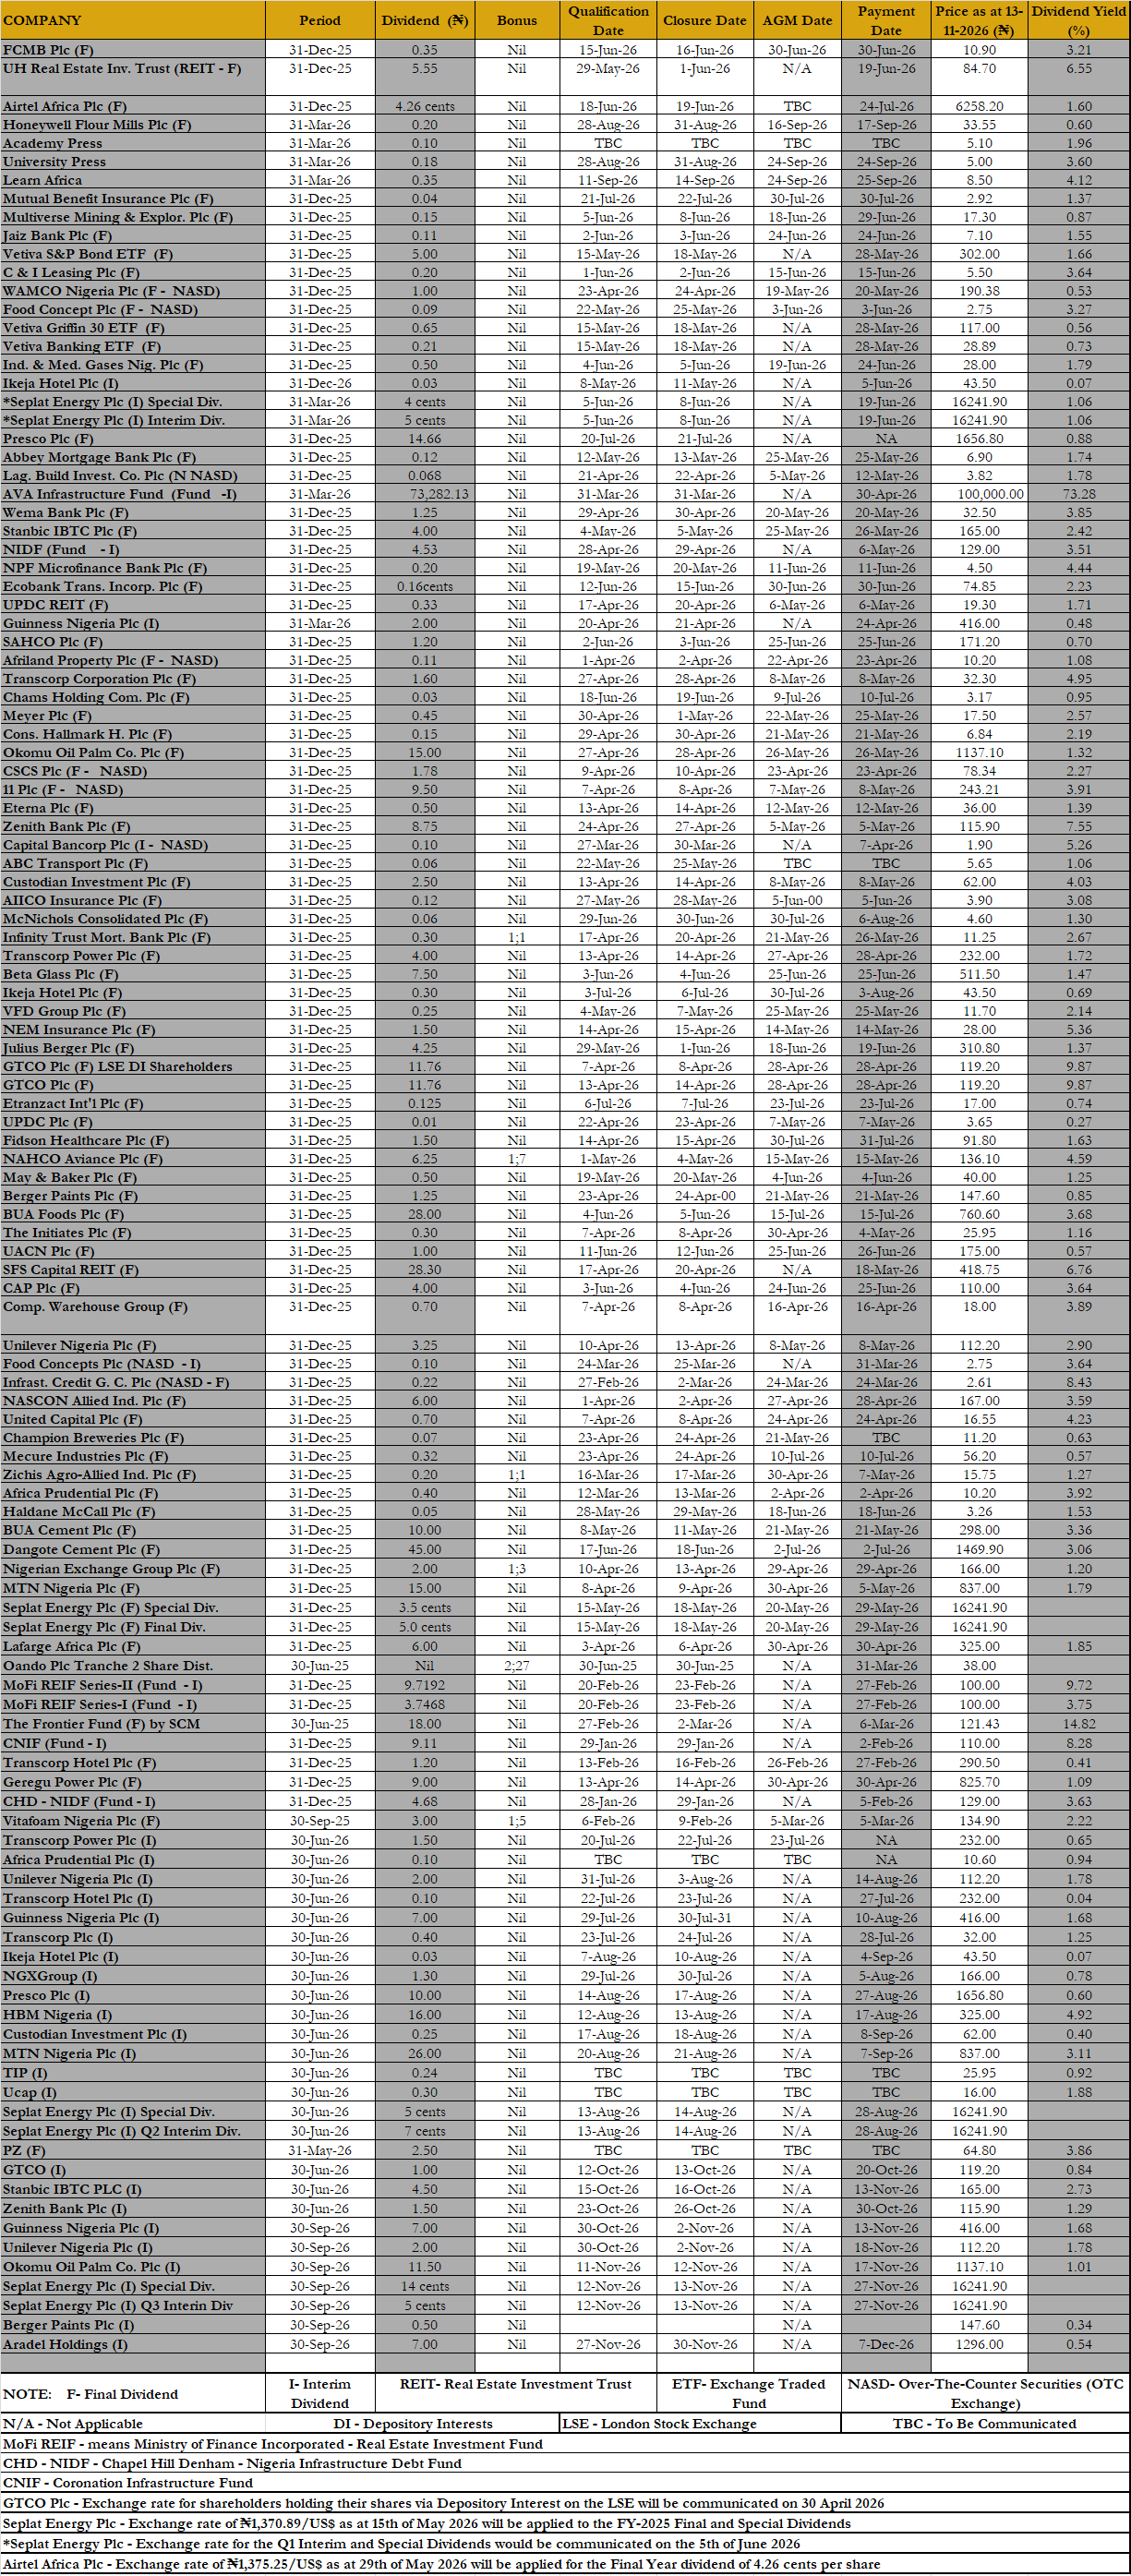
Going into the next trading session, investors are expected to remain cautious, with attention likely to focus on banking stocks, corporate earnings, dividend expectations and opportunities in fundamentally strong companies trading at attractive valuations. Selective accumulation may provide support for stocks experiencing temporary price corrections, while continued profit-taking in heavyweight counters could keep the broader market under pressure.
The NGX All-Share Index (ASI) declined by 0.25%, shedding 625.82 points to close at 247,660.74 points against 248,286.56 points recorded in the previous session. The decline translated into an estimated loss of ₦406.34 billion in market capitalisation, which settled at approximately ₦161.73 trillion, while the market’s year-to-date return moderated to 59.15%. Trading activity weakened, with total volume falling by 17.85% to 305.63 million shares, valued at ₦16.55 billion in 29,606 deals. FIDELITYBK led volume transactions with 29.20 million shares, representing 9.55% of total volume, while GTCO and ZENITHBANK accounted for 6.98% and 6.51%, respectively. In terms of value, GTCO dominated transactions with ₦2.46 billion, representing 14.89% of total traded value, followed by ZENITHBANK and STANBIC. Market breadth remained negative, with 14 equities advancing against 36 decliners, reflecting sustained selling pressure across the market. MAYBAKER led the gainers, appreciating by 10.00% to ₦44.00, followed by CORNERST, which gained 9.89% to ₦5.00; NPFMCRFBK rose 8.99% to ₦4.85; ABBEYBANK advanced 8.80% to ₦6.80; and WAPIC added 7.24% to ₦2.37. On the losers’ chart, AFRIPRUD recorded the steepest decline, shedding 10.00% to close at ₦10.80, followed by FTGINSURE, which fell 9.55% to ₦1.80; LEARNAFRCA lost 9.41% to ₦7.70; MEYER declined 9.40% to ₦14.45; and CMFC dropped 9.04% to ₦3.52. Other notable decliners included FIRSTHOLDCO (-4.36%), HONYFLOUR (-3.64%), ETERNA (-3.19%), TRANSCORP (-2.90%), ZENITHBANK (-2.81%), ACCESSCORP (-2.41%), NGXGROUP (-2.31%), GTCO (-1.72%), UBA (-1.04%), FIDELITYBK (-0.21%) and NEM (-0.18%).