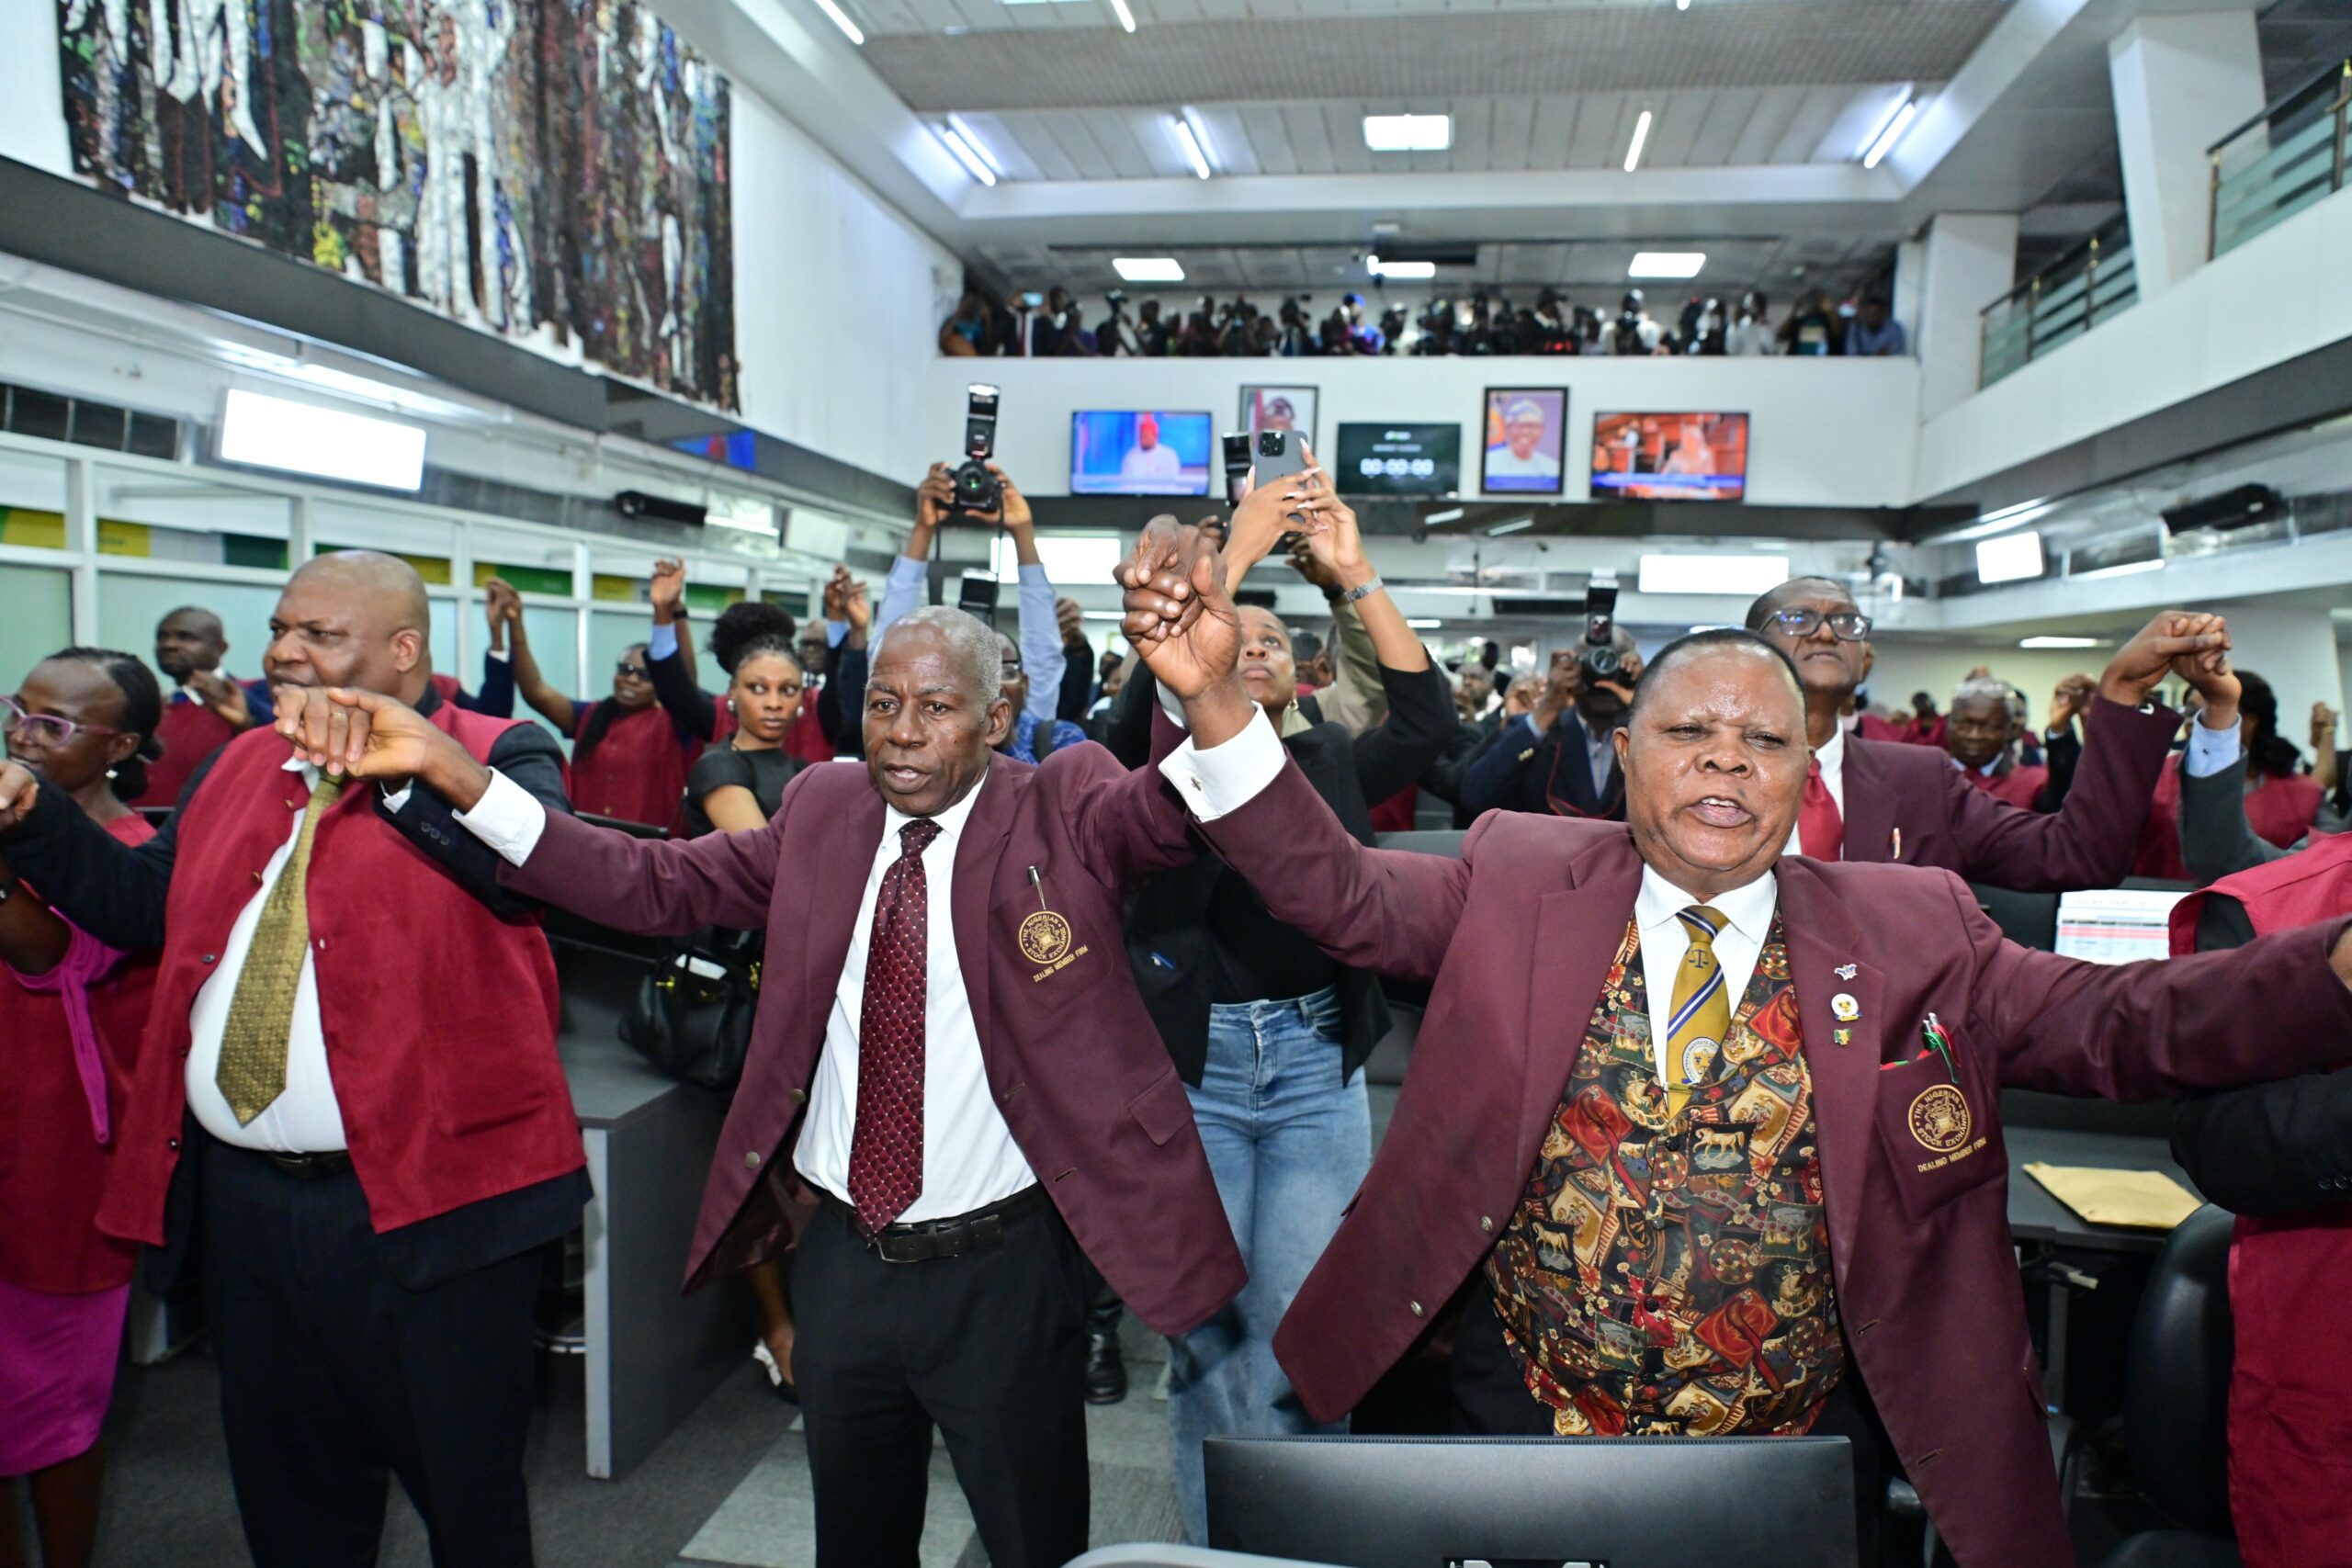
Market Update For September 23, 2026
The Nigerian equities market extended its positive run on Wednesday as sustained buying interest across selected stocks pushed the benchmark higher, with investors maintaining demand for major counters despite increased selling pressure in some pockets of the market.
The session continued the recent upward movement in Nigerian equities, with the All-Share Index maintaining its position above the 250,000-point mark. Buying interest was particularly visible across banking, industrial, consumer and other actively traded stocks, helping the broader market maintain a positive tone.
The latest advance followed another positive session on Tuesday, suggesting that investors are continuing to support equities as the market approaches the next major technical resistance area.
Among the stocks that attracted strong demand was ETERNA, which recorded the largest gain of the session. NAHCO, MAYBAKER and NASCON also posted substantial advances, while gains in major banking stocks helped provide additional support to the index.
ZENITHBANK was one of the notable banking gainers, rising 2.27%, while FIRSTHOLDCO and ACCESSCORP also recorded gains. Other stocks such as TIP, IMG, MTNN, OANDO, GTCO and STANBIC contributed to the positive performance.
The distribution of gains across different sectors suggests that the market’s advance was not driven by a single industry. However, the relatively moderate movement in the index compared with some individual stocks also indicates that gains remained concentrated in selected counters.
Trading activity was another major feature of the session. Turnover strengthened significantly as investors exchanged more than 1.5 billion shares, with FTGINSURE accounting for more than half of the total volume.
The heavy activity in FTGINSURE was followed by strong transactions in other actively traded counters, while GTCO dominated the market in terms of transaction value. The banking sector continued to attract substantial investor attention, with ZENITHBANK and FIDELITYBK also featuring prominently among the most traded stocks.
The increase in market activity alongside the positive close provides an indication of sustained participation. However, higher turnover also means that the market is likely to see increased two-way activity as investors lock in gains in some counters while taking fresh positions in others.
The session was also marked by significant declines in several stocks. CAVERTON fell 9.09%, making it the worst-performing stock for the day, while UPL declined 9.00%. SOVRENINS, CHAMS and WAPIC also recorded notable losses.
The weakness in some counters was further highlighted by new price lows. VERITASKAP touched a 52-week low of ₦1.04, while AFRIPRUD traded below its previous 52-week low before settling at ₦10.10.
Despite these declines, the broader market remained positive, with advancing stocks comfortably outnumbering decliners. This indicates that buying interest was sufficiently strong to offset losses in several counters.
Technical Analysis
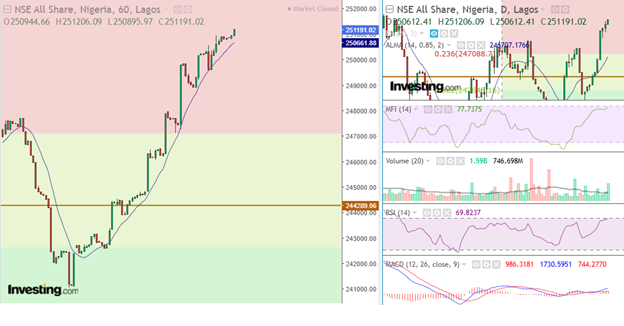
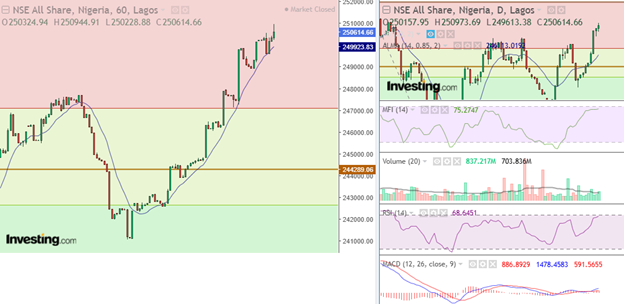
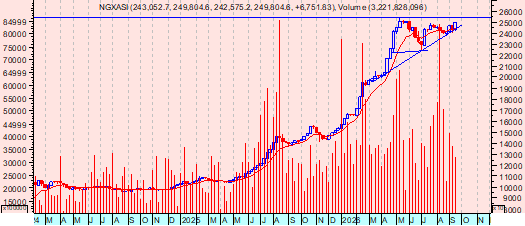
Technically, the NGX All-Share Index remains in a short-term upward trend. The benchmark has maintained its position above the 250,000-point psychological level, which has now become an important reference point for near-term market direction.
Wednesday’s close at 251,191.02 points places the index closer to the 252,500-point resistance zone. The market will need stronger follow-through buying to break decisively above this area.
A sustained move above 252,500 points could strengthen the current upward momentum and encourage further buying. However, failure to clear the resistance could result in some investors taking profits following the recent gains.
The 250,000-point level remains the immediate support. A break below this level could expose the index to the 248,000-point area, while a deeper correction could bring the 246,000-point region into focus.
Trading volume will remain an important technical consideration. Strong volume accompanying further gains would indicate continued participation, while a decline in volume during an advance could suggest weakening momentum.
The market’s breadth also remains constructive, although the performance of large-cap stocks will continue to have a significant influence on the direction of the benchmark.
Outlook
The outlook for the Nigerian equities market remains centred on whether the current buying interest can carry the ASI through the 252,500-point resistance level.
Investors are likely to continue monitoring banking stocks and other highly capitalised counters, given their influence on the broader index. Continued demand for these stocks could provide the momentum required for the market to test higher levels.
At the same time, the market’s strong year-to-date performance means profit-taking remains a possibility, particularly around key resistance levels. The divergence between the day’s strongest and weakest performers also suggests that investors are becoming more selective in allocating funds.
Sector rotation could therefore remain a major feature of trading, with investors moving between counters based on earnings expectations, valuations, corporate developments and short-term price momentum.
For the broader market, maintaining the 250,000-point level would preserve the current short-term structure, while a decisive break above 252,500 points would mark an important technical development. Conversely, a sustained move below 250,000 points could increase selling pressure and shift attention towards lower support levels.
Oil Market
The global oil market also remained a key factor for investors, particularly given the importance of crude oil revenues to Nigeria’s fiscal and external position.
Oil prices recovered on Wednesday after falling to their lowest levels in more than two weeks in the previous session. Brent crude futures rose $1.33, or 1.34%, to $100.58 per barrel by 1303 GMT, while West Texas Intermediate gained 65 cents, or 0.72%, to $91.17.
The recovery followed a sharp decline in the previous session, when Brent fell to $97.36 per barrel, its lowest level since September 8. WTI also touched its lowest level since September 1 earlier on Wednesday.
Improving Gulf crude supplies continued to weigh on prices, although concerns around refined products provided some support. European low-sulphur gasoil’s premium to Brent climbed to a record level of about $95 a barrel as the market responded to a global diesel supply shortage.
The possibility of restrictions on US diesel exports has also added another layer of uncertainty to the refined-products market, with traders assessing the potential impact on global supply.
Against this backdrop, the Nigerian equities market maintained its upward momentum. The NGX All-Share Index gained 576.36 points, or 0.23%, to close at 251,191.02 points, while market capitalisation increased by ₦374.14 billion to ₦163.06 trillion. The market’s year-to-date return rose to 61.42%.
Trading activity strengthened, with 1.59 billion shares valued at ₦45.80 billion exchanged in 49,736 deals. Market breadth remained positive, with 46 stocks advancing, 23 declining and 77 unchanged. FTGINSURE dominated volume with 860.31 million shares, representing 54.09% of total volume, while GTCO led value transactions at ₦11.85 billion.
Top gainers were ETERNA, which rose 10.00% to ₦38.50; THOMASWY, up 9.88% to ₦2.78; HMCALL, which gained 9.70% to ₦3.28; OMATEK, up 9.63% to ₦1.48; and JOHNHOLT, which advanced 9.59% to ₦8.00. Top losers were CAVERTON, down 9.09% to ₦4.00; UPL, which fell 9.00% to ₦4.55; SOVRENINS, down 7.69% to ₦2.04; CHAMS, which declined 7.16% to ₦3.24; and WAPIC, which lost 6.30% to close at ₦2.23 each.