Market Update For September 22, 2026
The Nigerian Exchange (NGX) extended its positive run on Tuesday, September 22, 2026, as sustained demand for selected large-cap equities pushed the market further above the 250,000-point psychological threshold.
The session reflected continued confidence in major banking, consumer and industrial stocks, with investors maintaining buying interest despite pockets of profit-taking across the market. The advance was supported by gains in several heavyweight counters, helping the benchmark index maintain its upward trajectory.
Although the pace of appreciation moderated compared with some of the stronger sessions recorded recently, the market’s ability to remain firmly above 250,000 points remains significant from a technical perspective. The latest advance also came with stronger trading activity, suggesting that investor participation remained healthy.
Banking stocks were again prominent during the session, with ZENITHBANK recording the highest traded value and FIDELITYBK dominating volume. GTCO, UBA, ACCESSCORP and FIRSTHOLDCO were also among the banking and financial stocks that contributed to the positive market performance.
Outside the banking space, CADBURY and STANBIC posted strong gains, while DANGCEM, PZ, NGXGROUP, OANDO, NEM and NB also closed higher.
The market’s advance was not broad-based across every counter, but the performance of several influential stocks was sufficient to keep the overall index in positive territory.
CADBURY emerged as one of the strongest major gainers, rising 8.29%, while STANBIC appreciated by 7.09%. UBA gained 4.07%, CUSTODIAN advanced 2.71%, ZENITHBANK rose 2.64% and GTCO added 2.54%.
Other notable gainers included HBMNG, which increased 1.83%, FIRSTHOLDCO at 1.75%, DANGCEM at 1.71%, PZ at 1.22%, NGXGROUP at 1.09%, OANDO at 0.98%, NEM at 0.70%, ACCESSCORP at 0.67%, NB at 0.58% and WEMABANK at 0.16%.
The gains across these counters provided support for the broader market and showed that demand remained present across different segments of the equities market.
However, the session also demonstrated that investors were not buying indiscriminately. Selling pressure remained visible in several counters, particularly among stocks that had previously attracted significant interest.
MULTIVERSE recorded the steepest decline of the session, falling 9.86%. HMCALL declined 9.39%, MBENEFIT dropped 8.38%, CHAMS shed 8.26%, while MANSARD fell 6.67%.
The contrasting performance between gainers and losers suggests that investors are increasingly repositioning within the market, with liquidity moving towards selected stocks rather than producing a uniform rally across all sectors.
Market activity improved substantially during Tuesday’s session.
A total of 837.26 million shares were traded, representing a 45.82% increase compared with the previous session. The transactions were executed in 52,126 deals, with total market value reaching ₦48.57 billion.
The increase in both volume and transaction value provides evidence of stronger market participation. It also indicates that the positive movement in the index occurred alongside meaningful turnover.
FIDELITYBK remained the most actively traded stock by volume, recording 165.43 million shares, equivalent to 19.76% of total market volume.
ZENITHBANK and CHAMS also featured prominently in volume activity, contributing 12.62% and 8.58%, respectively, to total traded volume.
On the value side, ZENITHBANK remained the market’s leading stock, recording ₦13.73 billion in transactions. This represented 28.27% of the day’s total value.
GTCO and MTNN were also among the stocks contributing significantly to value turnover.
The strong concentration of turnover in banking stocks highlights the continued importance of the sector to overall NGX liquidity. With several banks also posting gains, the sector provided both price and volume support to the market.
Market breadth remained supportive of the upward movement, with 39 stocks recording gains against 29 decliners, while 78 equities closed unchanged.
The positive breadth indicates that the advance was not entirely dependent on one or two stocks. Nevertheless, the relatively large number of unchanged stocks also points to some degree of caution among investors.
The market’s breadth will therefore remain an important indicator in the coming sessions. A continued increase in the number of advancing stocks alongside higher turnover could strengthen the broader market structure, while a narrowing breadth despite rising index levels could indicate increasing selectivity and profit-taking.
Price activity was also notable at the lower end of the market. REGALINS touched a new 52-week low of ₦0.70, while LEGENDINT traded below its previous 52-week low before closing at ₦3.40.
These movements underline the divergence currently taking place beneath the headline index, with some stocks experiencing strong accumulation while others remain under pressure.
Technical Analysis
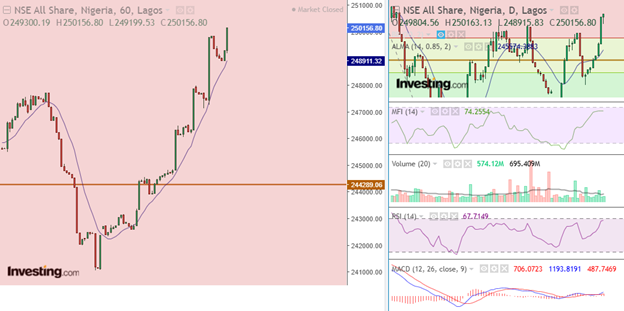
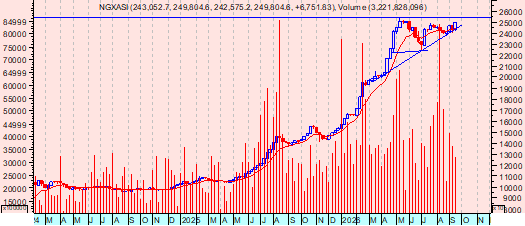
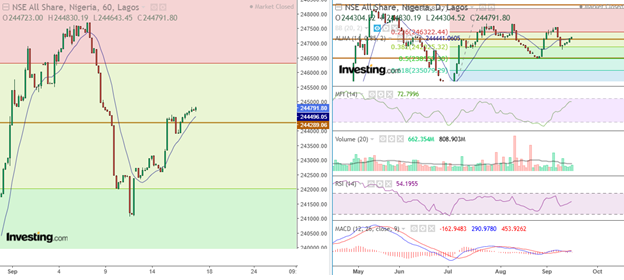
From a technical standpoint, Tuesday’s close maintained the NGX’s short-term bullish structure.
The ASI closed at 250,614.66 points, keeping the index above the psychologically important 250,000-point threshold. This level is increasingly important because sustained trading above it would provide a stronger base for the next leg of the market’s movement.
The immediate resistance remains around 252,500 points. A decisive break above this area, supported by stronger volume and positive breadth, could create room for the index to extend its advance toward higher levels.
On the downside, the 250,000-point region has become an important near-term support zone. A sustained close below this level could signal increased profit-taking and raise the possibility of a retracement toward lower support areas.
The technical structure therefore remains constructive, but the market is approaching a zone where additional buying pressure may be required to sustain the momentum.
Trading volume will be particularly important. A breakout above resistance accompanied by higher turnover would provide stronger confirmation than an advance occurring on declining activity.
Similarly, market breadth should be monitored closely. A healthy continuation of the rally would ideally involve broader participation from equities rather than reliance on a limited number of heavyweight stocks.
The performance of banking stocks remains one of the major features of the current market.
ZENITHBANK, GTCO, UBA, ACCESSCORP and FIRSTHOLDCO all recorded gains during Tuesday’s session, while ZENITHBANK dominated value turnover.
The strong activity in the banking segment is significant because the sector contains some of the largest and most liquid companies on the NGX. Movements in these counters can therefore have a meaningful impact on the overall direction of the ASI.
Investor interest in the sector could continue to be shaped by expectations around earnings, capital requirements, dividends, interest-rate conditions and broader economic developments.
At the same time, the market’s performance outside banking remains important. Gains in CADBURY, DANGCEM, PZ, NB, OANDO and other non-bank counters demonstrate that investor interest is not confined entirely to financial stocks.
Oil Market
The international oil market remained another important consideration for investors on Tuesday, with crude prices trading close to the $100-per-barrel level.
Brent crude futures for November traded at approximately $99.94 per barrel, down $0.40 or 0.40%, while West Texas Intermediate (WTI) futures traded around $95.43 per barrel, down $0.36 or 0.37%.
Oil prices remained elevated as traders assessed risks to global supplies arising from geopolitical developments involving Iran and the broader Middle East.
The market was also monitoring diplomatic developments at the United Nations, with expectations around possible negotiations adding another layer of uncertainty to the oil market.
For Nigeria, crude oil prices remain particularly important because oil exports are a major source of foreign-exchange earnings and government revenue. Changes in the international oil market can therefore influence the country’s external liquidity, fiscal position, exchange-rate expectations and overall investor sentiment.
A sustained period of relatively high crude prices could provide some support to Nigeria’s external accounts, although geopolitical disruptions to production, shipping routes or exports could also create significant volatility.
Market Outlook
The NGX enters the next trading session with its bullish structure intact, but the market is approaching an important technical area.
The immediate focus will be whether the ASI can maintain its position above 250,000 points and subsequently challenge the 252,500-point resistance.
Continued buying interest in large-cap banking stocks, stronger trading activity and broader market participation could provide support for further gains. Conversely, increased profit-taking, weakening breadth or a decline below the 250,000-point support could lead to a period of consolidation.
Investors are also likely to remain selective as the market continues to trade at elevated levels. Corporate earnings expectations, company-specific developments, dividend prospects and valuation considerations could increasingly determine individual stock performance.
The Dangote Refinery IPO, developments around Nigeria’s inclusion in the FTSE Russell Frontier Index and movements in foreign investor flows are also expected to remain relevant to market sentiment.
The commencement of Nigeria’s FTSE Russell Frontier Index status on September 21 could increase attention on eligible Nigerian large-cap stocks and potentially influence institutional positioning over time.
Meanwhile, global developments, particularly crude oil prices, Middle East tensions, global monetary policy and movements in the dollar, will remain important external variables.
Market Summary
The NGX All-Share Index (ASI) gained 457.86 points, or 0.18%, to close at 250,614.66 points, compared with 250,156.80 points on Monday. Market capitalisation increased by ₦297.21 billion to ₦162.68 trillion, while the market’s year-to-date performance rose to 61.05%. Total volume traded increased by 45.82% to 837.26 million shares, while value traded stood at ₦48.57 billion across 52,126 deals. Market breadth remained positive, with 39 equities advancing, 29 declining and 78 unchanged. FIDELITYBK led trading volume with 165.43 million shares, accounting for 19.76% of total volume, while ZENITHBANK recorded the highest value traded at ₦13.73 billion, representing 28.27% of total value. ZENITHBANK and CHAMS contributed 12.62% and 8.58%, respectively, to total volume, while GTCO and MTNN also ranked among the leading stocks by value. Among the top gainers, SOVRENINS rose 9.95% to ₦2.21, NEIMETH gained 8.90% to ₦7.95, CADBURY advanced 8.29% to ₦60.10, FTGINSURE increased 7.73% to ₦1.95, and STANBIC rose 7.09% to ₦163.85. The top losers were MULTIVERSE, down 9.86% to ₦19.20, HMCALL, down 9.39% to ₦2.99, MBENEFIT, down 8.38% to ₦3.50, CHAMS, down 8.26% to ₦3.22, and MANSARD, down 6.67% to ₦11.20 each.