Guinea Insurance Plc is a long-established Nigerian non-life insurance company, incorporated in 1958 and listed on the Nigerian Exchange in January 1970. Its business covers motor, marine, fire and special risks, oil and gas, aviation, agriculture, travel and other general insurance products. The company serves individuals, businesses and corporate clients.
Current price: N0.70
Rating: Buy
Price projection: N1.60 and N2.00
Technical Analysis
In this report, we shall use the following tools and analysis methods:
Elliott’s wave theory to understand the overall market sentiment
Fibonacci tools to determine support and resistance levels
The Relative Strength Index and volume to evaluate the market’s strength
The Money Flow Index to determine the market liquidity
Moving average and MACD to understand the nature of the trend
Top-down analysis to know the best investment position
Elliott wave analysis
Weekly chart: Market overview
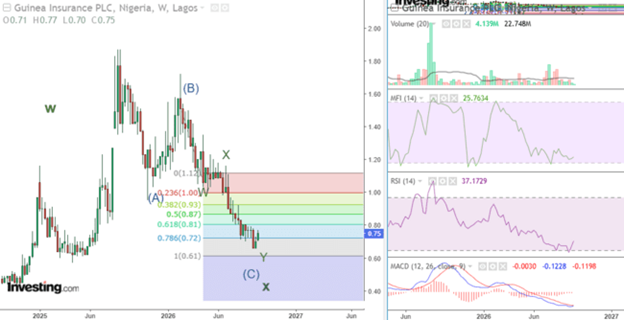
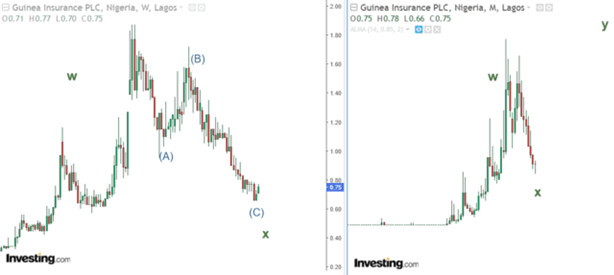
On the weekly chart, Guinea completed Wave Y of the minor degree, trading within the 1.0 Fibonacci level. This performance signifies bearish exhaustion as the stock experienced a deep correction. Therefore, traders should expect a bullish market. In line with this performance, Guinea’s liquidity, volume, and momentum initiated their recovery phase. Also, MACD sustained its divergence signal.
Daily chart: Trading opportunity
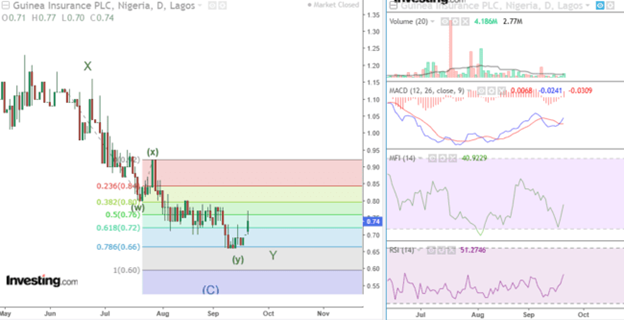
On the daily chart, Guinea began its recovery after finding support at the 1.0 Fibonacci level. In line with this performance, the stock’s volume closed strongly above its moving average, signalling strong bullish momentum. Also, liquidity and momentum improved. Thus, traders should watch N0.65 and N0.60 as potential support levels, with prices projected at N1.60 and N2.00.
SWOT Analysis
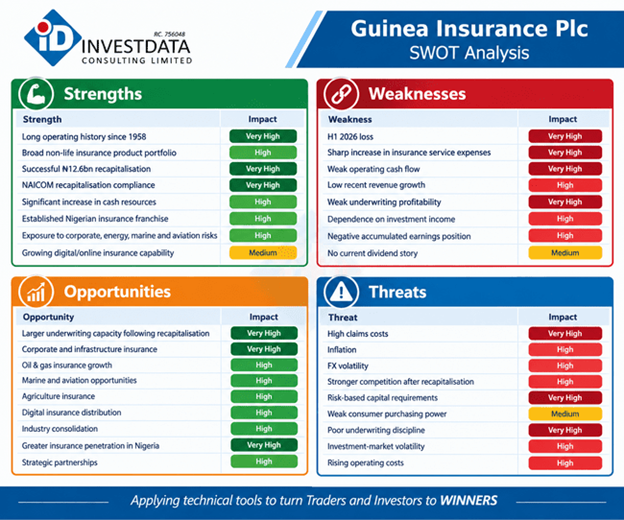
Guinea Insurance’s SWOT profile reflects a company with a stronger capital foundation and significant growth opportunities following its successful recapitalisation. Its long operating history, broad insurance portfolio and improved capital position provide a platform for expansion, particularly in corporate, energy, marine and other specialist insurance segments. However, weak H1 2026 profitability, rising claims and negative operating cash flow remain key concerns.
Going forward, the company’s ability to convert its stronger capital base into profitable underwriting, improve claims management and generate sustainable cash flow will be critical. Overall, Guinea Insurance presents a potential recovery and growth opportunity, but investors should closely monitor earnings quality, underwriting performance and cash generation before assuming that the benefits of recapitalisation will translate into stronger shareholder returns.