Market Update For September 21, 2026
The Nigerian equities market sustained its positive momentum on Monday, September 21, 2026, as the Nigerian Exchange (NGX) extended its winning streak to eight consecutive trading sessions, supported by renewed buying interest across several stocks
Also, Nigeria officially returned to the FTSE Russell Frontier Market status, a major reclassification that marks the end of a three-year absence since the country was downgraded to “Unclassified” status in September 2023 following a severe foreign-exchange liquidity crisis and capital repatriation. The reclassification comes with advantages for the Nigerian market such as the inflow of Global tracker funds from investors tied to FTSE Russell indices who are now systematically adjusting their portfolios to re-include Nigerian equities. This is expected to translate into a surge in market capitalization as seen in the bourse in recent days, lifting the NGX equities market capitalisation to ₦162.2 trillion. Companies expected to benefit most significantly from the reclassification having been exposed to global funds 0Guaranty Trust Holding Company (GTCO), Zenith Bank, FBN Holdings, MTN Nigeria, Dangote Cement, Aradel Holdings.
The market opened Monday on a firm footing as investors continued to position in selected equities, although the overall movement of the benchmark index remained moderate. The session reflected a combination of strong demand for selected stocks and profit-taking in some counters that have recently recorded significant gains.
The continued advance comes after the market recorded seven straight sessions of gains last week, reinforcing the positive sentiment that has characterised the NGX in recent sessions. However, Monday’s relatively modest index gain suggests that investors are becoming more selective, with attention increasingly focused on individual stock fundamentals, liquidity and near-term price opportunities.
Buying interest was spread across several sectors and stocks. TRANSCORP, OANDO, CADBURY, UACN, GTCO, NB, ACCESSCORP and NGXGROUP were among the notable gainers, providing support for the broader market. NASCON and THOMASWYATT also recorded double-digit gains to lead the gainers’ table.
The performance of banking stocks was mixed but generally supportive of the market. GTCO gained 3.00%, while ACCESSCORP advanced 2.74% and ZENITHBANK edged higher by 0.16%. The movement in these highly liquid counters remains important to the overall direction of the market because of their significant contribution to trading activity and market capitalisation.
The consumer goods segment also recorded notable buying interest, with CADBURY and NB advancing 4.72% and 2.99%, respectively, while NASCON rose by the maximum 10.00%. TRANSCORP also attracted strong demand, gaining 6.78%, while OANDO advanced 4.85%.
Despite the broad positive sentiment, selling pressure remained visible in several counters. OKOMUOIL suffered the steepest decline, falling 10.00%, while SOVRENINS, HMCALL, CUSTODIAN and FIRSTHOLDCO also recorded sizeable losses. The divergence between the strongest gainers and decliners highlights the increasing level of stock-specific activity in the market.
Trading activity improved during the session, pointing to stronger investor participation. A total of more than 574 million shares changed hands in over 68,000 deals, with ZENITHBANK dominating both volume and value turnover.
The heavy activity in ZENITHBANK reinforces the importance of institutional and retail participation in highly liquid banking counters. The stock accounted for a sizeable portion of the day’s traded volume and value, while ARADEL and GTCO also featured among the leading stocks by value traded.
The market also recorded notable movements around its 52-week trading range. UPDCREIT traded around its 52-week high at about ₦19.90, reflecting continued demand in the stock. At the other end, TRIPPLEG traded below its 52-week low, underscoring the uneven performance among individual equities despite the broader market’s positive direction.
Investor sentiment remained constructive as the market maintained its upward trajectory. The positive breadth indicates that buying interest extended beyond a few major index constituents, with more stocks participating in the advance.
However, the market’s eight-session winning streak also raises the possibility of short-term profit-taking. Investors who entered positions earlier in the rally may begin to lock in gains, particularly in stocks that have recorded sharp price appreciation.
This could produce a more volatile trading pattern in the coming sessions, with the direction of the index increasingly dependent on the performance of heavyweight stocks and the ability of buyers to sustain demand at elevated price levels.
The market may therefore experience periods of consolidation as investors reassess valuations and determine whether to maintain existing positions or take profits. Such consolidation would not necessarily invalidate the broader upward trend, particularly if the index continues to hold above important technical support levels.
Technical Analysis and Outlook
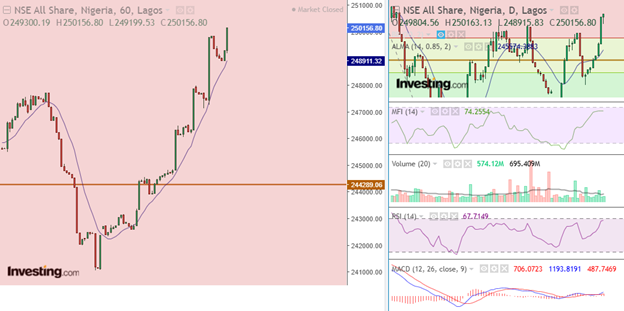
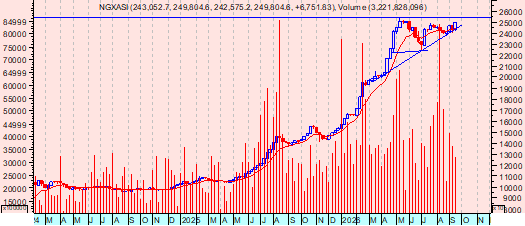
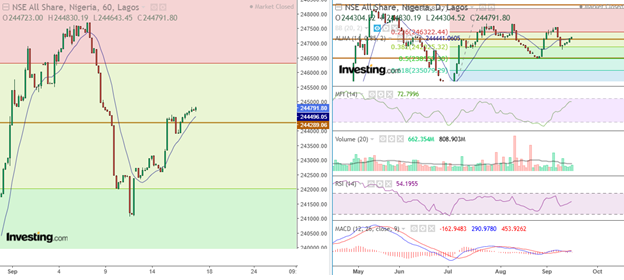
Technically, the NGX All-Share Index remains in a short-term bullish phase after crossing the 250,000-point psychological threshold. The index has continued to post higher closes, supported by sustained demand across selected stocks.
The 252,500-point region remains the immediate resistance level to monitor. A strong break above this zone, accompanied by increased volume and broader participation, could reinforce the current bullish structure and signal further upward movement.
On the downside, the 248,000–249,000-point region remains an important near-term support area. As long as the index holds above this zone, the prevailing short-term bullish structure remains intact. A decisive break below support, however, could expose the market to increased profit-taking and a deeper correction.
Momentum indicators would also need to be monitored closely following the extended rally. Eight consecutive positive sessions indicate strong market momentum, but prolonged advances can also leave some stocks vulnerable to short-term reversals as traders secure gains.
Volume will therefore remain an important confirmation signal. Further index gains accompanied by stronger turnover would indicate that demand remains healthy. Conversely, a decline in volume during additional advances could suggest weakening participation and the possibility of consolidation.
The outlook for the market will also depend on the performance of banking, consumer and industrial stocks, which continue to provide significant support to the broader index. Sustained institutional interest in liquid large-cap counters could help the market maintain its upward bias, while broad-based profit-taking could temporarily moderate the pace of gains.
Oil Market
Developments in the international oil market remain another factor for investors to monitor. Crude prices fell sharply on Monday as markets assessed the possibility of diplomatic progress in the Iran conflict and expectations of a partial recovery in Saudi shipments.
Brent crude futures declined 2.6% to $101.18 per barrel, while US West Texas Intermediate crude fell 2.7% to $97.61 per barrel. Both benchmarks touched their lowest levels since September 10 during Monday’s trading session.
The decline came as investors monitored developments ahead of this week’s United Nations General Assembly, where diplomatic discussions could influence expectations around the conflict involving Iran and the United States.
For Nigeria, movements in crude prices remain important because of the oil sector’s contribution to government revenue and foreign exchange earnings. A prolonged decline in oil prices could affect sentiment around Nigeria’s external position and fiscal outlook, although the immediate impact on listed equities would depend on the duration and magnitude of the price movement.
The domestic market, however, continues to benefit from strong year-to-date gains, meaning investor behaviour could increasingly shift from broad-based buying to selective positioning. Companies with stronger earnings prospects, attractive valuations and consistent liquidity may continue to attract attention as investors balance the opportunity for further gains against the risk of a market correction.
Overall, Monday’s session showed that the NGX remains supported by positive momentum, but the relatively small index gain after eight consecutive advances suggests that the market could enter a more selective phase. The ability of the ASI to sustain its position above 250,000 points, combined with trading volume and breadth, will be important in determining whether the current rally extends further or pauses for consolidation.
The NGX All-Share Index (ASI) gained 352.24 points, or 0.14%, to close at 250,156.80 points, compared with 249,804.56 points on Friday. Market capitalisation increased by ₦228.25 billion to ₦162.39 trillion, while the market’s year-to-date return rose to 60.76%. Market breadth remained positive, with 41 stocks advancing against 28 decliners, while 77 stocks closed unchanged. THOMASWYATT and NASCON led the gainers with 10.00% each, followed by FTGINSURE (+9.70%), LEARNAFRCA (+7.50%) and UPDCREIT (+7.28%). The top losers were OKOMUOIL (-10.00%), SOVRENINS (-8.64%), HMCALL (-8.33%), CUSTODIAN (-6.67%) and FIRSTHOLDCO (-5.38%). Trading volume stood at 574.12 million shares, valued at ₦38.04 billion, across 68,506 deals, with ZENITHBANK recording the highest volume at 77.07 million shares.