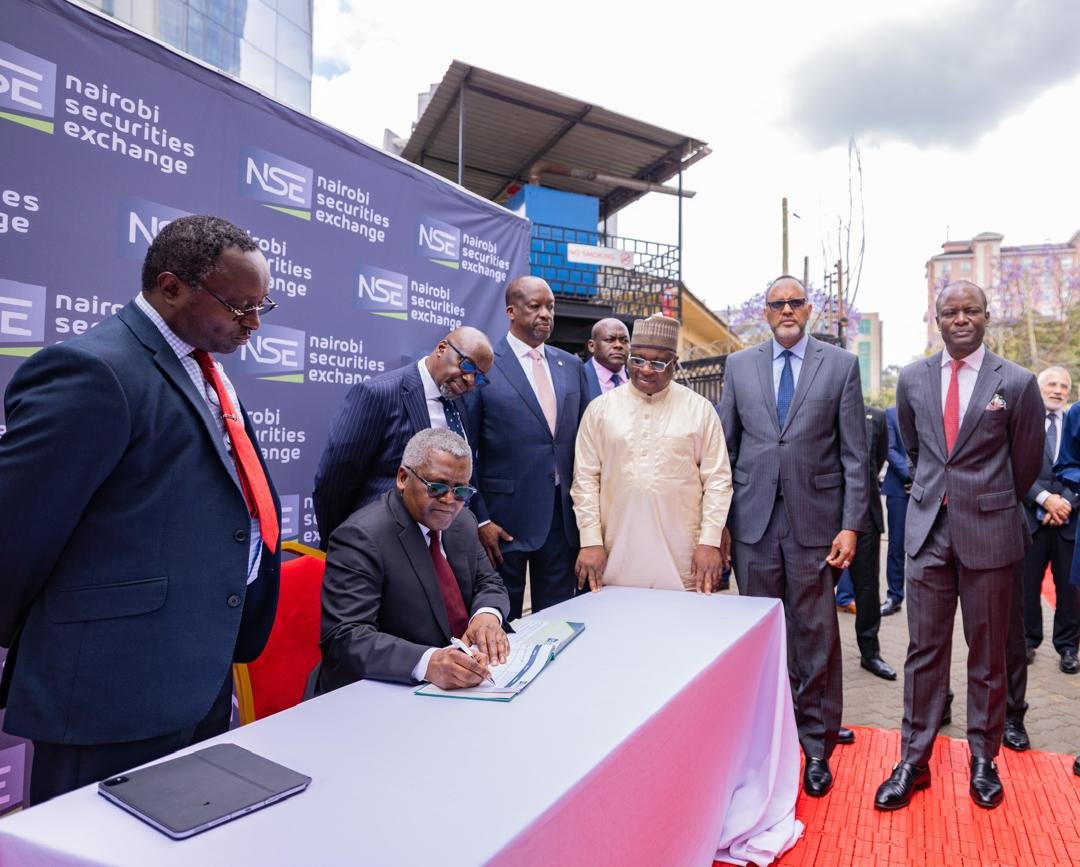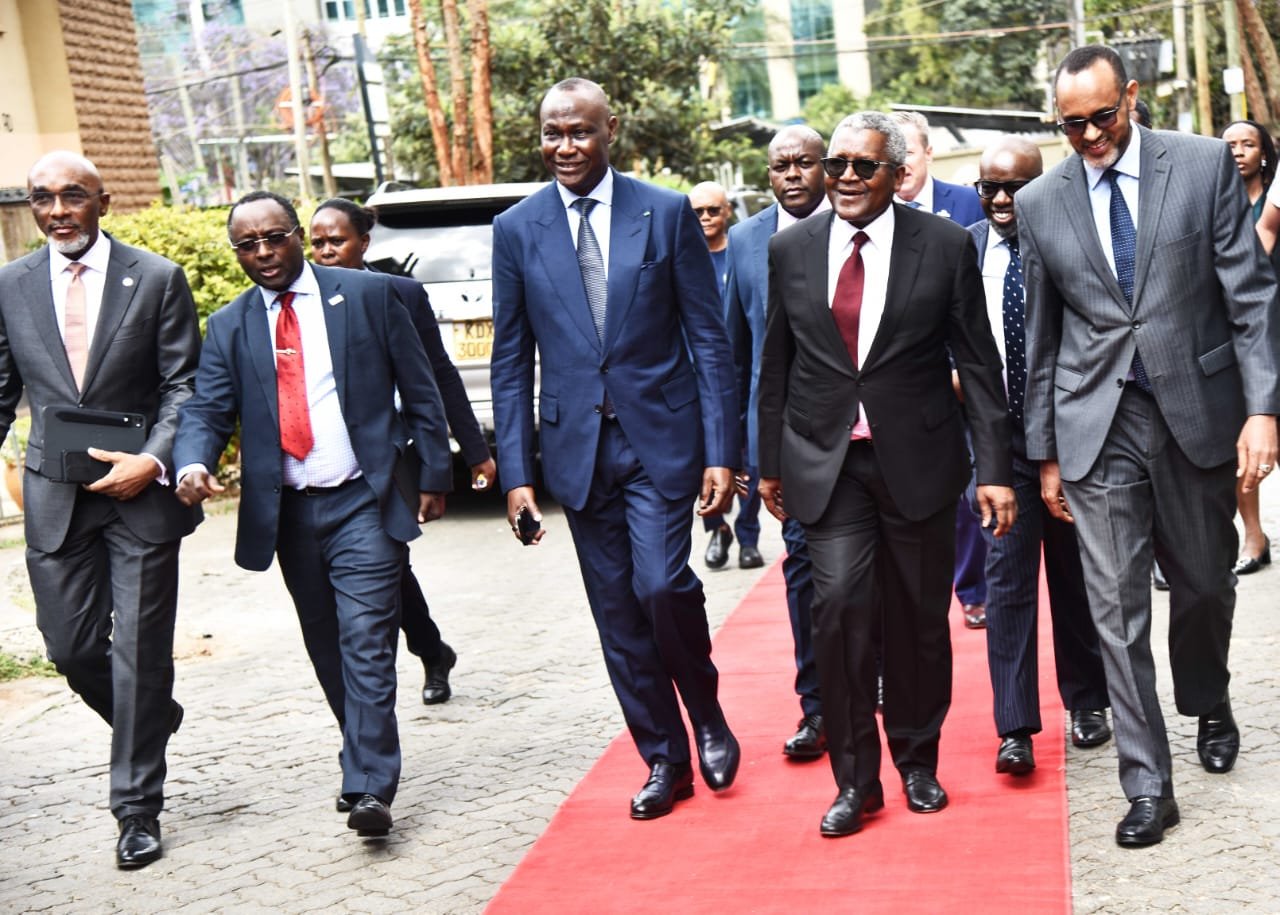
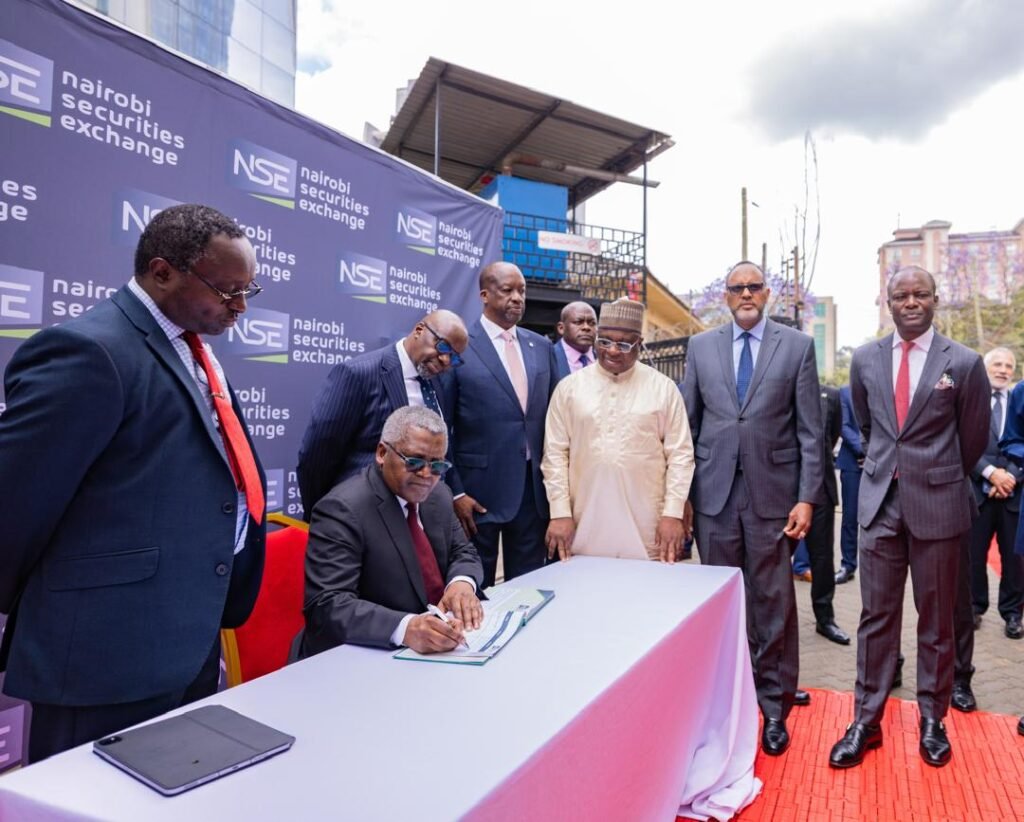
Caption: Alhaji Aliko Dangote (second left), President/Chief Executive of Dangote Industries Limited, signing a document during the Roadshow for the Initial Public Offering (IPO) at the Nairobi Securities Exchange (NSE). He is flanked from left by CEO of the NSE Frank Mwiti; Tom Nulwa, Chairman of NSE; Ugas S. Mohammed, Chairman, Capital Markets Authority (MCA) of Kenya; Dr. Umaru Kwairanga, Chairman of the Nigerian Exchange Group Plc; and Temi Popoola, CEO, NGX Group.
Market Update For September 30, 2026
The Nigerian equities market extended its decline on Wednesday, September 30, as investors continued to take profits in selected large-cap stocks ahead of the October 1 Independence Day holiday.
The session came after a prolonged period of strong gains in the market, leaving investors increasingly focused on securing profits from stocks that had appreciated significantly. The selling pressure was most visible across some banking, telecommunications and consumer-related stocks, although activity remained firm in several counters.
The decline was largely driven by losses in heavyweight stocks, with FIDELITYBK falling 6.07%, MTNN declining 3.01% and ACCESSCORP losing 2.25%. HBMNG dropped 1.53%, DANGSUGAR shed 1.45%, UBA declined 1.20%, STANBIC fell 0.61%, while GTCO slipped 0.38%.
The performance of these large-cap stocks had a notable impact on the broader index because of their relatively significant market weights. The weakness suggests that investors were willing to reduce exposure to selected equities after the market’s recent rally, even as interest remained visible in other stocks.
The profit-taking also came as the market approached the end of September and the start of a new month. Investors may have been repositioning portfolios ahead of the holiday break, while the strong year-to-date performance of the Nigerian market provided an opportunity for some participants to lock in accumulated gains.
However, the decline in the benchmark index did not translate into broadly negative market breadth. A number of stocks recorded gains during the session, indicating that buying interest remained present outside the major decliners. This divergence between the index and individual stock performance highlights the selective nature of trading as investors moved between sectors and counters.
Trading activity remained relatively strong, with substantial volumes changing hands during the session. VFDGROUP was particularly active, accounting for a large share of the day’s traded volume. The heavy activity in the stock contributed significantly to overall market turnover, while GTCO remained one of the most prominent counters by transaction value.
The concentration of trading in a few stocks also suggests that liquidity remained available despite the decline in the benchmark. Investors continued to execute large transactions in selected counters, pointing to ongoing portfolio adjustments rather than a broad withdrawal of market participation.
Attention will now shift towards the October trading cycle, with investors expected to assess third-quarter corporate earnings expectations, valuations, monetary conditions and broader economic developments. The market’s strong year-to-date performance may also keep valuation and profit-taking considerations in focus, particularly in stocks that have recorded substantial price appreciation.
The performance of the naira, interest-rate environment and liquidity conditions will remain important factors for equities. Lower interest rates can influence the relative attractiveness of equities and fixed-income assets, while corporate earnings will determine whether recent share-price gains are supported by improvements in company fundamentals.
The banking sector is likely to remain closely watched given its large representation in the market and its sensitivity to monetary policy, interest rates, liquidity and economic activity. Telecommunications and consumer stocks will also remain important as investors assess earnings prospects, operating costs and the impact of macroeconomic conditions on corporate performance.
Meanwhile, developments in the international oil market provided a positive backdrop for Nigeria’s external-sector outlook. Crude prices rose on Wednesday as stalled US-Iran peace discussions and tighter US fuel markets supported prices.
Brent crude traded around $103.71 per barrel, while West Texas Intermediate stood at about $91.98. Brent was heading for a monthly gain of roughly 14%, which would represent its strongest monthly increase since July, while WTI was on track for a gain of about 5.5%.
Oil prices were supported by uncertainty surrounding efforts to resolve tensions between Washington and Tehran. Qatar said it remained hopeful that shuttle diplomacy between the two countries could lead to progress, although US President Donald Trump denied reports that he was willing to provide Iran with sanctions relief and release frozen funds in exchange for concrete steps on its nuclear programme.
Saudi Arabia also resumed oil tanker loadings from its Red Sea port of Yanbu after restarting operations on its East-West Pipeline. The development added another factor to the market’s assessment of regional supply and transportation conditions.
For Nigeria, sustained strength in crude prices remains relevant because oil exports continue to influence foreign exchange earnings, government revenues and external-sector conditions. However, the impact on domestic equities will also depend on oil production levels, fiscal management, exchange-rate developments and the ability of companies to translate a stronger macroeconomic environment into improved earnings.
With the Nigerian market entering a new month after a strong period of appreciation, investors are likely to remain selective. The combination of recent gains, corporate fundamentals and changing macroeconomic conditions could result in continued rotation between stocks as market participants reassess their positions.
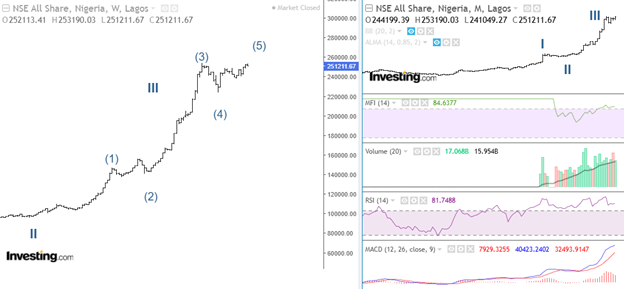
The NGX All-Share Index fell by 701.53 points, or 0.28%, to close at 251,211.67 points from 251,913.20 points on Tuesday, while market capitalisation declined by ₦425.73 billion to ₦163.10 trillion. The market’s year-to-date return eased to 61.43%. Market breadth was slightly positive, with 30 gainers against 29 losers and 87 stocks unchanged. Trading remained active, with 878.32 million shares worth ₦32.31 billion exchanged in 44,396 deals. VFDGROUP led volume with 367.32 million shares, while GTCO recorded the highest transaction value. Among the major market movers, FIDELITYBK fell 6.07%, MTNN declined 3.01%, ACCESSCORP lost 2.25%, HBMNG dropped 1.53%, DANGSUGAR shed 1.45%, UBA fell 1.20%, STANBIC declined 0.61% and GTCO slipped 0.38%. HMCALL was the top gainer, rising 10.00% to ₦3.41, followed by CORNERST at 9.80% to ₦5.60, LIVINGTRUST at 9.79% to ₦3.14, ABCTRANS at 9.76% to ₦6.75 and ROYALEX at 9.52% to ₦1.15. On the losing side, LEARNAFRCA fell 10.00% to ₦7.65, THOMASWY declined 9.80% to ₦2.67, SOVRENINS dropped 6.78% to ₦2.20, GUINEAINS lost 6.67% to ₦0.70, while CONHALLPLC declined 5.07% to ₦7.12.