Neimeth International Pharmaceuticals Plc was incorporated in August 1957 and commenced operations in January 1958. The company was formerly associated with Pfizer, which divested through a management buyout in May 1997. It is listed on the Nigerian Exchange, having been listed on 21 September 1979.
This history matters because pharmaceutical manufacturing is not simply a distribution business. It requires product registration, quality control, manufacturing expertise, established distribution channels and trust among healthcare professionals and consumers.
Current price: N7.65
Rating: Buy
Price projection: N11, N13, and N16
Technical Analysis
In this report, we shall use the following tools and analysis methods:
Elliott’s wave theory to understand the overall market sentiment
Fibonacci tools to determine support and resistance levels
The Relative Strength Index and volume to evaluate the market’s strength
The Money Flow Index to determine the market liquidity
Moving average and MACD to understand the nature of the trend
Top-down analysis to know the best investment position
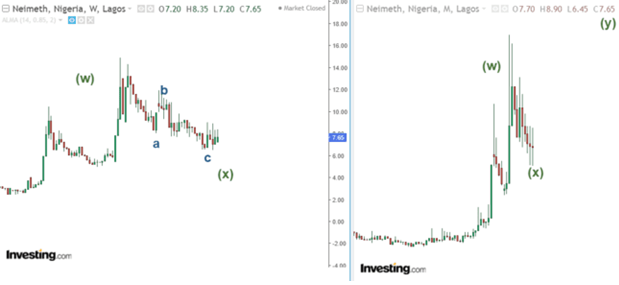
Elliott wave analysis
Weekly chart: Market overview
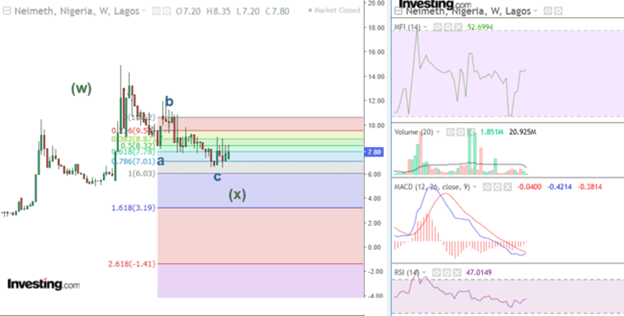
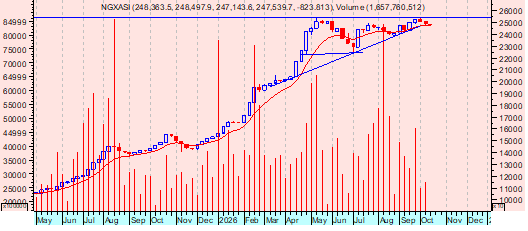
Neimeth retraced to the 1.0 Fibonacci level and commenced its recovery phase on the weekly chart. In line with this performance, the stock’s liquidity and momentum improved despite low trading volume. MACD also sustained its divergence signal, preparing investors for a trend reversal.
Daily chart: Investment opportunity
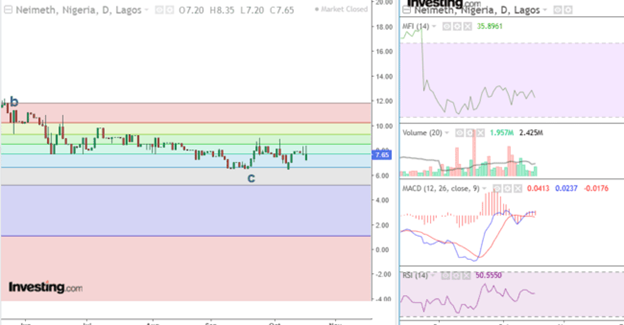
On the daily chart, Neimeth sustained strong bullish volume and momentum. In line with this performance, MACD retained its bullish signal. These sentiments should attract investment when the stock’s liquidity improves. Investors should watch N6 as a potential support level with N11, N13, and N16 as profit-taking zones.
SWOT analysis
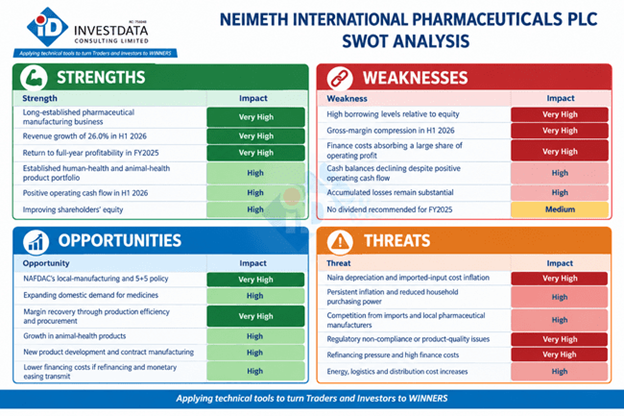
Neimeth’s SWOT profile reflects a pharmaceutical manufacturer with an established operating history, strong recent revenue growth and a return to profitability, supported by opportunities arising from Nigeria’s drive towards local pharmaceutical production.
However, the company continues to face high borrowing levels, margin compression, significant finance costs and declining cash balances. While expanding healthcare demand and improved manufacturing efficiency could strengthen its earnings outlook, the benefits will depend on management’s ability to convert revenue growth into sustainable profit and cash flow.
For investors, Neimeth offers a recovery opportunity rather than a fully established growth-and-income proposition. Confirmation of improving margins, lower debt pressure and stronger cash generation would materially strengthen the investment case.