
Market Update For October 26, 2026
The Nigerian equities market strengthened on Monday, October 26, 2026, as renewed buying interest in heavyweight stocks lifted the benchmark index above the 250,000-point psychological threshold. The rally added ₦2.64 trillion to market capitalisation, reflecting strong price appreciation in selected large-cap stocks across the industrial goods, financial services and energy sectors. However, the decline in trading activity and negative market breadth indicated that the advance was not supported by broad-based participation.
The positive performance followed Friday’s close at 247,222.27 points, with the market benefiting from significant gains in DANGCEM, NGXGROUP and FIRSTHOLDCO. The performance of these stocks helped offset losses across several other equities, allowing the benchmark index to record a substantial advance despite the greater number of declining stocks.
Although the market’s upward movement suggests renewed investor confidence, the uneven distribution of gains points to a selective investment strategy. Investors appear to be concentrating on stocks with significant market influence while maintaining a cautious approach towards other equities. This divergence between index performance and market breadth remains an important consideration in assessing the sustainability of the current rally.
DANGCEM emerged as a major driver of the market’s positive performance, gaining 10.00% to close at ₦1,222.10. The stock’s advance provided substantial support to the benchmark index, reflecting its influence within the industrial goods sector and the broader equities market.
NGXGROUP also recorded a strong performance, appreciating by 8.20% to ₦165.00, while FIRSTHOLDCO advanced by 7.56% to ₦155.00. These gains demonstrated renewed demand for selected stocks and contributed to the overall increase in market capitalisation.
The financial services sector also recorded positive movements among several major banking stocks. ACCESSCORP gained 4.15%, GTCO advanced by 2.54%, and ZENITHBANK rose by 1.26%. UBA added 0.25%, while ARADEL appreciated by 2.48%, providing additional support to the market.
The performance of these equities highlights the importance of large-cap stocks in determining the direction of the Nigerian equities market. When stocks with substantial market weightings record significant price gains, they can lift the benchmark index even when selling pressure persists across other segments of the market.
However, the concentration of gains in selected stocks raises questions about the strength of the broader market recovery. A more sustainable rally would typically require increased participation across different sectors, accompanied by improvements in market breadth and trading activity.
Despite the strong index performance, market breadth remained negative, with 31 stocks declining against 26 gainers, while 89 stocks closed unchanged.
The higher number of losers suggests that selling pressure remained evident across several listed equities, even as the benchmark index advanced. This divergence indicates that the market’s positive performance was driven largely by the appreciation of selected heavyweight stocks rather than a broad improvement in investor sentiment.
Negative breadth during an advancing session does not necessarily invalidate the bullish trend. However, persistent divergence between the benchmark index and the number of advancing stocks may signal that the rally is becoming increasingly concentrated.
If buying interest continues to focus on a limited number of large-cap stocks, the index could maintain its upward trajectory while a significant portion of the market struggles to recover. Conversely, an improvement in market breadth would suggest that investor confidence is spreading across more stocks and sectors.
The performance of declining equities also points to continued portfolio adjustments. Some investors may be locking in profits after previous price advances, while others may be reducing exposure to stocks facing weaker demand.
Consequently, the market’s direction in subsequent sessions will depend not only on the performance of the leading stocks but also on whether buying interest broadens to other equities.
Market activity moderated during the session, with approximately 329.51 million shares traded, valued at ₦25.43 billion across 43,647 deals.
The subdued turnover contrasted with the strong appreciation in the benchmark index, suggesting that the rally did not coincide with a broad increase in trading activity. Although price gains were substantial, the available figures indicate that investor participation remained selective.
ZENITHBANK led trading by volume, with 25.92 million shares exchanged, representing approximately 7.87% of total market volume. UBA and ACCESSCORP followed among the notable contributors, accounting for 7.28% and 5.46% of total volume, respectively.
On the value side, DANGCEM recorded the highest turnover at ₦6.39 billion, equivalent to 25.11% of the day’s total traded value. The stock’s dominance in value traded reinforces its importance to the session’s overall performance.
ZENITHBANK and ARADEL were also among the notable contributors to traded value, reflecting continued activity in major financial and energy-related stocks.
The relationship between price performance and trading activity will be important in determining the strength of the rally. An advance accompanied by rising volume and value would provide stronger evidence of sustained demand. In contrast, further gains amid weakening turnover could suggest that the market lacks sufficient participation to maintain its momentum across a wider range of stocks.
Investors should therefore distinguish between an index-led rally and a broad-based recovery. While both can produce positive returns, the latter generally provides stronger evidence that bullish sentiment is spreading throughout the market.
The industrial goods sector attracted attention following DANGCEM’s 10.00% gain. Given the stock’s importance to the benchmark index, its performance was a significant factor in Monday’s advance.
The financial services sector also contributed through gains in NGXGROUP, FIRSTHOLDCO, ACCESSCORP, GTCO, ZENITHBANK and UBA. However, the varying magnitude of these advances indicates that buying interest was concentrated in particular stocks rather than evenly distributed across the sector.
ARADEL’s gain also added to the positive performance among energy-related equities. The movement of energy stocks remains relevant to investor assessments of Nigeria’s economic outlook, given the importance of the petroleum industry to foreign exchange earnings and government revenue.
Nevertheless, the session’s performance should not be interpreted as evidence of a uniform sector-wide recovery. Individual stock fundamentals, valuations, liquidity and investor positioning can produce substantially different outcomes within the same sector.
For investors, this reinforces the importance of evaluating individual companies alongside broader market trends. Strong index performance may create opportunities, but stock selection remains important when market breadth is weak and trading activity is concentrated.
Technical Analysis and Market Outlook
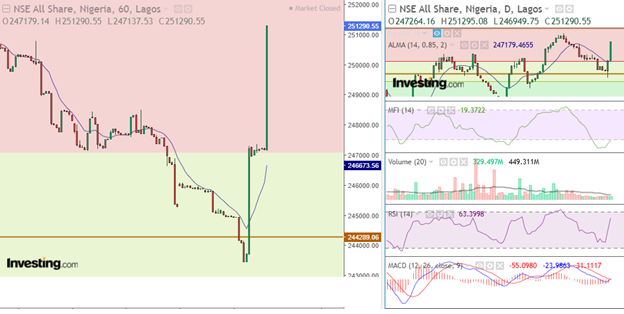
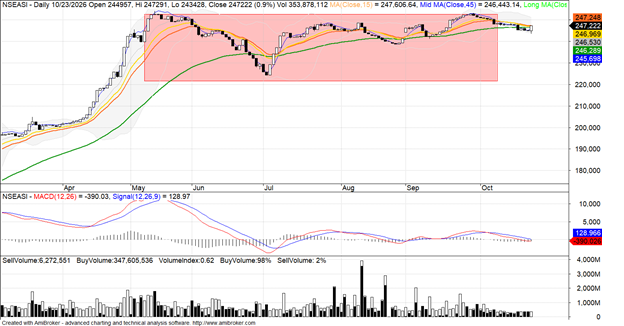
The NGX All-Share Index gained 4,068.27 points to close at 251,290.54 points, representing a 1.65% advance from Friday’s 247,222.27-point close. The recovery moved the index above the psychologically important 250,000-point level, strengthening its near-term technical outlook.
From a price-action perspective, the move above 250,000 points suggests that buyers regained control during the session after the market closed below that level on Friday. Maintaining this position would help preserve the current upward momentum and improve the prospects of a further test of higher resistance levels.
The immediate support zone is around 250,000 points, which may serve as an important reference point for market participants. A sustained hold above this level would reinforce the recovery, while a decisive break below it could expose the index to renewed selling pressure.
On the upside, the 252,000–255,000-point range represents a potential resistance zone to monitor. A sustained breakout above this area, supported by improving trading activity and broader market participation, could strengthen the bullish outlook. Failure to clear the resistance zone may encourage profit-taking and short-term consolidation.
Market breadth remains a critical confirmation indicator. With 31 losers against 26 gainers, the session’s advance lacked broad participation. If the index continues rising while declining stocks consistently outnumber advancing equities, the rally could become vulnerable to reversals in heavyweight stocks.
Trading volume is another important consideration. The approximately 329.51 million shares exchanged during the session provide a basis for monitoring whether future advances attract stronger participation. An increase in volume alongside further price appreciation would provide additional confirmation of demand, while declining turnover could weaken confidence in the sustainability of the upward movement.
The market’s short-term direction will therefore depend on three key factors: the ability of the ASI to sustain its position above 250,000 points, the strength of buying interest in heavyweight stocks, and the extent to which participation broadens across the market.
Investors should avoid relying solely on the benchmark index when assessing market strength. Monitoring market breadth, trading activity and individual stock performance will provide a more complete picture of underlying conditions.
Oil Market
In the international commodities market, crude oil prices declined on Monday as expectations of easing tensions between the United States and Iran reduced immediate concerns about supply disruptions. However, continued attacks on Saudi Arabia kept geopolitical risks in focus and limited the improvement in market sentiment.
Brent crude futures fell by $2.03, or 1.7%, to $114.70 per barrel, while US West Texas Intermediate crude declined by $2.60, or 2.5%, to $100.71 per barrel.
The declines followed a strong performance in the previous week, when Brent gained 6% and WTI advanced by 2.3%. Despite Monday’s retreat, both benchmarks remained elevated amid concerns about potential disruptions to global oil supplies.
The outlook for crude prices remains sensitive to developments in the Middle East. Any reduction in geopolitical tensions could ease supply concerns and put downward pressure on prices, while further attacks on key production or transport infrastructure could trigger renewed increases.
For Nigeria, international oil prices remain an important macroeconomic indicator because of their implications for export earnings, foreign exchange supply and government revenue. However, the domestic benefits of higher crude prices also depend on production volumes, export receipts and the management of public finances.
Consequently, movements in the global oil market will remain relevant to investors assessing Nigeria’s economic outlook and the potential implications for listed companies across the energy, industrial and financial services sectors.
Market Summary
The Nigerian equities market closed higher on Monday, October 26, 2026, as the NGX All-Share Index (ASI) gained 4,068.27 points, or 1.65%, to settle at 251,290.54 points from 247,222.27 points recorded in the previous session. Market capitalisation increased by ₦2.64 trillion to ₦163.16 trillion, while the year-to-date return rose to 61.48%. Trading activity stood at approximately 329.51 million shares valued at ₦25.43 billion across 43,647 deals, although turnover weakened despite the strong index performance. Market breadth was negative, with 26 gainers, 31 losers and 89 unchanged stocks, reflecting limited participation in the rally. Buying interest in heavyweight stocks, particularly DANGCEM, NGXGROUP and FIRSTHOLDCO, supported the market’s advance, alongside gains in ACCESSCORP, GTCO, ARADEL, ZENITHBANK and UBA. DANGCEM led the gainers, rising 10.00% to ₦1,222.10, followed by HONYFLOUR (+9.78%) to ₦19.65, ROYALEX (+9.18%) to ₦1.07, NGXGROUP (+8.20%) to ₦165.00 and FIRSTHOLDCO (+7.56%) to ₦155.00. On the losers’ table, ABCTRANS declined 9.59% to ₦6.60, CAVERTON fell 9.38% to ₦4.35, LIVESTOCK shed 9.09% to ₦15.50, CHAMPION lost 8.16% to ₦9.00, and PZ dropped 7.61% to ₦63.70. ZENITHBANK led trading by volume with 25.92 million shares, accounting for 7.87% of total volume, while DANGCEM recorded the highest traded value at ₦6.39 billion, representing 25.11% of total market value.