Quarter Under Preview: -THIRD QUARTER 2026
Current Share Price: N119.00
Latest Final Dividend: N8.75
Latest Interim Dividend: N1.50
Estimated Beta Value: 0.75x
Estimated Fair Value: N135.00
Ratings: Buy
Analyst: Jeariogbe Tunde Segun
The Company
Historical Background of Zenith Bank Plc
Zenith Bank Plc is one of Nigeria’s leading financial institutions, established in May 1990 by Jim Ovia. The bank commenced operations in July 1990, after being granted a commercial banking licence by the Central Bank of Nigeria (CBN).
From its inception, Zenith Bank focused on technology-driven banking, operational efficiency, strong corporate governance, and customer service. These priorities supported its growth from a relatively small financial institution into a major player in Nigeria’s banking industry, serving individuals, small and medium-sized enterprises, large corporations, and public-sector organizations.
Zenith Bank became a public limited company during the banking sector consolidation exercise of 2004 and became listed on the Nigerian Stock Exchange, now the Nigerian Exchange Limited (NGX), in October 2004. Its listing broadened public participation in the bank’s ownership and strengthened its access to the capital market. Over the years, the bank expanded its branch network, electronic banking services, corporate banking operations, and international presence, including operations in selected African markets and the United Kingdom. It has also invested significantly in digital banking infrastructure to improve transaction processing, customer convenience, and service delivery.
Today, Zenith Bank operates as a major commercial banking group, providing services such as deposits mobilization, loans and advances, corporate finance, money-market activities, trade finance, and electronic banking. Its group structure includes subsidiaries in Ghana, the United Kingdom, Sierra Leone and The Gambia, alongside Zenith Pensions Custodian Limited and Zenith Nominees Limited. The bank’s shares trade on the NGX under the ticker ZENITHBANK, and it was admitted to the Exchange’s Premium Board in August 2015. Its established market presence, diversified banking services and regional reach make it an important institution to assess when examining Nigeria’s banking sector and the investment prospects of listed financial stocks.
Statement of Comprehensive Income
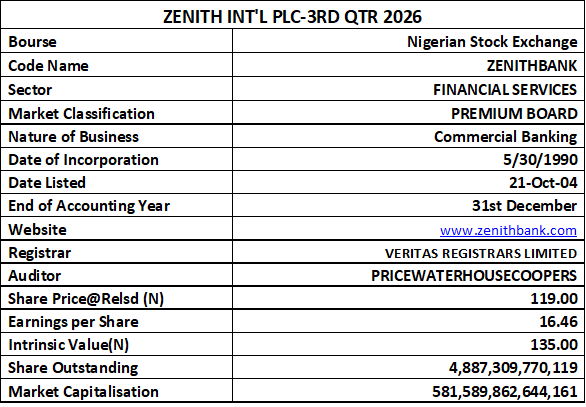
Zenith Bank Plc recorded gross earnings of ₦2.865 trillion in the first nine months of 2026, representing a 15.02% decline from ₦3.372 trillion reported in the corresponding period of 2025. Interest income also declined by 4.50% to ₦2.617 trillion from ₦2.740 trillion. However, the 15.41% reduction in interest expenses to ₦688.727 billion helped sustain net interest income at ₦1.928 trillion, marginally higher than the ₦1.927 trillion reported in 2025. This indicates that despite the moderation in income generation, the bank maintained its net interest earnings through improved funding cost management.
Operating expenses increased by 17.44% to ₦838.763 billion from ₦714.198 billion, reflecting rising operational cost pressures. Depreciation expenses rose significantly by 39.89% to ₦52.797 billion, while amortization rose by 8.08% to ₦11.484 billion. Despite these cost pressure, profit before tax grew marginally by 1.24% to ₦928.797 billion from ₦917.412 billion, suggesting some resilience in the bank’s underlying operating performance. However, the substantial increase in the tax charge by 65.12% to ₦252.971 billion significantly affected the bottom line.
Consequently, profit after tax fell by 11.56% to ₦675.826 billion, compared with ₦764.204 billion in the similar period of 2025. Total comprehensive income also dropped considerably by 41.91% to ₦508.283 billion from ₦875.031 billion, indicating weaker overall comprehensive performance.
Overall, Zenith Bank’s Q3 2026 performance reflects resilience in pre-tax earnings but increasing operating costs and a significantly higher tax burden have weakened earnings growth. Investors will need to monitor cost efficiency, revenue recovery and the sustainability of earnings growth in subsequent reporting periods.
Statement of Financial Position
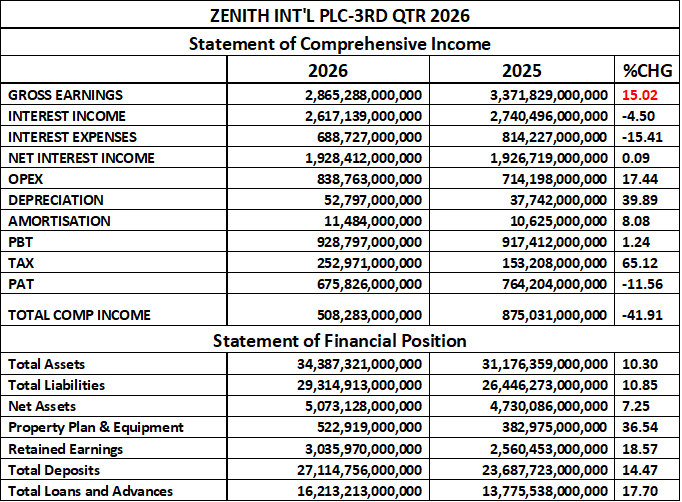
Zenith Bank Plc recorded a 10.30% growth in total assets to ₦34.387 trillion as at Q3 2026, compared with ₦31.176 trillion in the corresponding period of 2025. Total liabilities also increased by 10.85% to ₦29.315 trillion, while net assets grew by 7.25% to ₦5.073 trillion. The growth in the balance sheet reflects an expansion in the bank’s operations, although liabilities grew faster than assets, indicating a marginal increase in balance-sheet leverage. Meanwhile, retained earnings increased by 18.57% to ₦3.036 trillion, suggesting continued profit retention and a strengthening of the bank’s accumulated earnings base.
On the funding and lending side, total deposits rose by 14.47% to ₦27.115 trillion, while total loans and advances increased by 17.70% to ₦16.213 trillion. The faster growth in loans relative to deposits indicates increased deployment of deposit funds into lending activities, which could support future interest income, although asset quality and impairment risks require close monitoring. Property, plant and equipment also increased significantly by 36.54% to ₦522.919 billion, reflecting higher investment in the bank’s physical and operational infrastructure. Overall, the balance sheet shows healthy growth in assets, deposits, retained earnings and lending activities, providing a positive indication of business expansion and capacity for future earnings.
Financial Strength/Solvency Ratio
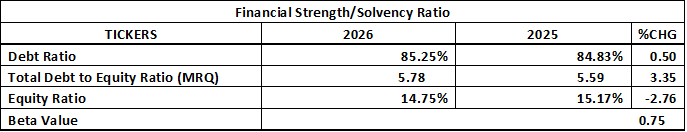
Zenith Bank’s financial strength and solvency ratios indicate a relatively high dependence on liabilities to finance its assets, with the debt ratio rising marginally by 0.50% to 85.25% from 84.83% in 2025, while the debt-to-equity ratio increased by 3.35% to 5.78x from 5.59x, reflecting a slight increase in financial leverage. Correspondingly, the equity ratio declined by 2.76% to 14.75% from 15.17%, indicating a marginal reduction in the proportion of assets financed by shareholders’ funds.
Although the figures reflect the highly leveraged nature of banking operations, the rising leverage and declining equity ratio warrant monitoring in assessing capital adequacy and long-term financial resilience. Meanwhile, the bank’s beta of 0.75 suggests relatively lower share-price volatility compared with the broader market, indicating a comparatively defensive risk profile.
Profitability Ratios
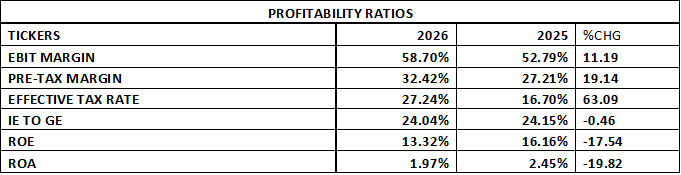
Zenith Bank recorded an improvement in operating profitability, with EBIT margin rising by 11.19% to 58.70% from 52.79% in 2025, while pre-tax profit margin increased by 19.14% to 32.42% from 27.21%. These improvements suggest better operating efficiency and stronger profit generation before tax. However, the effective tax rate increased significantly by 63.09% to 27.24% from 16.70%, indicating a substantially higher tax burden on earnings. The interest expense to gross earnings ratio (IE to GE) improved marginally to 24.04% from 24.15%, representing a 0.46% reduction and suggesting relatively stable interest cost management.
Despite the improvement in operating and pre-tax margins, shareholders’ returns weakened, as return on equity (ROE) declined by 17.54% to 13.32% from 16.16%, while return on assets (ROA) fell by 19.82% to 1.97% from 2.45%. This indicates that the growth in the bank’s asset and equity bases has not translated into proportionate improvements in returns. Overall, Zenith Bank’s profitability profile reflects stronger operating and pre-tax margins but weakening returns on shareholders’ funds and total assets, with the rising tax burden further constraining earnings conversion.
Efficiency Ratios
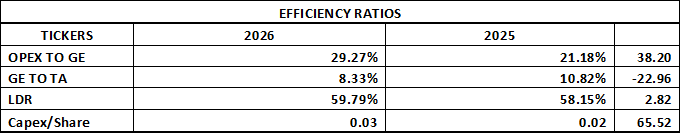
Zenith Bank’s efficiency ratios reflect increasing operating cost pressures, as operating expenses to gross earnings (OPEX to GE) rose significantly by 38.20% to 29.27% from 21.18% in 2025, indicating a higher proportion of gross earnings consumed by operating expenses. Gross earnings to total assets (GE to TA) declined by 22.96% to 8.33% from 10.82%, suggesting reduced revenue generation relative to the bank’s expanding asset base.
Meanwhile, the loan-to-deposit ratio (LDR) increased moderately by 2.82% to 59.79% from 58.15%, indicating a higher deployment of customer deposits into loans, although the ratio still suggests considerable deposit funding capacity remains available for further lending. Capital expenditure per share also increased by 65.52% to ₦0.03 from ₦0.02, reflecting higher investment in infrastructure and operational capacity. Overall, the ratios point to rising operating cost inefficiency and weaker asset utilization, which could constrain future profitability if revenue growth does not sufficiently offset the increase in operating expenses.
Investment/Valuation Ratios
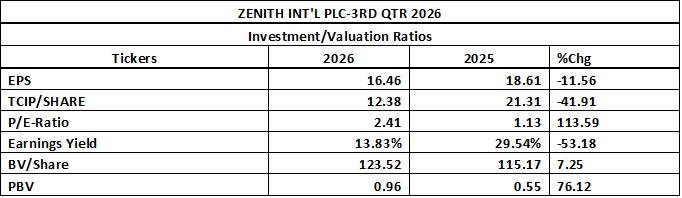
Zenith Bank’s investment and valuation ratios indicate a moderation in earnings performance, with earnings per share (EPS) declining by 11.56% to ₦16.46 from ₦18.61 in 2025. Total comprehensive income per share (TCIP/share) also declined by 41.91% to ₦12.38 from ₦21.31, reflecting the significant drop in total comprehensive income. Consequently, the price-to-earnings (P/E) ratio increased by 113.59% to 2.41x from 1.13x, while earnings yield fell to 13.83% from 29.54%, representing a 53.18% decline. Although the P/E ratio remains relatively low, the decline in earnings yield reflects reduced earnings support relative to the share price.
On the balance-sheet valuation front, book value per share improved by 7.25% to ₦123.52 from ₦115.17, indicating growth in shareholders’ funds on a per-share basis. However, the price-to-book value (P/BV) ratio increased by 76.12% to 0.96x from 0.55x, suggesting that the market valuation has moved closer to the bank’s underlying book value. Overall, Zenith Bank trades below its book value and at a relatively low earnings multiple, which may indicate valuation attractiveness. Nevertheless, the declining EPS and comprehensive income per share highlight the need for caution, as sustained earnings recovery will be important in supporting further share-price appreciation.
Zenith Bank Plc – Q3 2026 Final Investment Verdict
Zenith Bank’s Q3 2026 performance presents a mixed investment picture. The bank maintained positive earnings growth before tax, expanded its asset base by 10.30%, increased deposits by 14.47% and grew retained earnings by 18.57%. Its balance sheet remains substantial, with net assets of ₦5.07 trillion and book value per share of ₦123.52. However, the 11.56% decline in profit after tax, weakening ROE and ROA, rising operating expenses and a 41.91% decline in total comprehensive income are notable concerns. The bank’s strong deposit franchise and balance-sheet expansion remain positives, but the deterioration in earnings quality and operating efficiency calls for caution.
Investment/Valuation Verdict:
Zenith Bank remains fundamentally attractive, supported by its strong deposit franchise, growing retained earnings, relatively low price-to-book valuation and capacity to sustain dividend payments. Its beta of 0.75 also suggests relatively lower historical market sensitivity. However, rising operating expenses, declining post-tax earnings, weakening returns on equity and assets, and the higher tax burden indicate that profitability and operational efficiency require improvement.
Conclusion: At the prevailing market valuation, Zenith Bank offers reasonable long-term investment potential, particularly for investors seeking dividend income and capital appreciation. However, the recommendation is supported by its balance-sheet strength and valuation rather than strong current earnings momentum. A conservative intrinsic value estimate of ₦135 per share suggests moderate upside, making the stock a BUY, preferably on price weakness.